Best payment methods, platforms & tools for freelancers
Compare the best payment methods, platforms, and tools for freelancers, including fees, speed, global availability, currencies, and ease of use.
Summary
Most platforms now invoice and collect, but the invoice stays in your name. Ruul issues it as the legal counterparty for 5%, with no company needed. Wise suits cheap conversions, Payoneer marketplace earnings and Stripe checkout.
On this page
- Two types of platforms: Know which one you actually need
- Payment method categories: A practical map
- What to evaluate in a payment platform
- The best payment platforms for freelancers
- Platform comparison table
- How invoice size changes the cheapest option
- Choosing the right platform for your situation
- Most freelancers use more than one platform
- FAQs
Every payment decision you make as a freelancer has a direct effect on your income. Not in some abstract, long-term sense. Right now, on every invoice you send. The platform you choose determines how much you keep, how quickly you get paid, whether your client can actually pay you, and whether you’re exposed to compliance problems you didn’t know existed.
Upwork’s Future Workforce Index 2026 found that 38% of skilled U.S. knowledge workers now freelance, up from 28% a year earlier. The payment infrastructure supporting that workforce has not kept pace. Most freelancers end up with a patchwork of tools, chosen based on what clients asked for, not what actually serves their income.
This guide evaluates the main payment platforms available to freelancers: what they do well, where they fall short, and which one fits your specific situation. It also draws a distinction that most guides skip entirely: the difference between platforms that move money and platforms that handle the full payment workflow. That distinction shapes every decision that follows.
Two types of platforms: Know which one you actually need
Most comparisons treat all payment platforms as equivalent alternatives. They’re not. They solve different problems.
A payment transfer platform moves money, and many now add invoices and payment links too. The invoice still goes out in your name, though. You chase late payments yourself, you manage currency conversion, and the compliance side of each client stays with you.
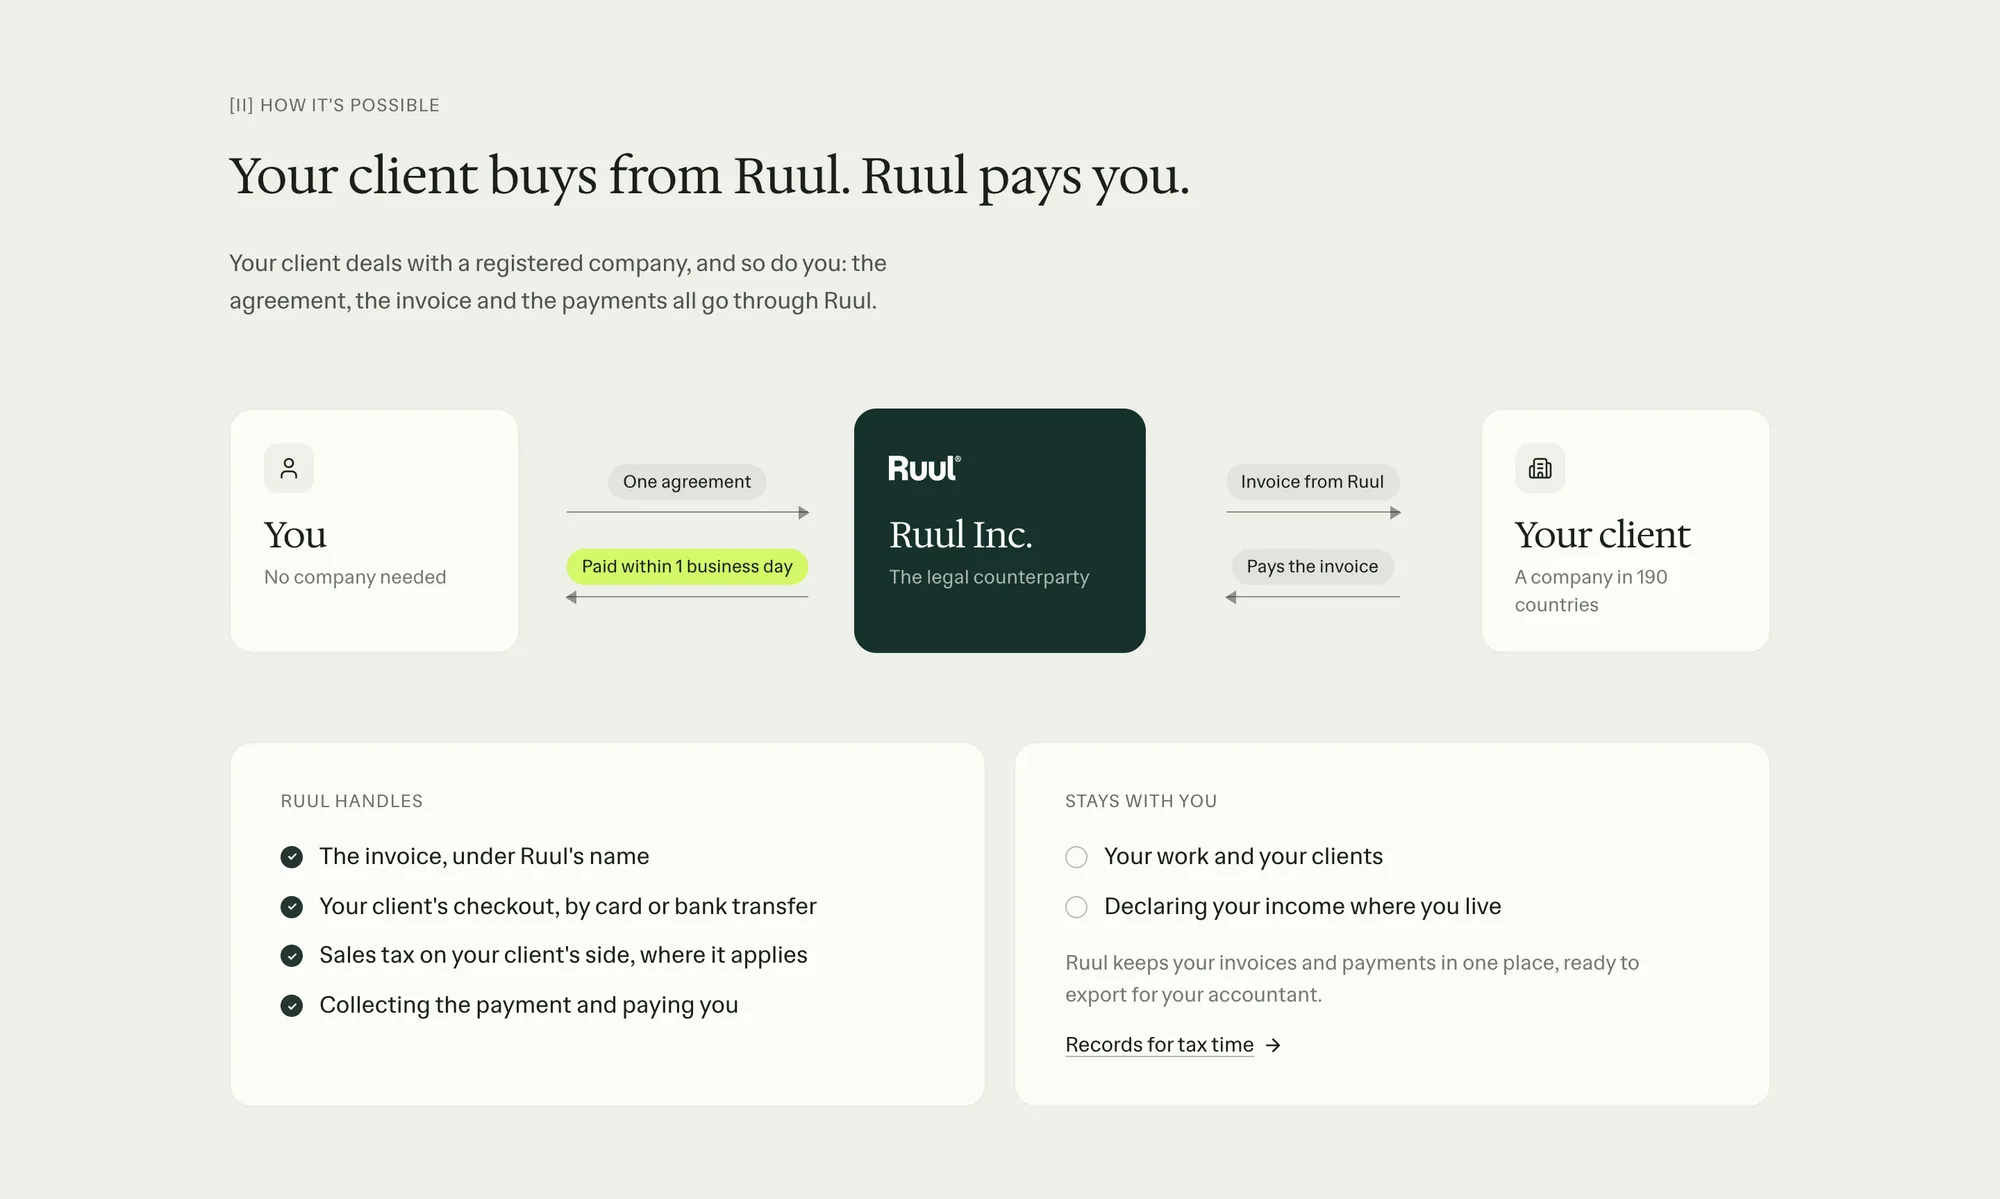
An end-to-end payment platform goes further. It becomes the legal counterparty: it contracts with you, issues the invoice to your client under its own name, collects the payment and pays you. Most of the admin goes with it, and the paper trail is built in automatically.
Most freelancers start with transfer-only platforms and hit limits when client volume grows, when international clients appear, or when they realize they have no company registration and can’t legally invoice in certain markets. If you need to invoice clients without a registered company across 190 countries, you need an end-to-end platform that acts as the legal counterparty.
That boundary between transfer-only and end-to-end is the analytical framework this guide uses throughout.
Payment method categories: A practical map
Four broad categories of payment methods are available to freelancers. Understanding the taxonomy helps you evaluate platforms within each category.
Bank transfers (ACH for domestic US, SEPA within the EU, SWIFT for international wires) work directly through banking infrastructure. They’re trusted and widely accepted. Domestic networks like ACH and SEPA process payments in batches, so a transfer usually takes one to three business days and costs little or nothing, and an instant SEPA transfer in euros arrives within seconds where both banks offer it. International wires are slower and cost more: SWIFT is a messaging network that tells banks what to do, and the money can pass through several banks on its way to you, with fees and an exchange rate markup along the way.
Digital payment platforms (Wise, PayPal, Payoneer, Stripe) layer technology on top of banking to make transfers faster, cheaper, or broader in reach. Each has a different fee model, geographic coverage, and level of service for freelancers specifically.
Freelance marketplace payment systems, built into platforms like Upwork and Fiverr, work well inside those ecosystems. They’re not designed for direct client invoicing outside the marketplace context.
Cryptocurrency offers a parallel payment rail entirely outside the traditional banking system. For freelancers who want to invoice clients normally and withdraw earnings in USDC, Ruul’s Crypto Payout makes that possible without asking clients to change how they pay.
What to evaluate in a payment platform
Seven criteria determine whether a platform is genuinely right for you.
Supported countries and currencies. A platform operating in 190 countries is not the same as one operating in 30. Check both where the platform sends and where it receives. Some platforms receive well but offer few ways to withdraw in your specific country.
Fee structure. Percentage fees and flat fees behave very differently at scale. A 5% flat commission on a $10,000 invoice is $500. A 3.49% processing fee, a 1.5% international fee and a 3% currency conversion spread add up to almost 8% on the same invoice, about $800. Run the math on your actual invoice values before assuming that lower-looking percentages are actually cheaper.
Transfer speed. How long you wait affects cash flow directly. Platforms that pay you within one business day operate on different economics than those with 3 to 5 business day settlement windows. Count the withdrawal too: on most platforms, the money lands in your platform balance first, and moving it to your bank can add one to three business days. Our guide to how long freelance payments take has the timeline for each method.
Client friction. Does your client need to create an account somewhere to pay you? Client friction is a real barrier to getting paid on time. The less your client has to do, the faster you receive funds.
Holds and reversals. Check what can delay or take back a payment. Once an international wire has arrived, the sender can’t pull it back without your cooperation, while a domestic ACH payment can occasionally be reversed. Platforms run their own dispute processes, and some lean toward the paying client by default. Some also hold or freeze funds on new accounts, or when an account suddenly receives larger amounts than usual. If you need the money secured before you start, escrow is a middle ground.
Registered business requirement. Several platforms assume you operate a registered company. If you don’t, your options narrow. Platforms built to operate without a business registration requirement are specifically useful for independent professionals who work across borders.
Invoicing and documentation capability. Most freelancers don’t prioritize this until tax season arrives. A platform that keeps centralized records and exportable transaction summaries makes tax preparation much simpler. Transfer-focused tools give you statements, and some sync with accounting software, but your invoices and client records usually live somewhere else. Platform records are only there while you can access the account, so export them regularly.
The best payment platforms for freelancers
Ruul
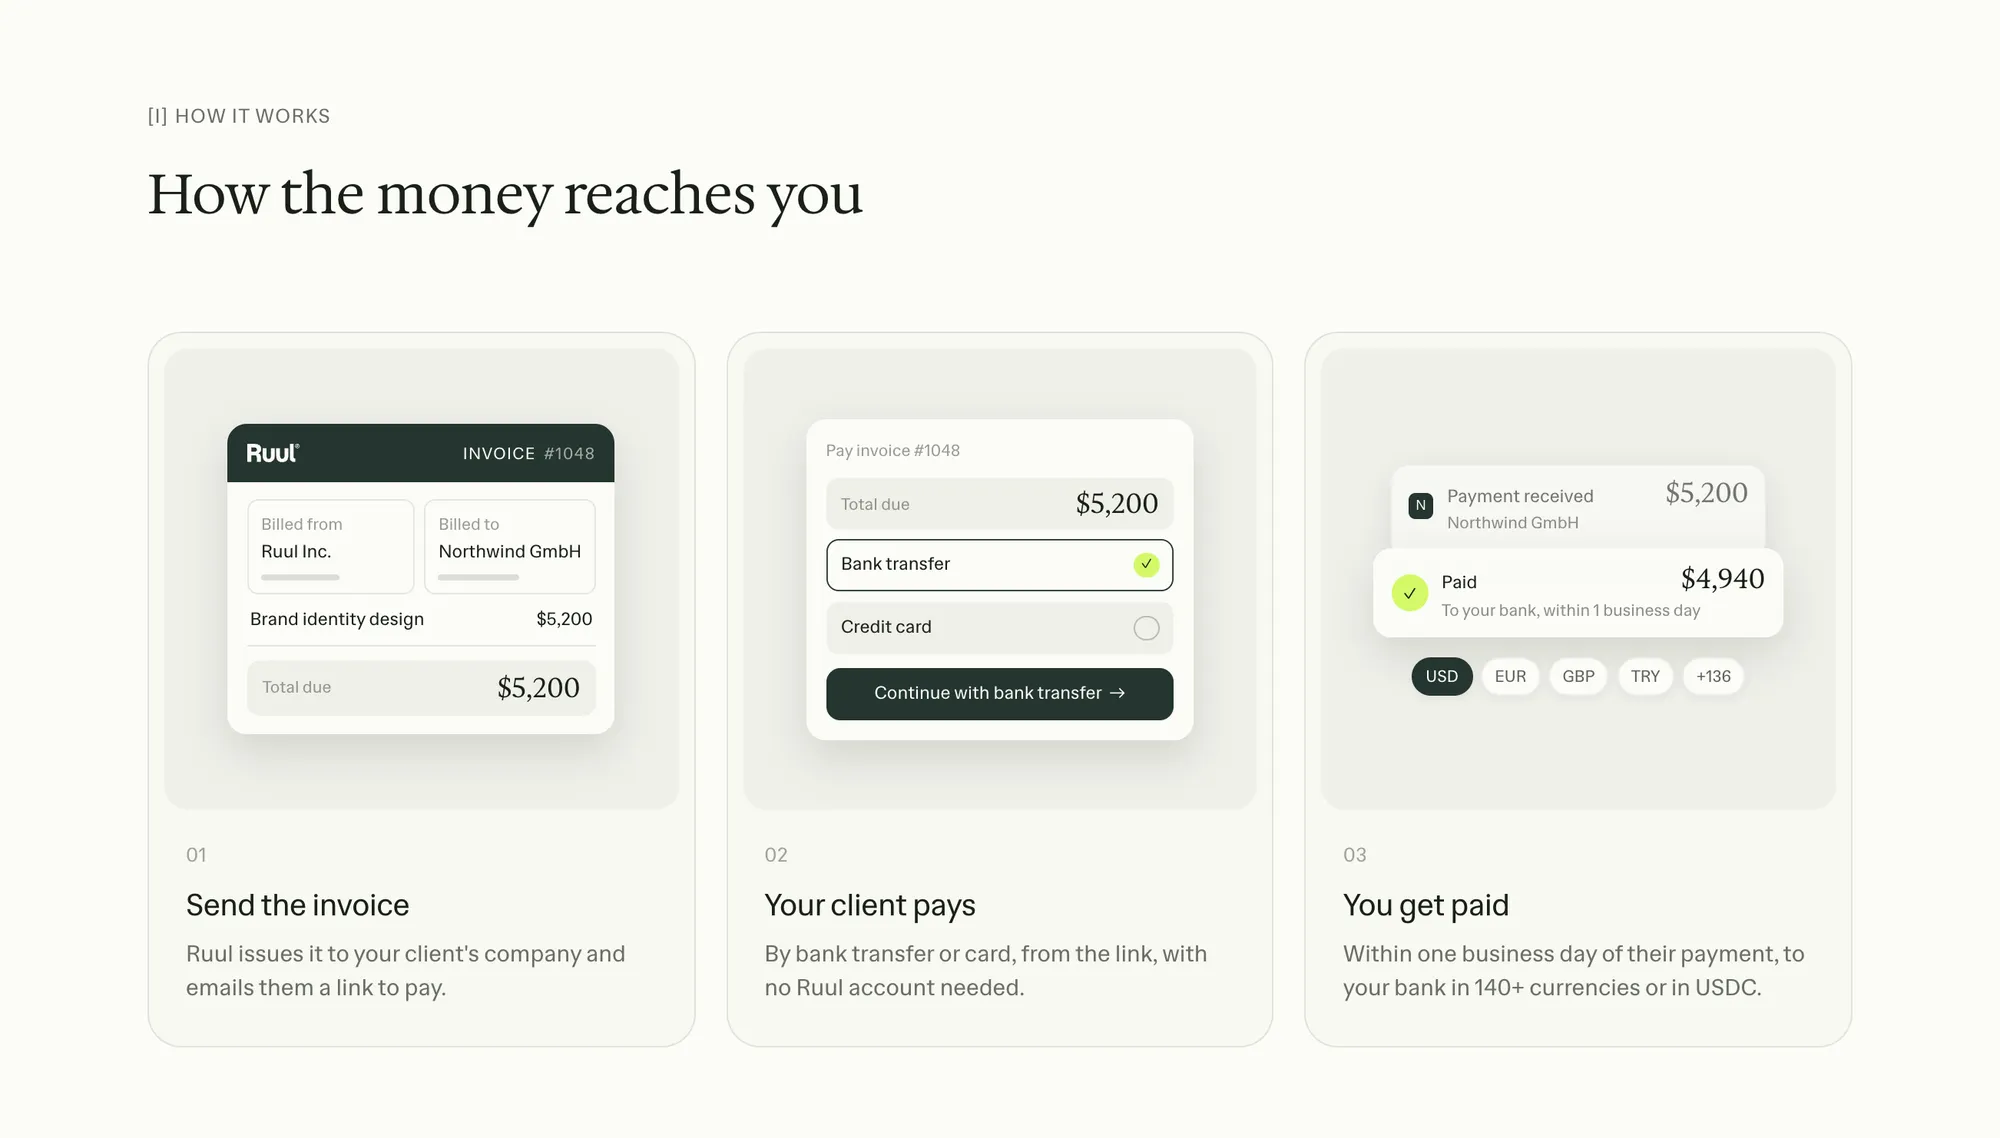
Ruul is an end-to-end payment platform built for freelancers and independent professionals who need to invoice clients in global markets without a registered company. It acts as the legal counterparty: Ruul contracts with you, issues the invoice to your client, collects payment, and deposits funds into your account within 1 business day of client payment. The 5% commission covers the complete flow. There are no setup costs and no monthly fees. You can create single, recurring, or subscription-based invoices directly on the platform, and for ongoing client relationships, subscription invoicing removes the need to manually recreate invoices each cycle. You can get paid in 140+ currencies across 190 countries. Automatic payment reminders follow up on unpaid invoices, so you rarely need to chase a client yourself. Over 240,000 freelancers use Ruul, with $1.18B+ in total transactions processed and a 96.4% satisfaction rate. Teams at the UN, McKinsey, Toyota, Klarna and MIT trust Ruul too. Getting paid is the endpoint, not another task in your workflow.
Best for: Freelancers invoicing international clients without a registered company; anyone who wants one platform to handle the complete payment workflow from invoice creation to getting paid.
Honest limitation: The 5% commission is higher than transfer-only fees on simple domestic transactions where both parties have established banking relationships and no compliance layer is needed.
Wise
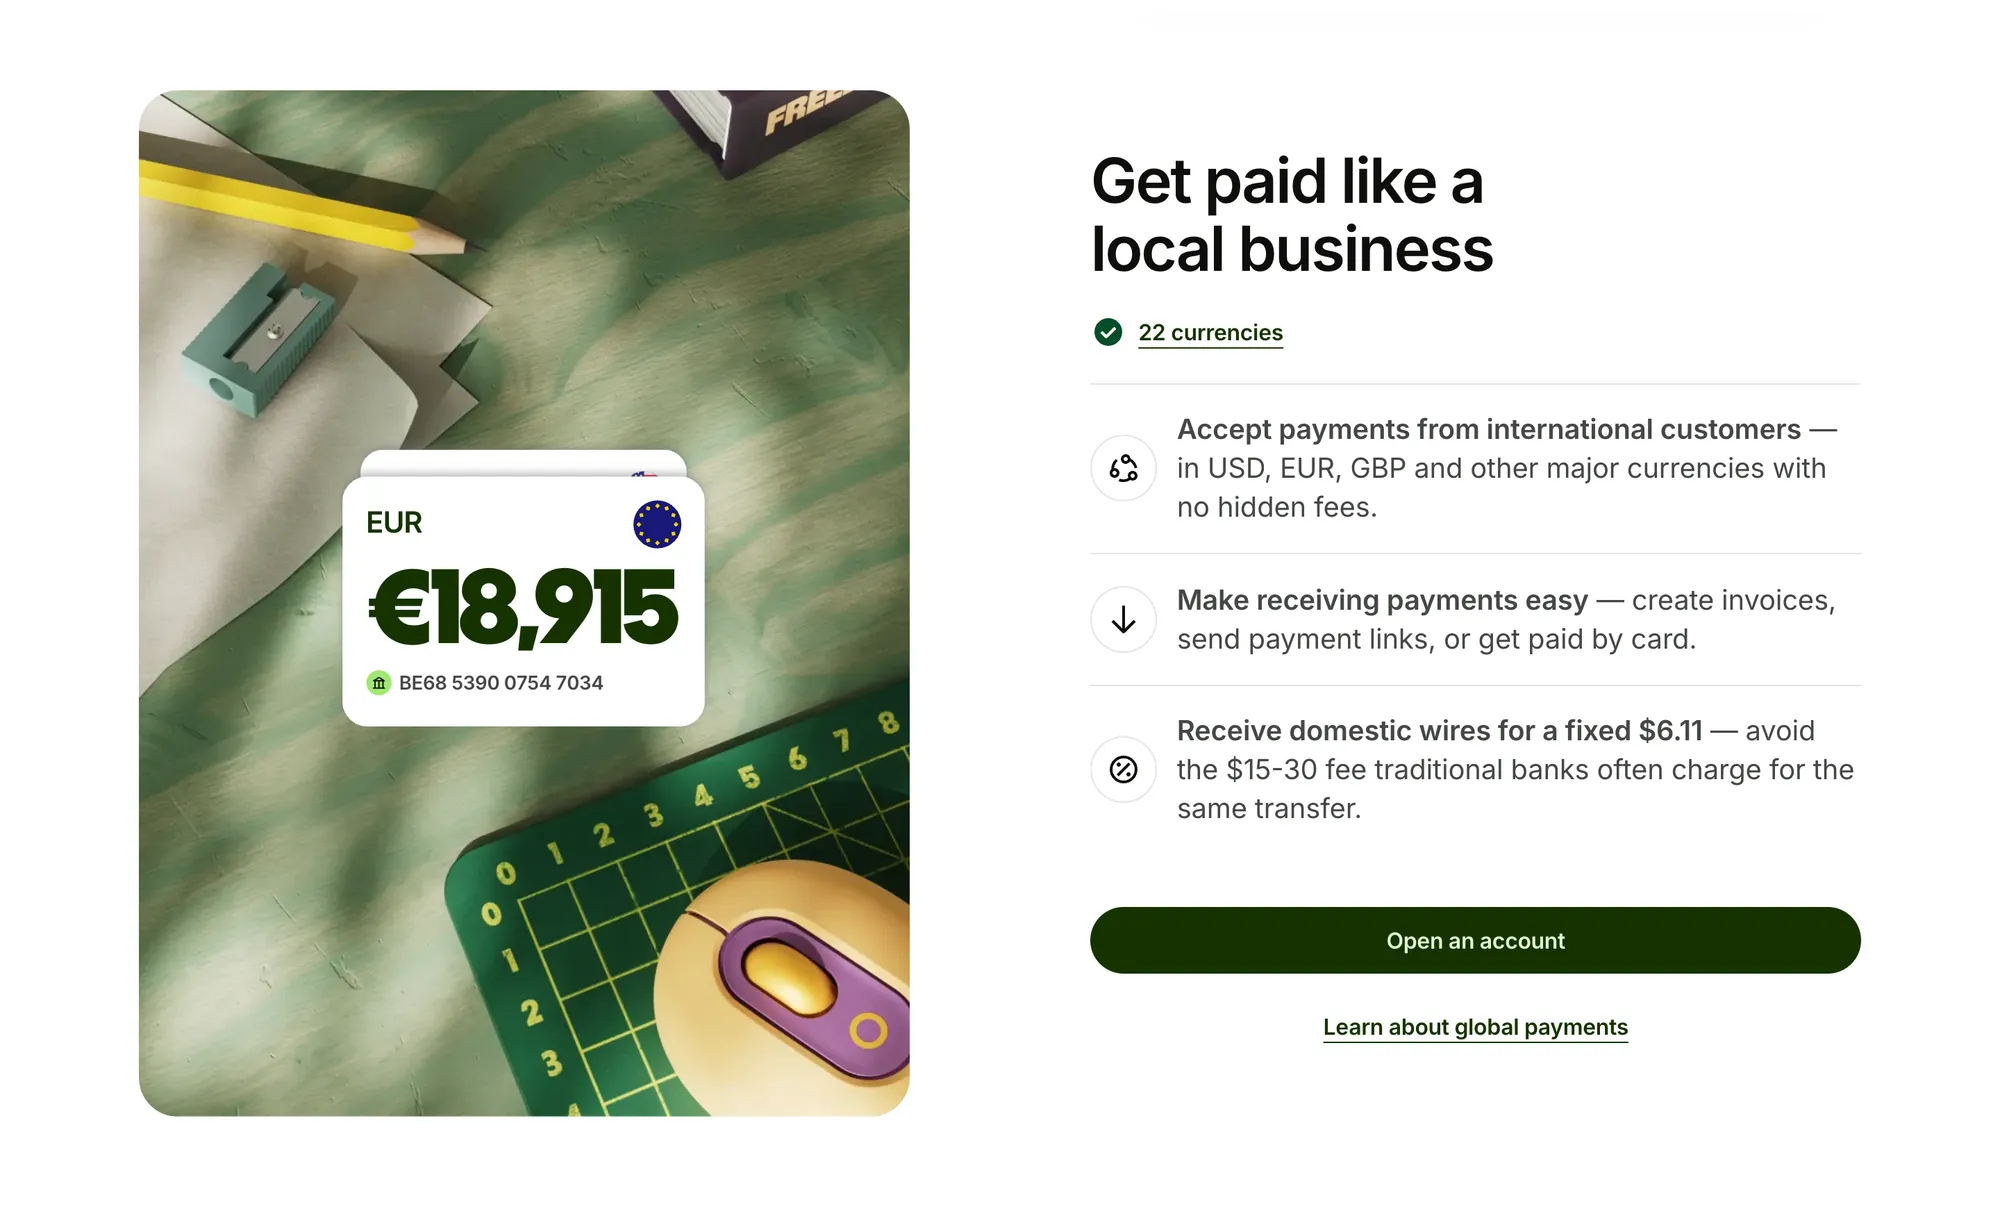
Wise (formerly TransferWise) is a multi-currency account with strong credentials for international transfers. It converts at the mid-market exchange rate with no markup on the exchange itself, and shows a separate fee upfront. Converting a USD balance costs about 0.3% to 0.9% depending on the currency (0.29% to EUR, plus a small fixed fee), and fees drop on large amounts (as of October 2026; verify current details at wise.com/pricing). You can hold and convert 40+ currencies and get account details to receive 22 of them. Local payments in nine currencies, including USD, EUR and GBP, arrive free, while an incoming USD wire costs $6.11. With a Wise Business account, which freelancers and sole traders can open, you can also send invoices and payment links that clients pay by bank transfer or card. What Wise doesn’t do is stand between you and your client: the invoice is in your name, and the compliance side of each cross-border engagement stays with you. For freelancers who already have an invoicing process and need a cost-effective way to receive and convert money, Wise is a strong standalone tool.
Best for: Freelancers with established invoicing processes who need a low-cost way to receive, hold and convert several currencies.
Honest limitation: No legal counterparty role. Invoices go out in your name, invoicing and card payments need a Wise Business account, and the client-side paperwork stays with you.
PayPal
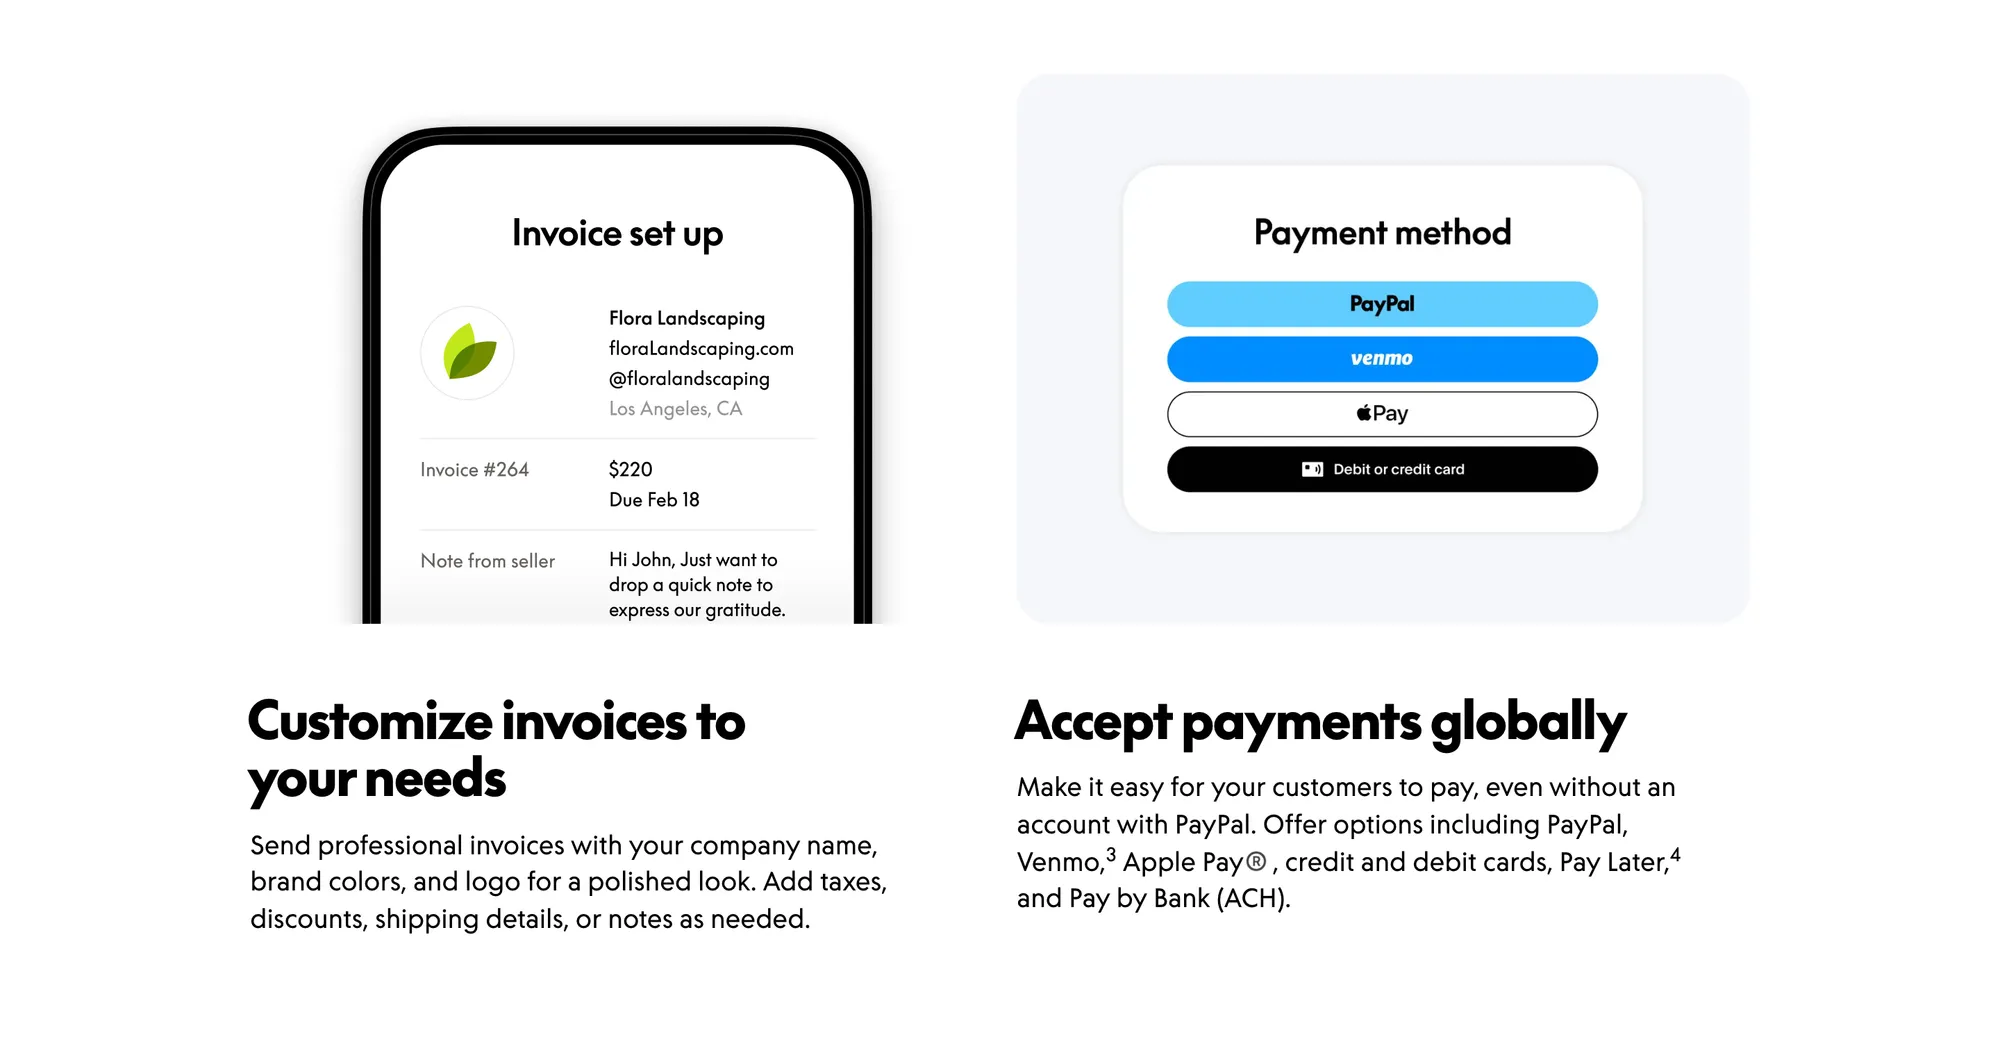
PayPal has genuine advantages for freelancers: it operates in nearly 200 markets, many clients already have an account, and it reduces client friction more than almost any other platform. It supports 25 currencies and includes invoicing tools. Payments hit your PayPal balance quickly. The fee structure, however, is a serious consideration. In the US, a paid invoice costs 3.49% + $0.49 when the client pays with PayPal and 2.99% + $0.49 when they pay by card. International payments add 1.5%, and converting the money adds a 3% spread, so a single international payment can cost you around 7.5% to 8% of the invoice value (as of October 2026; verify current fees at paypal.com). For high-volume international invoicing, those fees compound significantly. PayPal does not act as a legal counterparty. It moves money between accounts, and it can hold a new seller’s first payments for up to 21 days.
Best for: Freelancers working with clients who already use PayPal, particularly for lower-value or consumer-facing transactions.
Honest limitation: High cumulative international fees, a 3% conversion spread, and payment holds make it a poor default for high-volume cross-border invoicing.
Payoneer
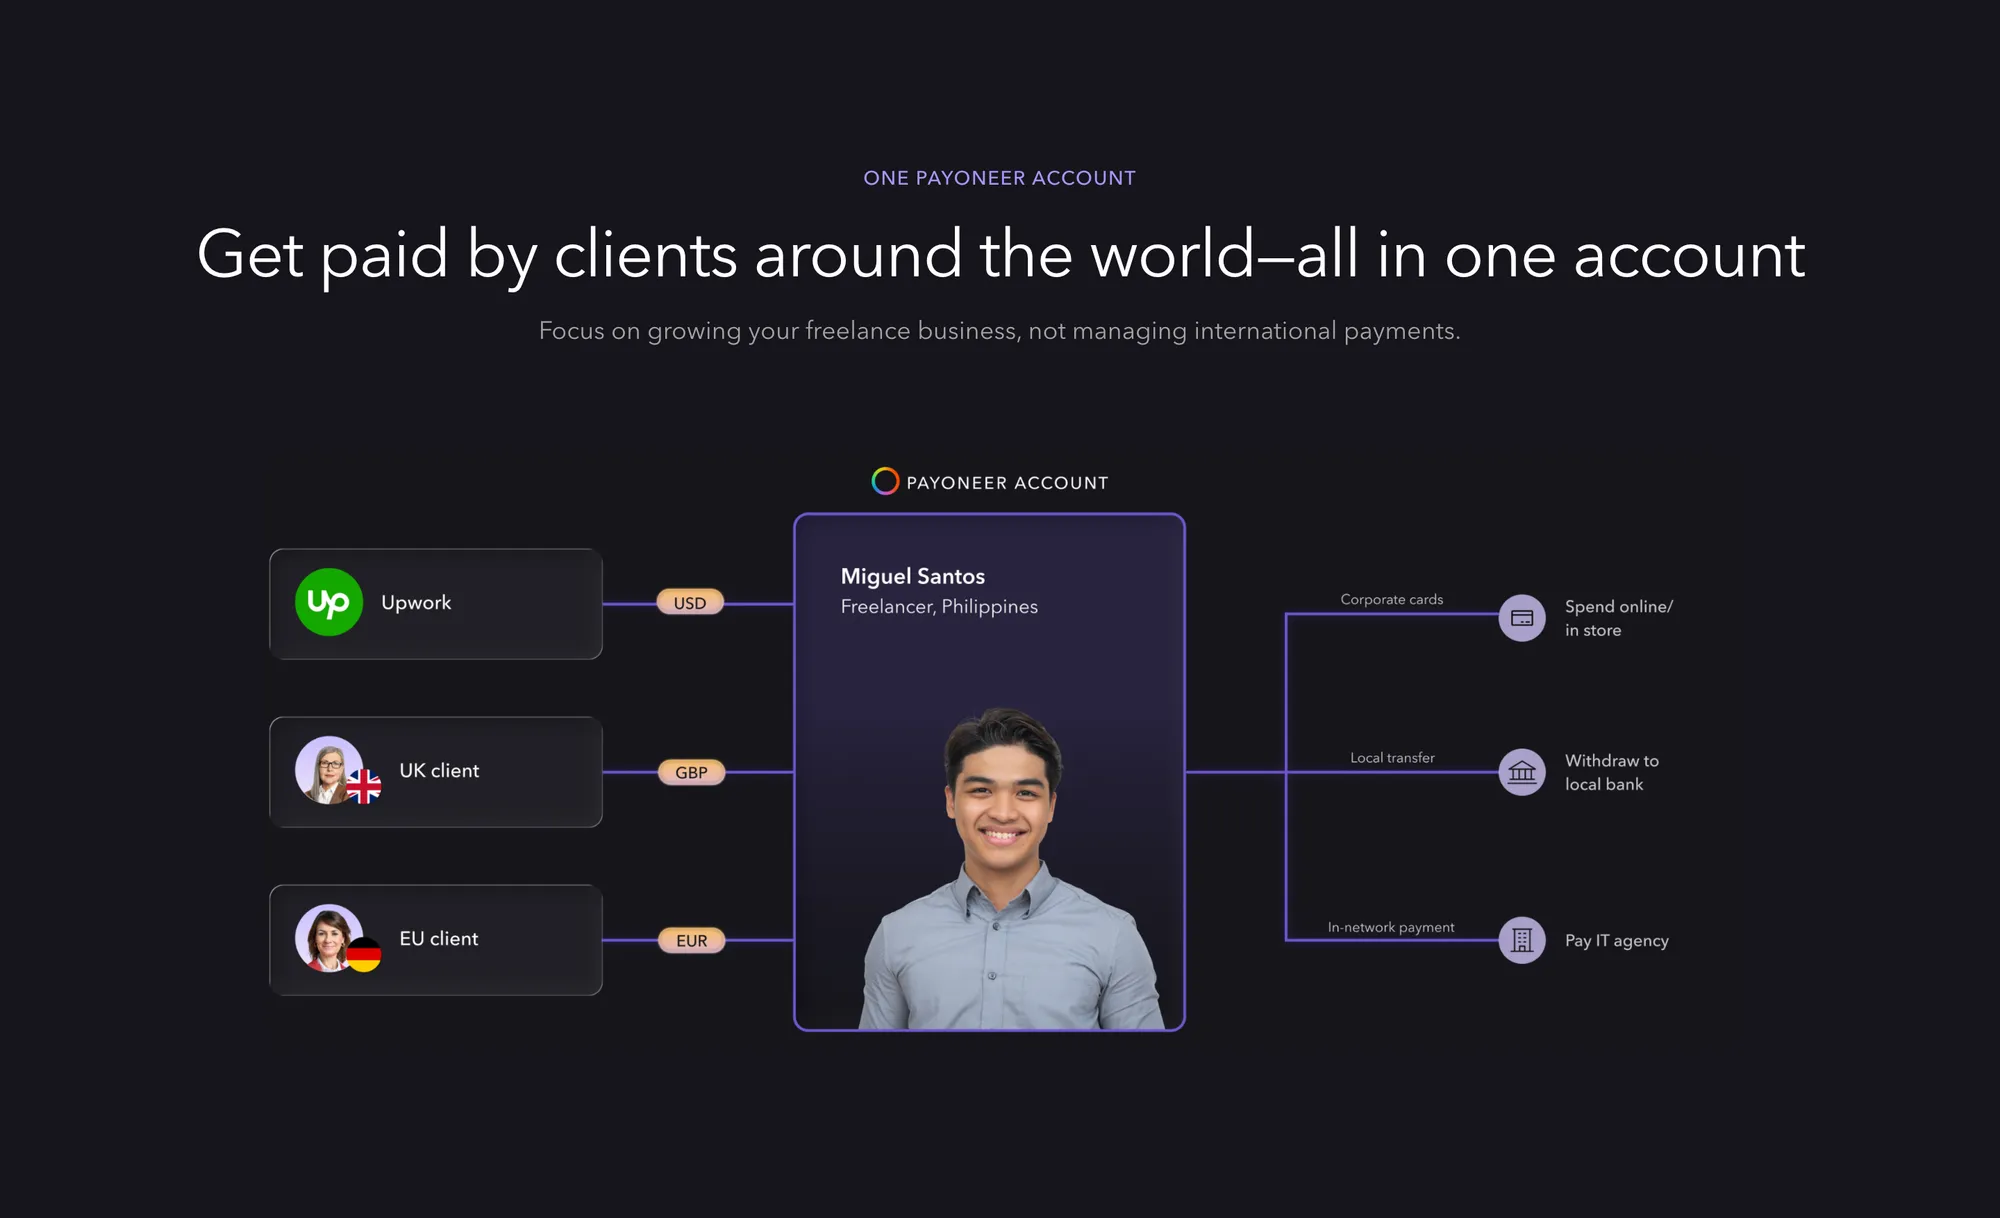
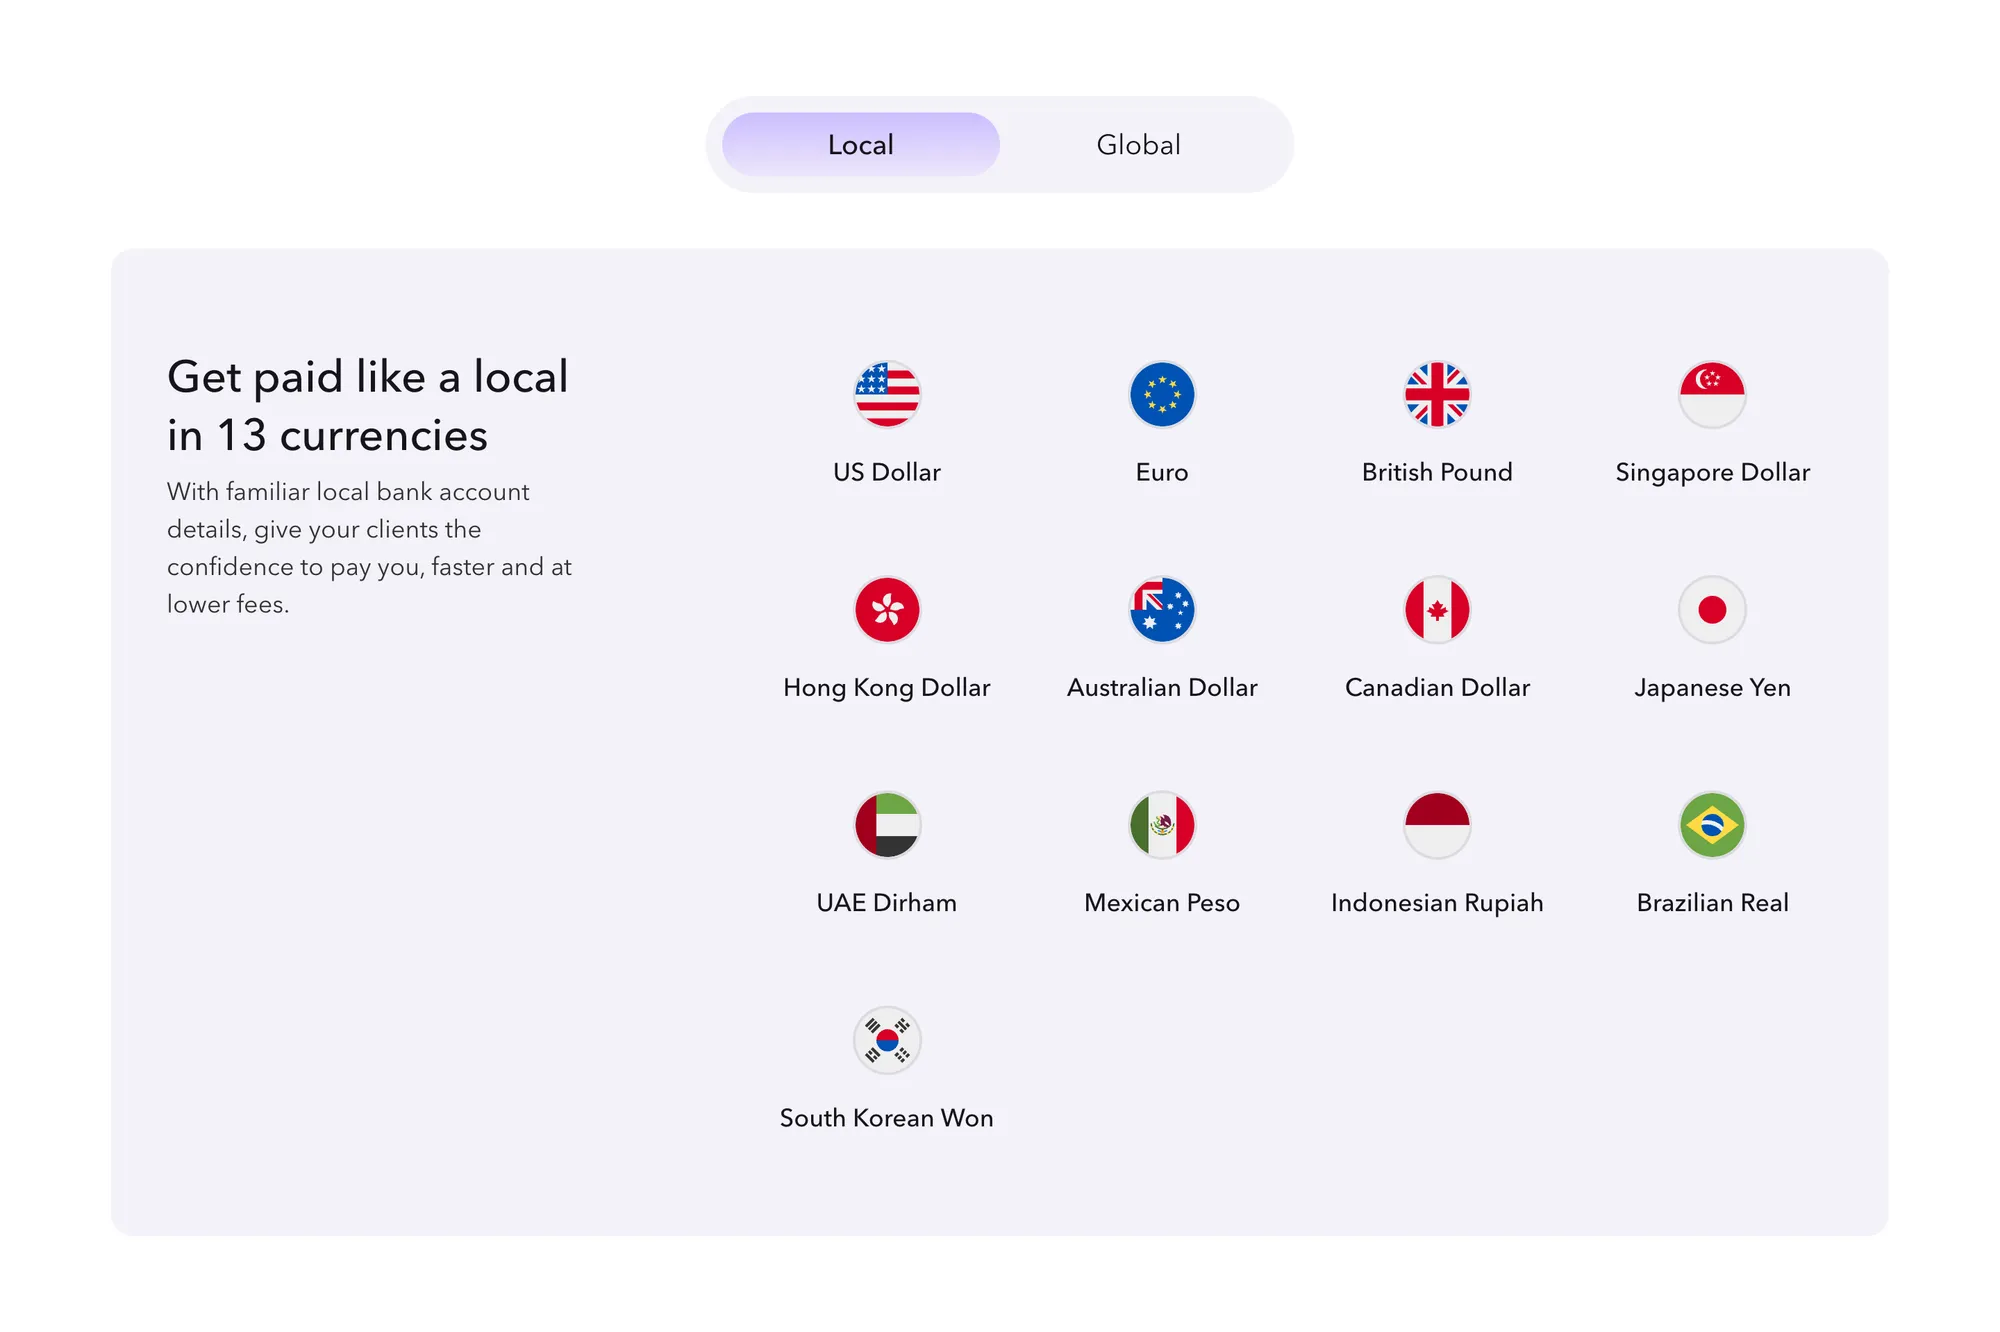
Payoneer is built around global receiving accounts, letting you get paid in 70+ currencies across 190+ countries and territories. You get local receiving account details in 13 currencies, including USD, EUR, GBP, CAD, AUD and JPY, so clients in those markets pay you with a local transfer rather than an international wire (as of October 2026; verify at payoneer.com/pricing). Receiving into an account in your own local currency is free, and in any other currency it costs 1%. Fees on marketplace earnings vary by marketplace. A client paying you by card costs up to 3.99% + $0.49, and by US bank debit 1%. Withdrawing to your bank in a different currency costs 1.2% to 4%, and accounts that receive less than $6,000 in 12 months pay a $29.95 annual fee. Payoneer can also send your invoice with a pay link and remind clients automatically, but it doesn’t act as a legal counterparty on that invoice. Its real strength is deep integration with freelance marketplaces and reach into markets where other platforms have limited presence.
Best for: Freelancers who mainly work through marketplaces like Upwork, Fiverr, or Amazon and want all their marketplace earnings in one account.
Honest limitation: No legal counterparty role; conversion and withdrawal fees of 1.2% to 4% add up on large or frequent transfers; a yearly fee applies to low-volume accounts.
Stripe
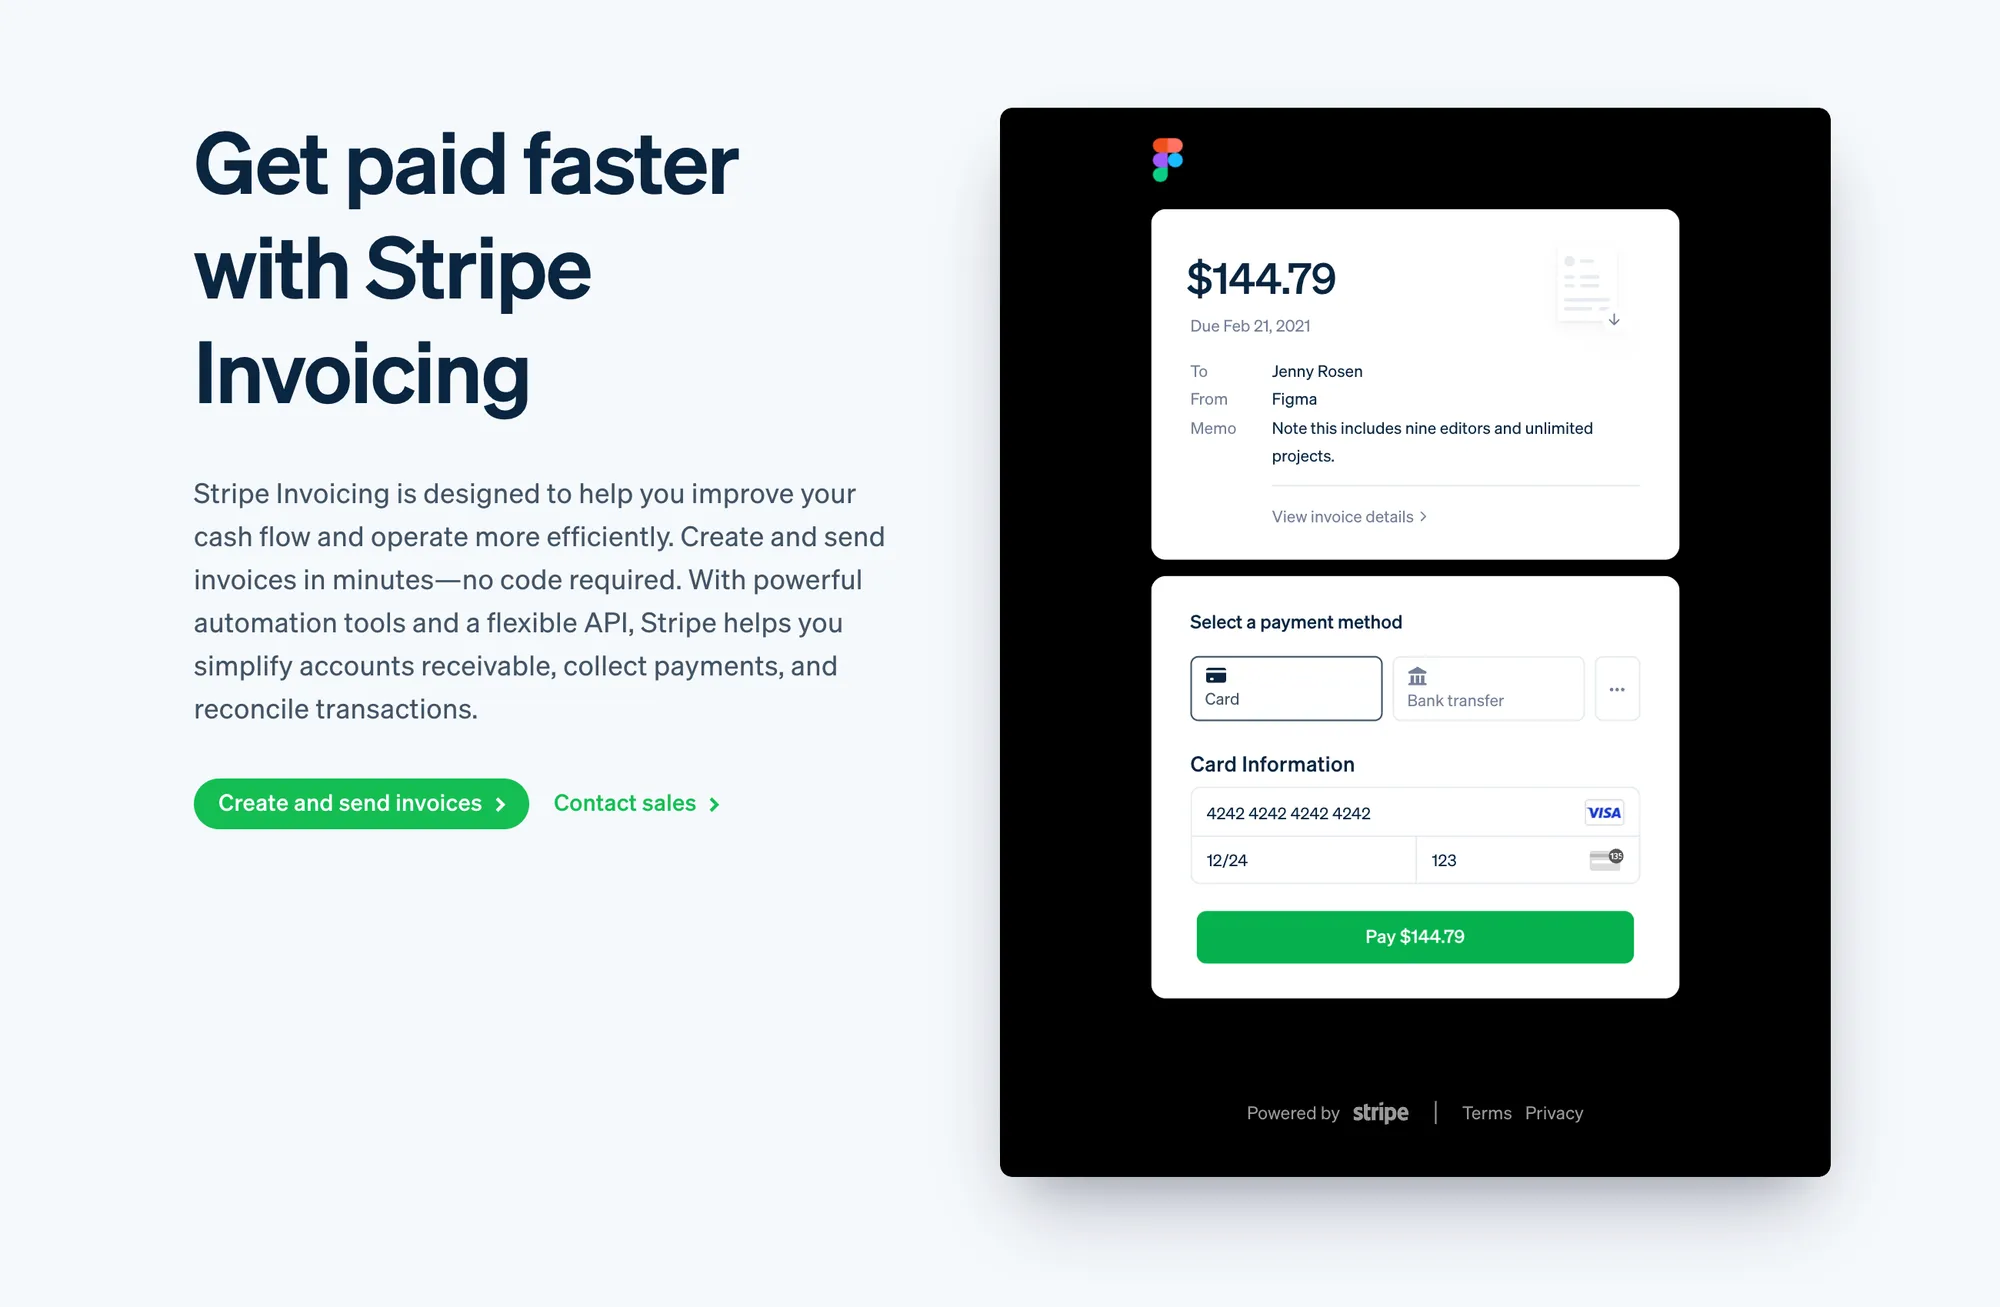
Stripe is a full-service payment processor with strong card acceptance, developer tooling, and support for 135+ currencies and a range of local payment methods. Standard card processing is 2.9% plus $0.30 for domestic cards, plus 1.5% for international cards and 1% if the currency has to be converted; ACH bank debit is 0.8% with a $5 cap (as of October 2026; verify current rates at stripe.com/pricing). Stripe is available to businesses in 51 countries and regions, and in many of them individuals and sole proprietors can sign up with personal identification and tax information rather than a company structure. Payment links are included, and Stripe Invoicing adds 0.4% per paid invoice. The platform is powerful, but that power comes with setup complexity. Configuring Stripe for a freelance invoicing workflow requires more technical fluency than most freelancer-specific tools. For accepting card payments through your own website or a custom checkout flow, Stripe is the professional standard. It does not act as a legal counterparty or handle cross-border compliance independently. Its merchant-of-record option, Managed Payments, is built for digital products and software subscriptions.
Best for: Technically fluent freelancers who need robust card payment acceptance, particularly those offering productized services or selling through a website.
Honest limitation: Higher setup complexity; not built for the freelancer invoicing workflow specifically; no legal counterparty or compliance handling for international engagements.
Direct bank transfer: SWIFT, SEPA, and ACH
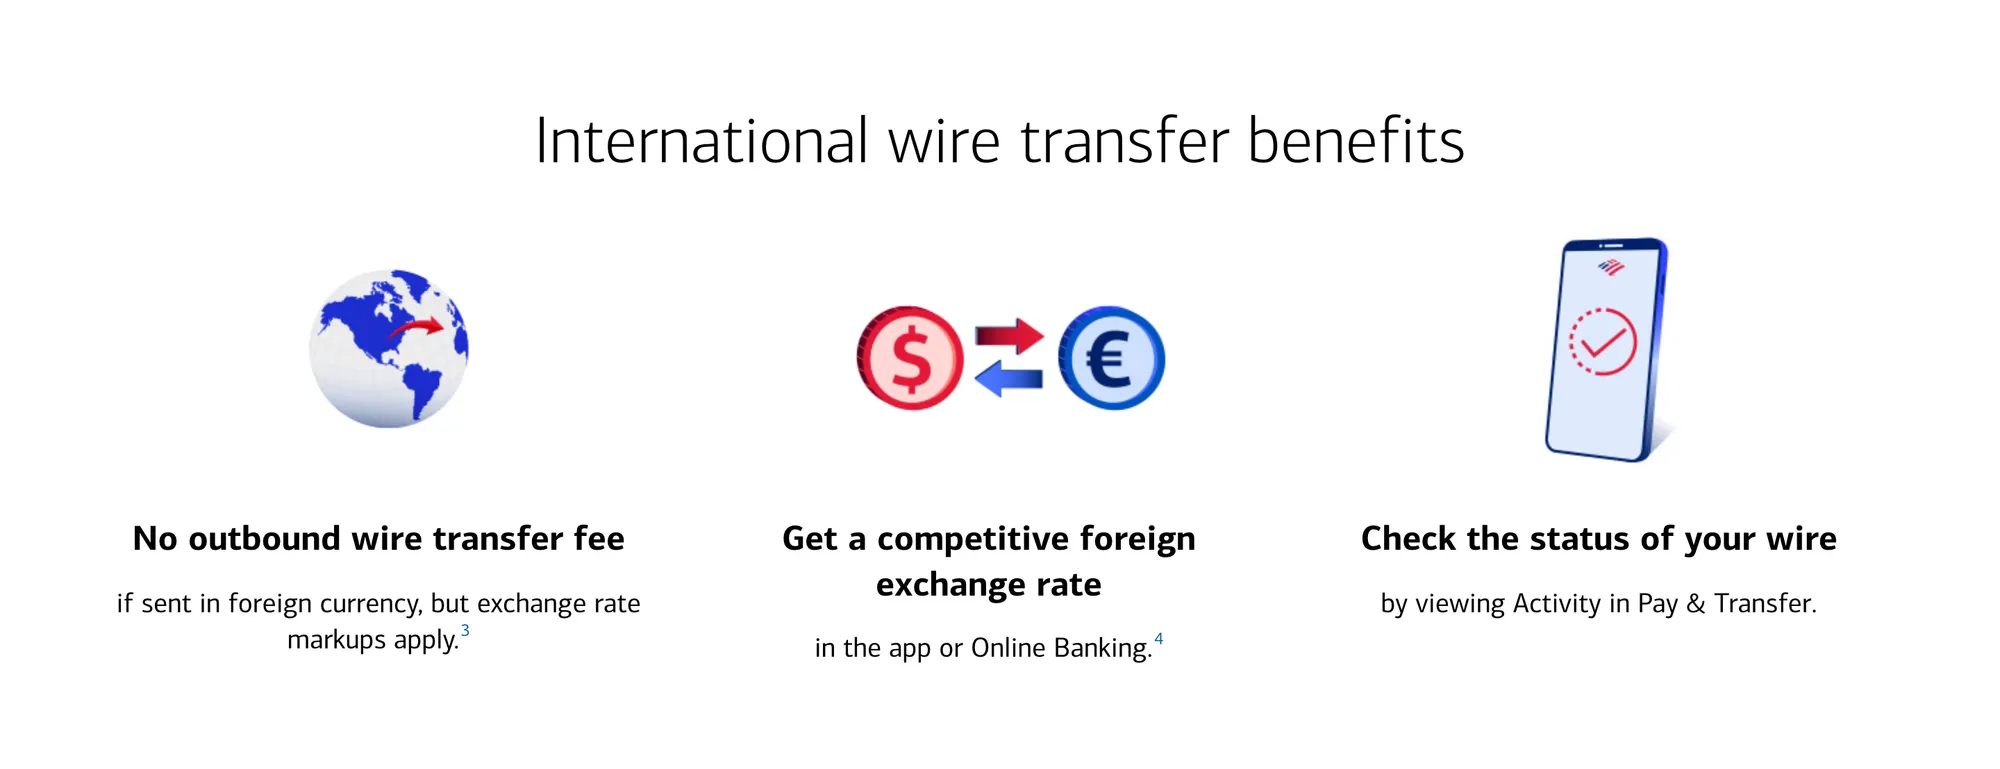
Bank transfers through ACH (domestic US), SEPA (within the EU), or SWIFT (international wires) are the zero-intermediary option. Domestic ACH and SEPA transfers are typically free or very low-cost and remain the standard for established, recurring client relationships. SWIFT international wires are a different calculation entirely. Sending an international wire typically costs $25 to $50 at a US bank (Bank of America charges $45 for a wire in US dollars), and your own bank may charge to receive it ($15 at Bank of America). Intermediary banks in the routing chain can take their own cut, and banks build a markup into the exchange rate when they convert. Together, these can take a noticeable bite out of a $1,000 invoice before it reaches you (actual fees vary by bank and routing). Beyond fees, a direct bank transfer means sharing your full account details with every client: your account and routing numbers in the US, or your IBAN in Europe, plus a SWIFT/BIC code for international wires. There is no invoicing support built in, and no payment tracking or documentation system. The case for bank transfer is strongest for large, recurring payments with trusted long-term clients where both parties have established banking relationships and the currency is consistent. The money lands straight in your account, with no platform balance to withdraw from.
Best for: Large domestic payments, recurring invoices to established clients in the same currency, markets where digital platforms have limited reach.
Honest limitation: Significant fee and markup exposure on international SWIFT transfers; no invoicing, tracking, or compliance support; full banking details shared with each client.
Platform comparison table
The table below applies the key evaluation criteria to each platform reviewed. All fee figures are as of October 2026 and subject to change; verify current details directly with each platform before making decisions.
| Platform | Key Markets | Fee Structure | Transfer Speed to Bank | Registered Business Required | Invoicing Included | Payment Collection Included | Best For |
|---|---|---|---|---|---|---|---|
| Ruul | 190 countries; 140+ currencies | 5% per paid invoice; no setup or monthly fees | 1 business day after client payment | No | Yes: single, recurring, subscription | Yes (card or bank transfer) | End-to-end workflow; invoicing without a company; international clients |
| Wise | Sends to 140+ countries; 40+ currencies; account details in 22 | Free to receive local payments; $6.11 per incoming USD wire; mid-market rate + about 0.3%–0.9% to convert | Most transfers within a day (77% in under 20 seconds) | No (Wise Business accepts freelancers and sole traders) | Yes, with Wise Business | Yes, with Wise Business (payment links; US cards from 2.9% + $0.30) | Low-cost receiving and conversion; multi-currency account management |
| PayPal | Nearly 200 markets; 25 currencies | Invoices: 3.49% + $0.49 (PayPal) or 2.99% + $0.49 (card); +1.5% international; 3% conversion spread | Instant to PayPal balance; 1–3 business days to bank | No | Yes | Yes | Client familiarity; lower-value consumer-adjacent transactions |
| Payoneer | 190+ countries and territories; 70+ currencies | Free in your local currency, 1% in others; card up to 3.99% + $0.49; 1.2%–4% to withdraw with conversion; $29.95 a year under $6,000 received | Typically within 2 business days | No | Yes (invoice with a pay link) | Yes (card, ACH, bank transfer, PayPal) | Consolidating marketplace earnings; multi-currency receiving |
| Stripe | Accounts in 51 countries; 135+ currencies | 2.9% + $0.30 domestic cards, +1.5% international, +1% conversion; 0.8% ACH (capped $5); invoicing +0.4% | First deposit in 7–14 days, then 2–4 business days | No (individuals and sole proprietors in many supported countries) | Yes (0.4% per paid invoice) | Yes (payment links, invoices, checkout) | Card payments; custom checkout; developer-built workflows |
| Direct Bank (SWIFT/SEPA/ACH) | Global (SWIFT); EU (SEPA); US (ACH) | SWIFT: about $25–$50 to send, a fee to receive, intermediary fees and an exchange-rate markup; SEPA/ACH: free or near-free | 1–5 business days | No | No | No | Large domestic payments; established long-term client relationships |
How invoice size changes the cheapest option
Fixed fees weigh most on a small invoice and percentage fees on a large one, so the order of the options shifts with the amount. Here is how the fees in the table above play out when an international client pays you in US dollars and the money is converted into your local currency.
A $500 invoice. A SWIFT wire’s sending, receiving and intermediary fees are fixed amounts, so on a small invoice they take a disproportionate share. If you already have an invoicing process, Wise costs the least, a few dollars, and Payoneer about $11 to $25 with its receiving and withdrawal fees. Ruul’s 5% comes to $25, with invoicing and collection included.
A $1,500 invoice. Once currency conversion is counted, PayPal’s stacked percentages make it the most expensive option by a wide margin. Ruul’s 5% is $75, less than Stripe charges for an international card payment that needs converting.
A $5,000 invoice. Ruul’s 5% is $250. For a large, recurring invoice to a reliable client, with your own invoicing system in place, Wise or a direct bank transfer is cheaper. At this size, what the 5% pays for is the rest of the workflow: Ruul issues the invoice under its own name, collects from your client, can send reminders and pays you within one business day after your client pays.
Choosing the right platform for your situation
The best payment platform is the one that solves your specific problem. Here’s the match.
You invoice international clients and have no registered company. Ruul is the direct answer. Ruul is the legal counterparty on the invoice, so you can invoice clients in 190 countries without a company of your own. You pay 5% per paid invoice, with no setup cost, no monthly fee and no separate currency conversion fee.
You have an established invoicing process and need a cheaper international transfer layer. Wise handles multi-currency receiving and transfer efficiently at lower fees than PayPal or SWIFT wire. It doesn’t replace your invoicing process; it improves the transfer step.
Your clients are already on PayPal and you work in consumer-facing markets. PayPal works for occasional low-to-mid-value transactions where the client familiarity advantage outweighs the fee cost. It’s not optimal for high-volume international invoicing.
You primarily withdraw from Upwork, Fiverr, or other marketplaces. Payoneer’s direct marketplace integrations make it the most friction-free option for consolidating those earnings into a single account.
You need card payment acceptance on your own website or through a custom checkout flow. Stripe is purpose-built for this. Set aside time for proper configuration; the setup is not instant.
You invoice one or two large domestic clients on a recurring basis. Direct bank transfer or ACH works well when the relationship is established, the currency is consistent, and you manage invoicing through separate software.
You run ongoing retainer arrangements and want invoices to go out automatically. Ruul’s subscription invoicing charges your client’s card on the schedule you set, creates each invoice for you and tracks whether it has been paid.
Most freelancers use more than one platform
Single-platform setups are rare in practice. A typical freelancer might receive most direct client payments through Ruul, withdraw marketplace earnings through Payoneer, and use Wise for specific cross-currency transfers. That’s not inefficiency. It’s responding rationally to different client preferences and payment types.
The complexity cost of running multiple platforms is real but manageable when each platform serves a specific, defined role. The problem arises when platforms accumulate reactively, without clarity on what each one handles. The result is duplicated fees, scattered documentation, and a confusing picture at year-end when you need to reconcile income across accounts.
The cleaner approach: identify your primary payment flow and build from there. For most freelancers doing cross-border work, that means one end-to-end platform as the foundation, supplemented by transfer tools for specific client preferences. Keep your bank details ready for domestic and large payments, and list the payment options you accept on each invoice, so a client never has to ask how to pay you. Centralizing your documentation, or exporting records consistently across platforms, makes tax preparation far more manageable when the time comes.
Most payment platforms move money. Ruul also issues the invoice, collects from your client and pays you, in 190 countries, without a registered company. See how getting paid works on Ruul or create your account at app.ruul.io/register.
FAQs
Which payment platform is best if I’m just starting out?
PayPal or Ruul. PayPal needs nothing more than an account. Ruul is just as quick to start and handles the whole flow, invoice included, so you don’t need a separate invoicing tool. If you have no registered company and want professional invoices from day one, Ruul is the cleaner option.
Is a bank transfer cheaper than an online payment platform?
It depends on where your client is and how large the invoice is. From a client in your own country, a bank transfer usually wins on large invoices: ACH and SEPA transfers cost little or nothing, while a 3% platform fee on a $5,000 invoice is $150. From a client abroad, a platform often wins on smaller invoices, because a wire’s sending, receiving and intermediary fees are fixed amounts that take a large share of a small payment.
How do I get paid by enterprise clients that only pay by bank transfer?
Many corporate finance teams pay by bank transfer as a matter of policy, because it fits their accounts payable process. Share your bank details, or receive the money into Wise if you need to convert it afterward, which keeps the conversion cheap. If you invoice through Ruul, the client can still pay that invoice by bank transfer, without a Ruul account.
Which payment platform works if my country has limited banking options?
Ruul is specifically useful in that case. You can get paid in 190 countries, including Turkey, Pakistan and Bangladesh, where neither Stripe nor PayPal is available.
When is it worth adding another payment platform?
When it covers something your current setup doesn’t, such as a client who will only pay through PayPal or marketplace earnings that arrive through Payoneer. If it adds nothing new, the added complexity isn’t worth it.
Written by · Co-founder