Contractor compliance (DAC7)
Learn what DAC7 may mean for platforms and businesses working with contractors, including reporting and documentation basics.
Summary
DAC7 is about tax reporting, not worker classification. Platforms report seller income to EU tax authorities by January 31, from the first euro for services. A business hiring contractors through a platform owes no DAC7 report.
On this page
- What DAC7 is
- Who DAC7 applies to
- Which sellers are affected
- What data must be reported
- When and how to report
- Country-level nuances
- Which businesses are not reporting platform operators
- DAC7 and the Contractor of Record model
- Due diligence and onboarding
- Data protection and GDPR interaction
- Penalties for non-compliance
- Practical steps for platform operators
- Conclusion
- FAQs
Important disclaimer: This article is for informational purposes only. It does not constitute legal or tax advice. DAC7 obligations vary by EU member state, and implementation details continue to evolve. Consult qualified EU tax counsel before making compliance decisions. Ruul does not provide tax advice; Ruul provides invoicing and payment infrastructure, including its own compliance processes where required.
The EU’s DAC7 directive is not about workers. It is not about whether your contractors are employees. It has nothing to do with worker classification.
DAC7 is about tax transparency. Specifically, it requires digital platforms to report the income their sellers earn, freelancers and contractors included, to the tax authority of an EU member state. That authority passes each seller’s data on to the member state where the seller lives. The goal is to close the gap between income earned through platforms and income declared to tax offices.
If your business operates a digital platform that connects sellers to buyers, this directive affects how you collect data, how you verify it, and what you file every January. If your business simply uses platforms to source contractors, the reporting obligation sits with the platform, not with you.
Understanding that distinction is the starting point for everything that follows.
What DAC7 is
DAC7 is the informal name for Council Directive (EU) 2021/514, which amended the EU’s Directive on Administrative Cooperation (DAC). The original 2011 directive counts as DAC1, and each major amendment since has taken the next number, which is why this one carries the “DAC7” label.
Its rules have applied since 1 January 2023. The first reporting cycle covered calendar year 2023, with reports due to tax authorities by 31 January 2024 and the first exchange of information between member states taking place at the end of February 2024, as confirmed by the European Commission’s Taxation and Customs Union directorate.
The directive does not introduce new taxes. It does not change how income is taxed. It creates a reporting infrastructure that makes existing tax rules enforceable in the digital economy. Income earned on platforms was always taxable. DAC7 ensures tax authorities can actually see it.
Do not confuse DAC7 with the EU Platform Work Directive, which addresses worker classification and employment status. Those are separate instruments with separate scopes. DAC7 is solely about tax reporting by platforms.
Who DAC7 applies to
The reporting obligation under DAC7 falls on “Reporting Platform Operators.” The directive defines these as entities that contract with sellers and make a digital platform available to facilitate the performance of Relevant Activities.
Both EU-based and non-EU-based platforms fall within scope if they have EU-resident sellers or facilitate the rental of EU property. An EU platform reports to its home member state. A non-EU platform must register in a single chosen member state and report there. The EU then distributes the data across member states automatically. A platform with ties to more than one member state chooses one of them to report in. A non-EU platform based in a country whose rules the EU has found equivalent, so far the UK, Canada and New Zealand, can be partly or fully relieved of EU reporting once the relevant exchanges are active.
The Relevant Activities covered by DAC7 are:
- Rental of immovable property, including residential, commercial, and parking spaces
- Personal services, meaning time or task-based work carried out at the request of a user
- Sale of goods
- Rental of any mode of transport
The personal services category is the one most relevant to businesses engaging contractors and freelancers. Platforms like Upwork and Fiverr fall squarely within it. So does any marketplace that connects businesses to independent workers and facilitates those transactions.
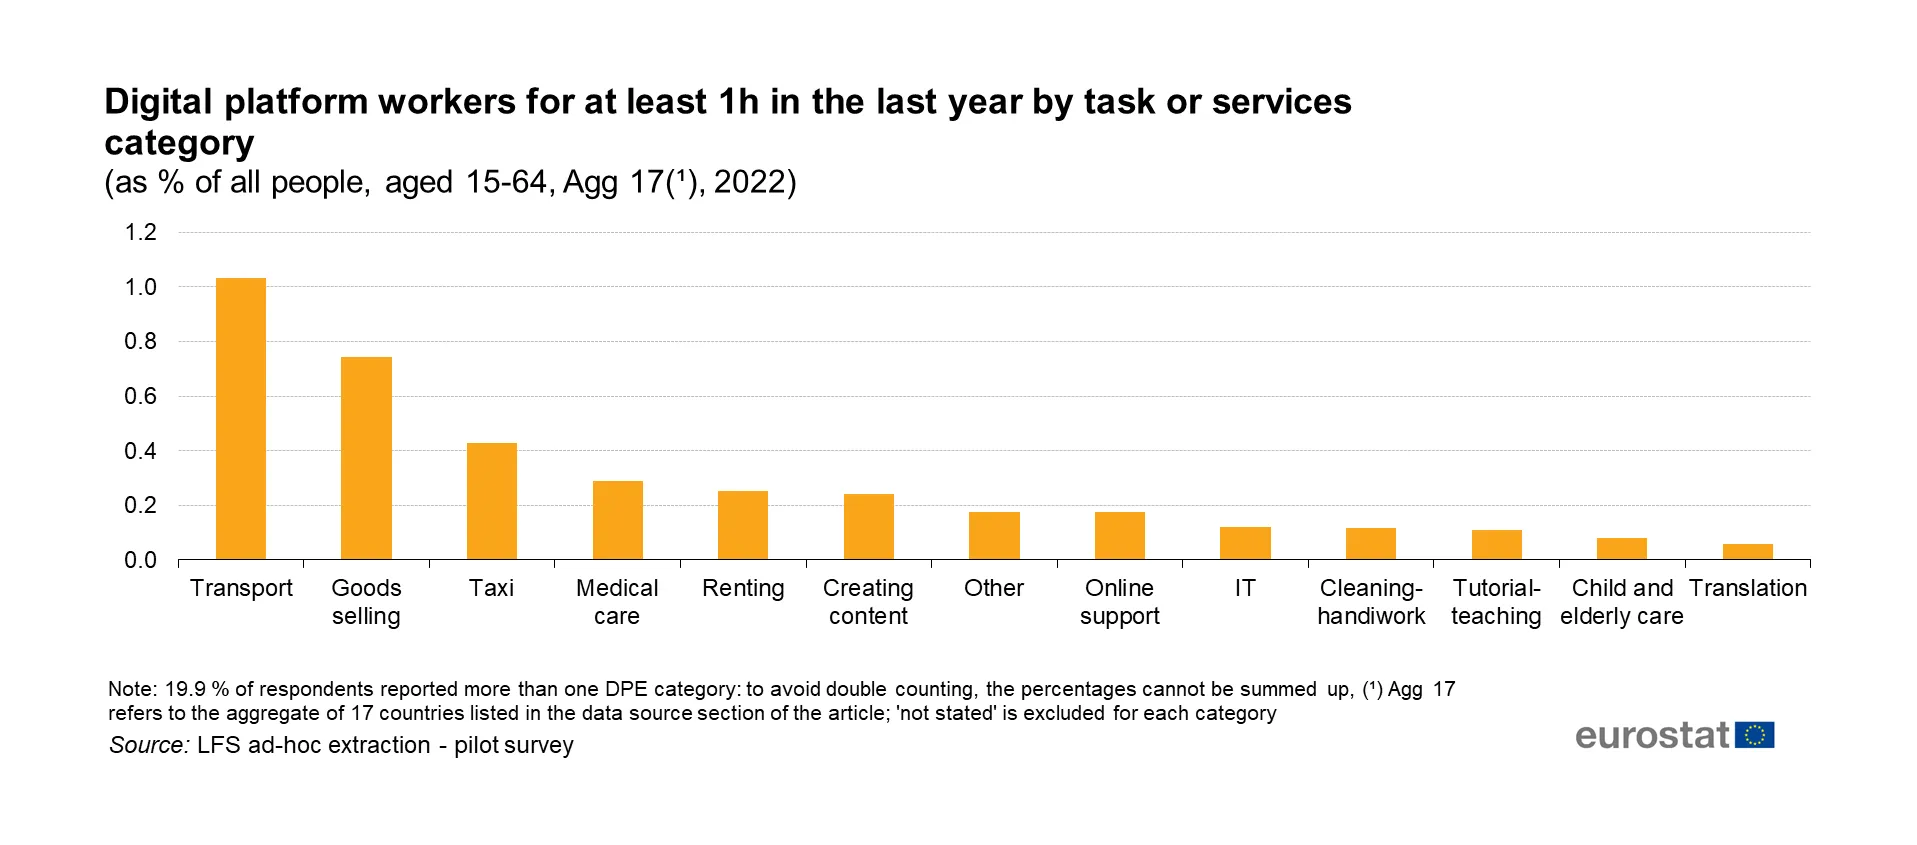
Importantly, for personal services there is no minimum earnings threshold. A single transaction triggers full DAC7 reporting obligations for the platform. The €2,000 / 30-transaction threshold that does exist applies only to sellers of goods, not to personal services providers. A freelancer earning €50 through a platform is reportable.
Some software falls outside the definition of a platform altogether. Payment processors (such as Stripe, PayPal, or Adyen) that only move money, with no further part in the underlying transaction, are outside scope, though they remain subject to PSD2’s payment-processing rules. So is software that only lists or advertises services, or only sends users on to another platform.
Which sellers are affected
DAC7 covers individual contractors and incorporated service providers transacting through platforms. The personal services category includes freelance developers, designers, writers, consultants, coaches, tutors, and anyone performing time or task-based work through an online marketplace. Drivers and couriers using gig economy platforms are also in scope.
DAC7 additionally covers sellers of goods via marketplaces and property hosts renting EU-located immovable property, even if the host is not EU tax resident.
The €2,000 / 30-sale exemption applies only to goods sellers. There is no de minimis threshold for personal services: freelance work is reportable from the first euro. Contractors must give platforms their TIN, or their place of birth if they have none. If a seller still hasn’t provided the information after two reminders and at least 60 days, the platform must close the account and stop the seller from registering again, or withhold the seller’s payments until the information arrives.
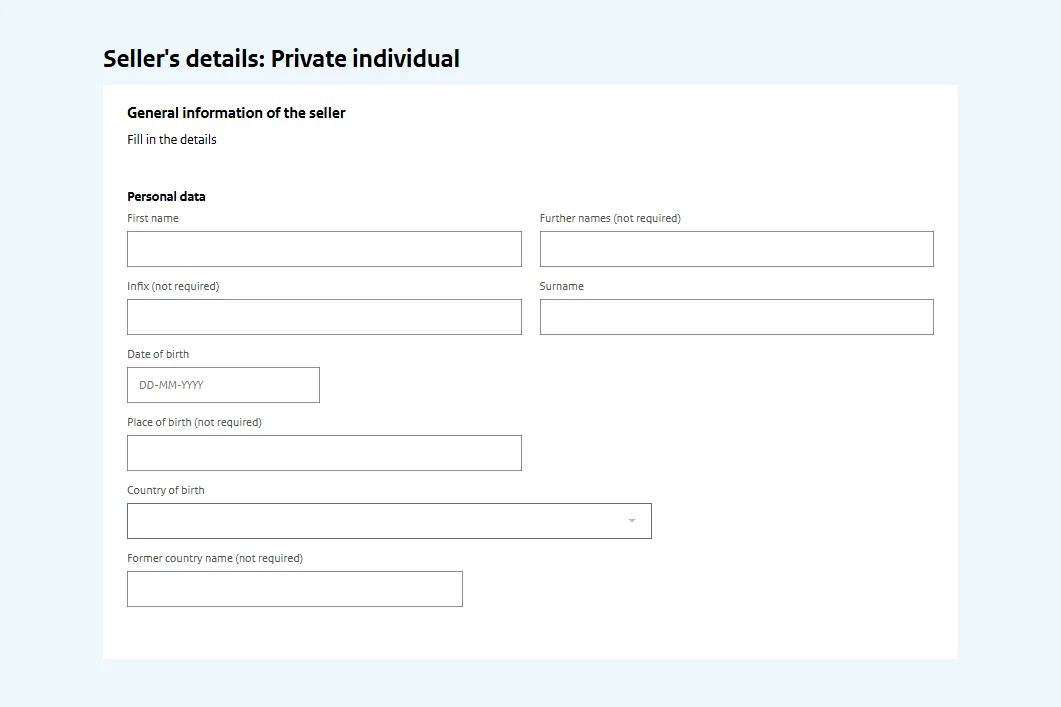
Some sellers are excluded entirely: government entities, companies whose shares are regularly traded on a stock exchange and their related entities, and entities that rent out the same property listing more than 2,000 times a year through the platform.
What data must be reported
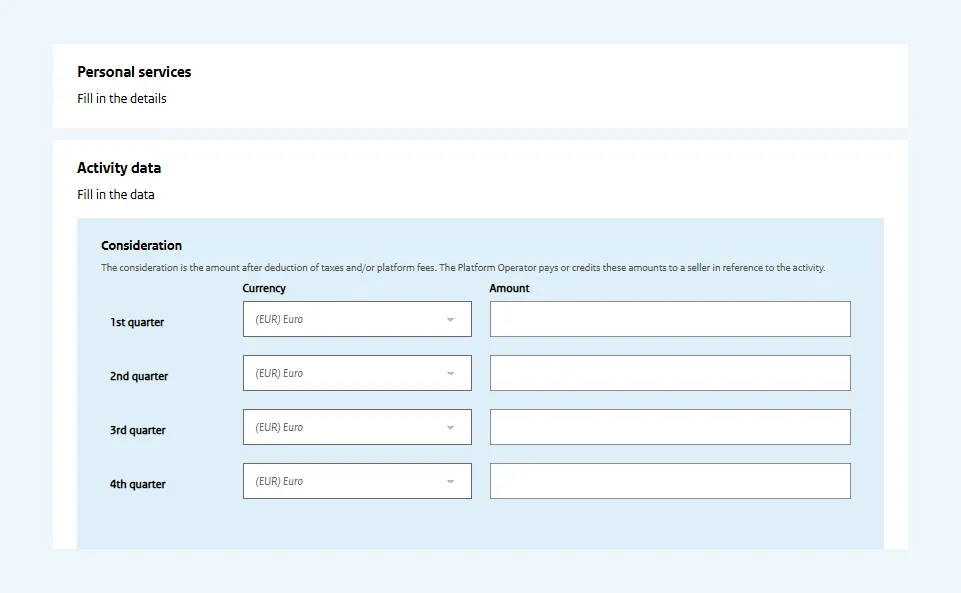
For each reportable seller, the platform must collect, verify, and report the following:
| Data point | Details |
|---|---|
| Name and primary address | Full name for individuals, legal name and registered office for entities |
| Date of birth | For individuals |
| Member state of residence | Determines which tax authority receives the data |
| Tax Identification Number (TIN) | With each member state that issued it, or, for an individual without one, their place of birth |
| VAT identification number | Where available, for individuals and entities |
| Business registration number | For entities |
| Financial account identifier | The bank or payment account that receives the money, where available, plus the account holder’s name if it differs from the seller’s |
| Consideration paid or credited | Per quarter, net of the platform’s fees, commissions and taxes |
| Number of activities | Per quarter |
| Fees, commissions, or taxes | Withheld or charged by the platform, per quarter |
For rental of immovable property, the report also includes the full property address, land registration or cadastral number, and number of rental days.
Platforms cannot simply take sellers at their word. The directive requires them to check that the information is reliable, using everything in their own records and any free electronic tools that a member state or the EU provides. For VAT numbers, the EU’s VIES system serves that purpose. A platform can hire a third-party provider to run these checks, but the responsibility stays with the platform.
Sellers must be told that their information will be collected and passed to tax authorities before it is reported. By 31 January, the same deadline as the report itself, the platform must also give each reportable seller the information it reported about them.
Records must be kept for at least five and at most ten years after the end of the reporting year, depending on the member state (Ireland, for example, requires six). Keeping those records organised and exportable from day one is not optional housekeeping: it is a compliance requirement. If you pay contractors through Ruul, each payment keeps its invoice, receipts and supporting files, ready to export for reconciliation.
When and how to report
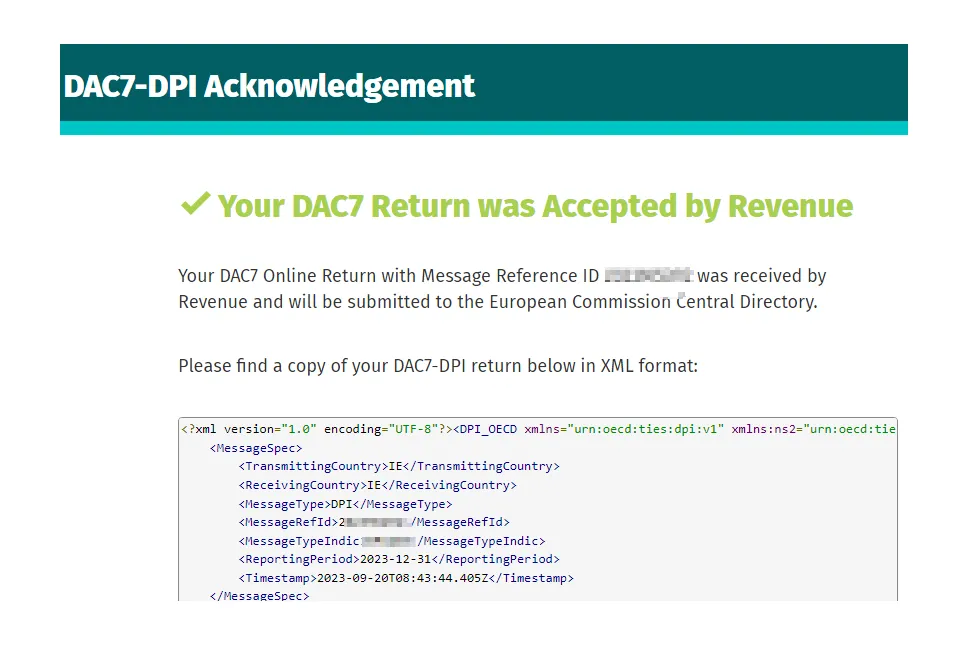
The annual reporting cycle works as follows:
- Due diligence deadline: 31 December of the calendar year being reported
- Reporting deadline: 31 January of the following year
So, data on seller activity during 2026 must be verified by 31 December 2026 and reported by 31 January 2027.
Reports are filed electronically with the tax authority of the member state where the platform is registered or has chosen to register for DAC7 purposes. The submission format uses a standardised XML schema. Once filed, that member state shares the data automatically with all other member states where reported sellers are tax resident.
Non-EU platforms must register in a single EU member state when they start facilitating activity involving EU-resident sellers or property located in the EU. The one-stop-shop structure means a platform does not need to register and file separately in every EU country.
If a seller still hasn’t provided the required information after two reminders and at least 60 days, the platform must close the seller’s account and stop them from registering again, or withhold their payments until the information is supplied. This is not optional: it is a prescribed action under the directive.
Country-level nuances
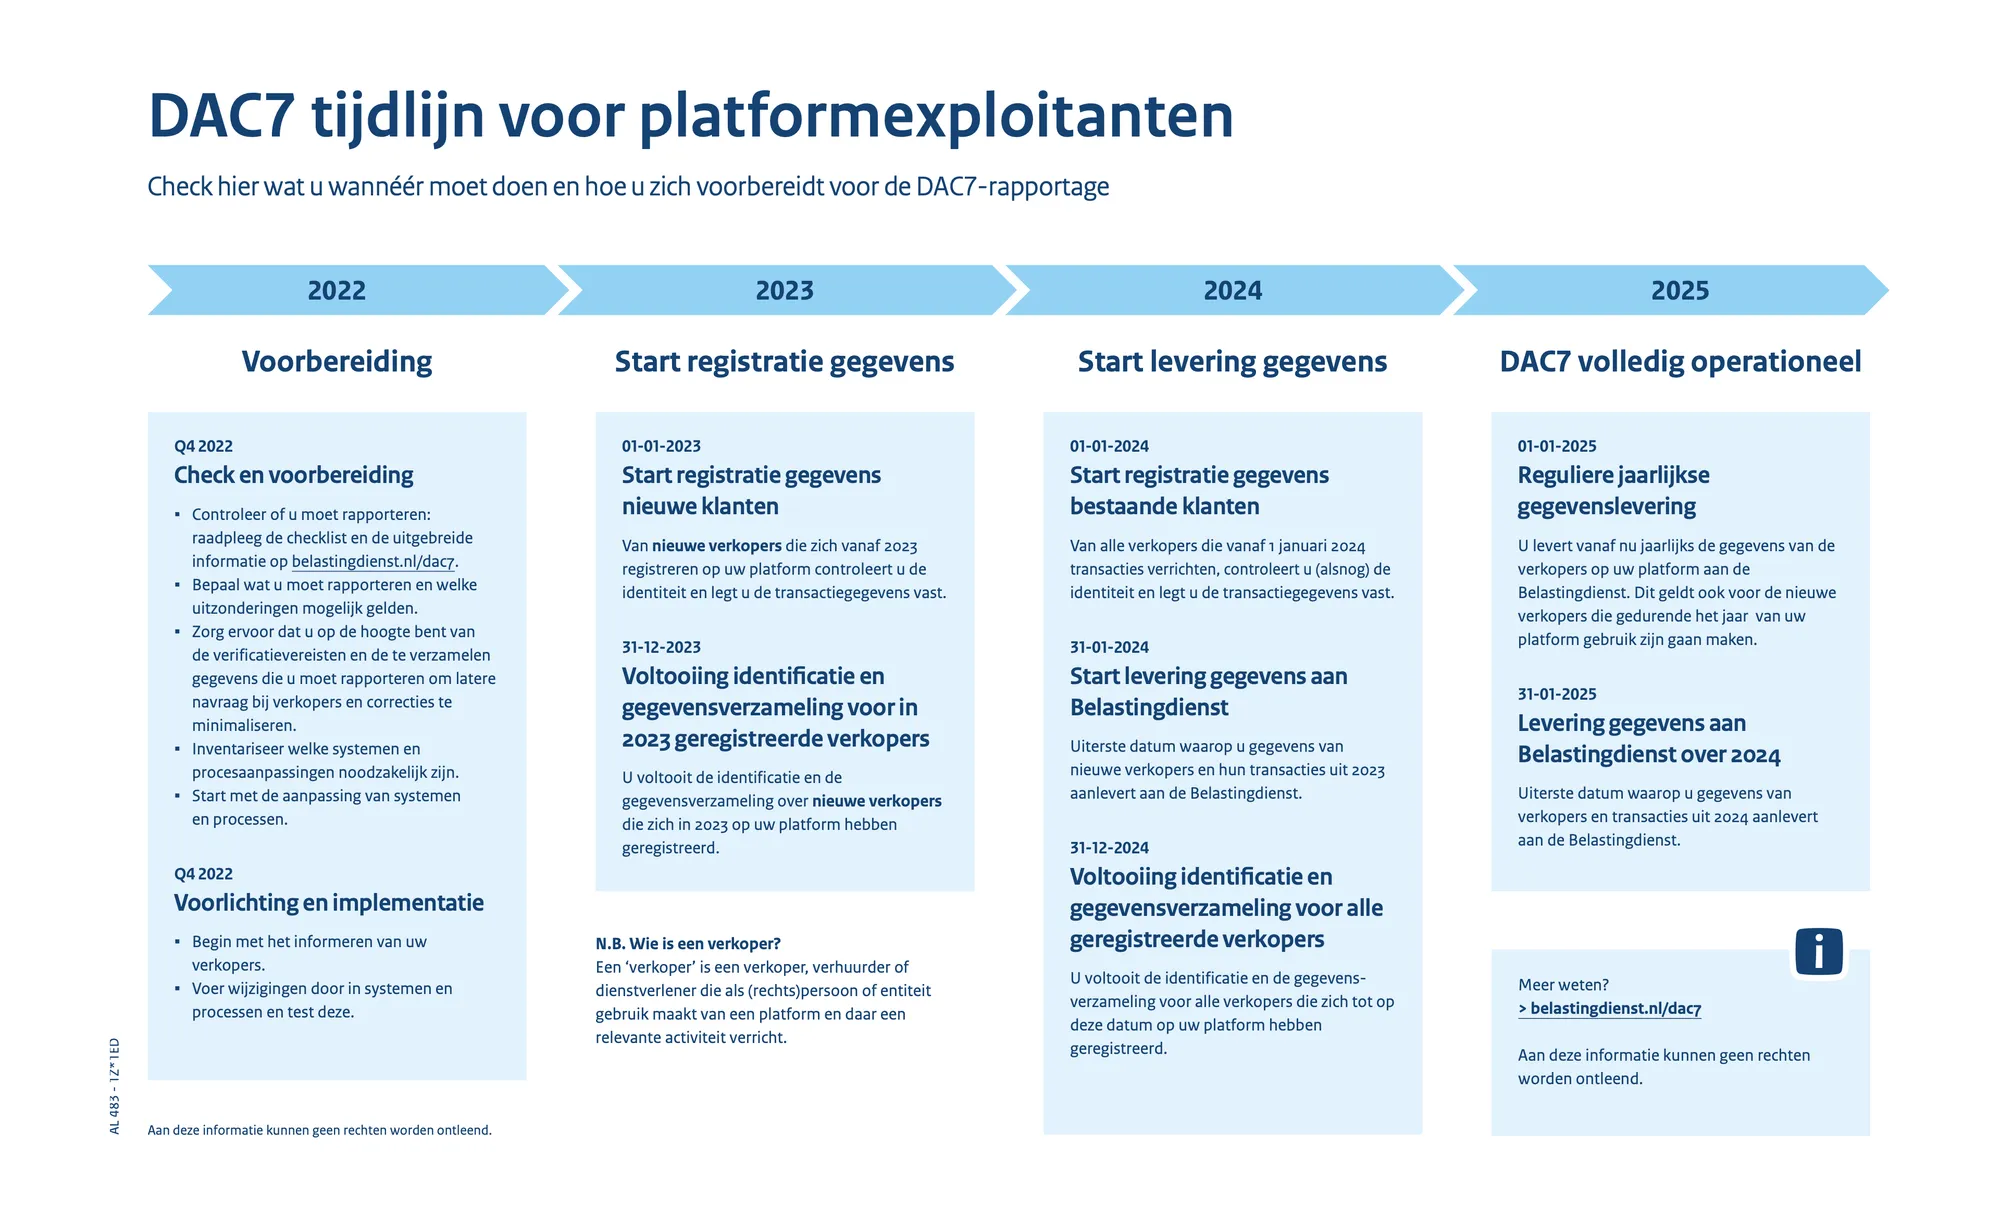
While the directive sets a common framework, EU member states adopted DAC7 at different times and set their own penalties. Spain’s law of May 2023 applied DAC7 from 1 January 2023, but the detailed rules followed only in early 2024, so the first Spanish reports, for 2023, were due between 6 February and 8 April 2024, according to Spain’s tax agency. Sweden fines per seller: SEK 2,500 for each seller whose report or checks are missing, and up to SEK 12,500 per seller if the gaps aren’t fixed in time. The Netherlands fines intentional or grossly negligent failures up to its highest fine category, €1,100,000 since 1 January 2026.
The reporting deadline is 31 January in every member state, but a national calendar can move it when it falls on a weekend: Spain’s 2026 window ran to 2 February. Check each year’s date with the tax authority you report to. Non-EU platforms choosing a member state for registration should factor in language, submission interface, and enforcement style.
Which businesses are not reporting platform operators
If your business uses a platform to find and hire contractors, you are the buyer. You are not the platform. The reporting obligation belongs to the platform, not to you.
A company that hires freelance developers through Upwork does not have a DAC7 reporting obligation. Upwork does. A company that sources creative work through Fiverr is not a Reporting Platform Operator. Fiverr is. The entity that contracts with sellers and operates the technology facilitating transactions is the platform; the entity that pays for services through that platform is the buyer.
Similarly, a business that engages contractors directly outside of any marketplace has no DAC7 reporting obligation under this directive. Direct payment relationships between a business and its contractors do not constitute a platform in the DAC7 sense.
The line that matters: an internal procurement system used to manage your own contractors is not a digital platform under DAC7. A marketplace where third parties transact with each other is. If your business operates a technology product that connects independent sellers to buyers, and you facilitate those transactions, you need to assess whether you qualify as a Reporting Platform Operator.
If your software or community site has evolved into something resembling a marketplace where independent sellers and unrelated buyers interact, seek specialist tax advice before assuming you are outside scope.
DAC7 and the Contractor of Record model
In a Contractor of Record model, a third party contracts with your contractors, invoices your company and pays them.
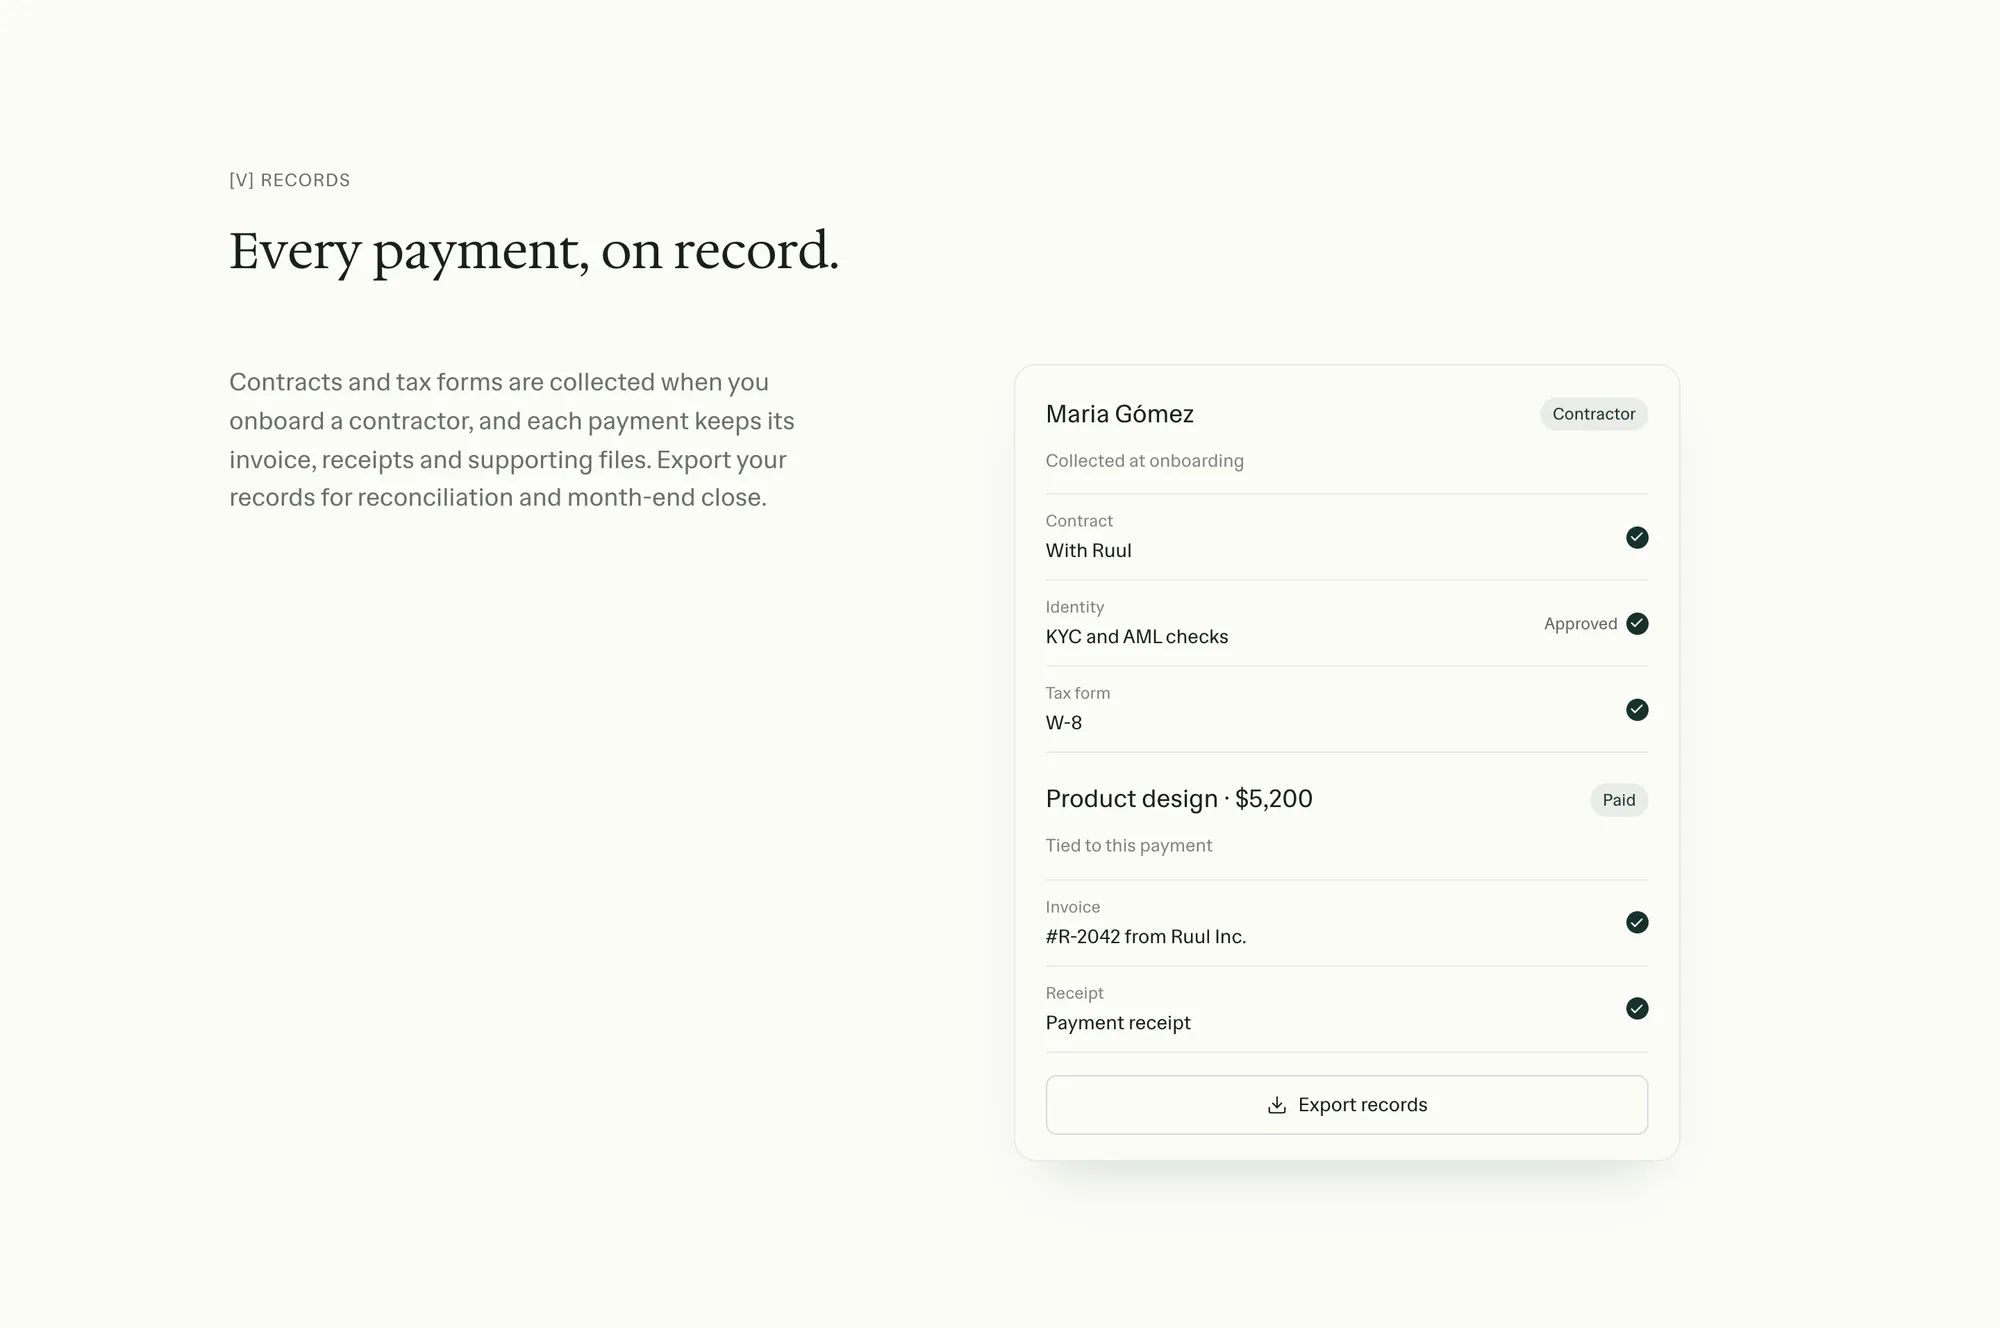
Ruul is that third party, as the legal counterparty for each contractor: it contracts with them, checks who they are, collects their tax forms and issues the invoice to your company. Your company works with one counterparty instead of a contract and an invoice for every contractor.
This doesn’t change your company’s position under DAC7. The reporting duty sits with whoever runs a platform that connects sellers with other users, and a company that pays its own contractors, directly or through Ruul, is the buyer in that picture, not the operator.
What the model changes is the paperwork around each contractor. Contracts, identity checks, tax forms and invoices sit with Ruul and stay in one record you can export, which is how Ruul supports contractor compliance across countries.
Due diligence and onboarding
DAC7 requires platforms to perform structured due diligence on sellers, particularly during onboarding. A compliant onboarding flow typically includes:
- Collecting identity and address information
- Obtaining the seller’s TIN and, where relevant, VAT number
- Verifying names, dates of birth, and registration numbers against identity documents or public registries
- Storing evidence of verification checks in secure internal systems
For sellers who were already on a platform on 1 January 2023, or when the platform first came into scope, the checks had to be finished by 31 December of the platform’s second reporting year: 31 December 2024 for platforms in scope from the start. If contractors still don’t provide the required data after two reminders and at least 60 days, the platform must close their account or withhold their payouts until they do.
DAC7 due diligence is the platform operator’s job, so a business that pays its own contractors, rather than running a marketplace, has none to run. With Ruul’s contractor onboarding, each contractor still verifies their identity and signs the contract with Ruul before their first payout, and their tax forms are collected and kept in one place.
Data protection and GDPR interaction
DAC7 operates alongside the General Data Protection Regulation. Platforms must report seller information to tax authorities while also protecting contractors’ privacy rights under GDPR. DAC7 provides a legal basis for processing contractor data for tax reporting purposes, but GDPR still requires clear privacy notices, disclosure of how data will be used and shared with tax authorities, and appropriate security measures.
Data minimisation and retention limits apply: DAC7 requires records to be kept long enough for enforcement (five to ten years depending on member state), but not indefinitely. If you run a platform, your privacy notice should tell sellers what you collect for DAC7, which tax authority receives it and how long you keep it.
Penalties for non-compliance
DAC7 requires each member state to establish penalties that are effective, proportionate, and dissuasive. The amounts vary significantly by jurisdiction.
| Penalty type | Examples |
|---|---|
| Fines per seller | Sweden: SEK 2,500 for each seller whose report or checks are missing, up to SEK 12,500 per seller if the gaps aren’t fixed in time. Spain: €200 for each seller without the required due diligence |
| Fixed and daily fines | Ireland: €19,045 for a missing, incorrect or incomplete return, plus €2,535 for each day a return remains outstanding |
| Fines for intent or gross negligence | Netherlands: up to the sixth fine category of the Dutch Criminal Code, €1,100,000 since 1 January 2026 |
| Loss of registration | A non-EU platform that hasn’t reported after two reminders from its member state of registration has its registration revoked |
| Exclusion from the EU | As a last resort, member states are to coordinate to stop a non-EU platform that won’t register or report from operating in the EU |
Financial penalties are not the ceiling of the risk. A non-EU platform that still hasn’t reported after two reminders from its member state of registration loses that registration, and it can register again only after giving assurances that it will comply, including with any reports it still owes. Member states are also to coordinate their enforcement, up to stopping such a platform from operating in the EU as a last resort. Both measures are written into the directive itself.
DAC7 data doesn’t stay in the country where the platform files. That tax authority passes each seller’s data to the member state where the seller lives, and for rentals to the member state where the property is, so a gap in one report reaches every country where your sellers are taxed.
Practical steps for platform operators
Step 1: Determine whether you are in scope. Confirm whether your platform facilitates transactions for personal services, property rental, goods sales, or transport rental. If you are purely processing payments or listing without facilitating, the exclusions may apply. Perform a gap analysis of current onboarding, KYC, and payment flows against DAC7 data requirements before drawing conclusions, using our contractor compliance checklist as a cross-check.
Step 2: Implement seller due diligence at onboarding. You need a structured process for collecting and verifying seller information at the point of registration: TINs, VAT numbers, addresses, dates of birth, and bank account details, before sellers begin transacting. Annual aggregation at year-end is not sufficient.
Step 3: Build systems to track reportable transactions quarterly. You need per-seller visibility into consideration paid, transaction counts, and fees withheld, broken down by quarter. Back-end systems must aggregate this data throughout the year, not reconstruct it in January.
Step 4: Register with the appropriate member state tax authority. EU-based platforms report to their home member state. Non-EU platforms must select a single EU member state and register before facilitating activity involving EU-resident sellers. Some member states, Ireland among them, also require every locally based platform operator to register, and even excluded operators to file a nil return.
Step 5: Build the January 31 annual reporting cycle into your operations calendar. 31 December is the due diligence completion deadline. 31 January is the filing deadline. Both are hard dates.
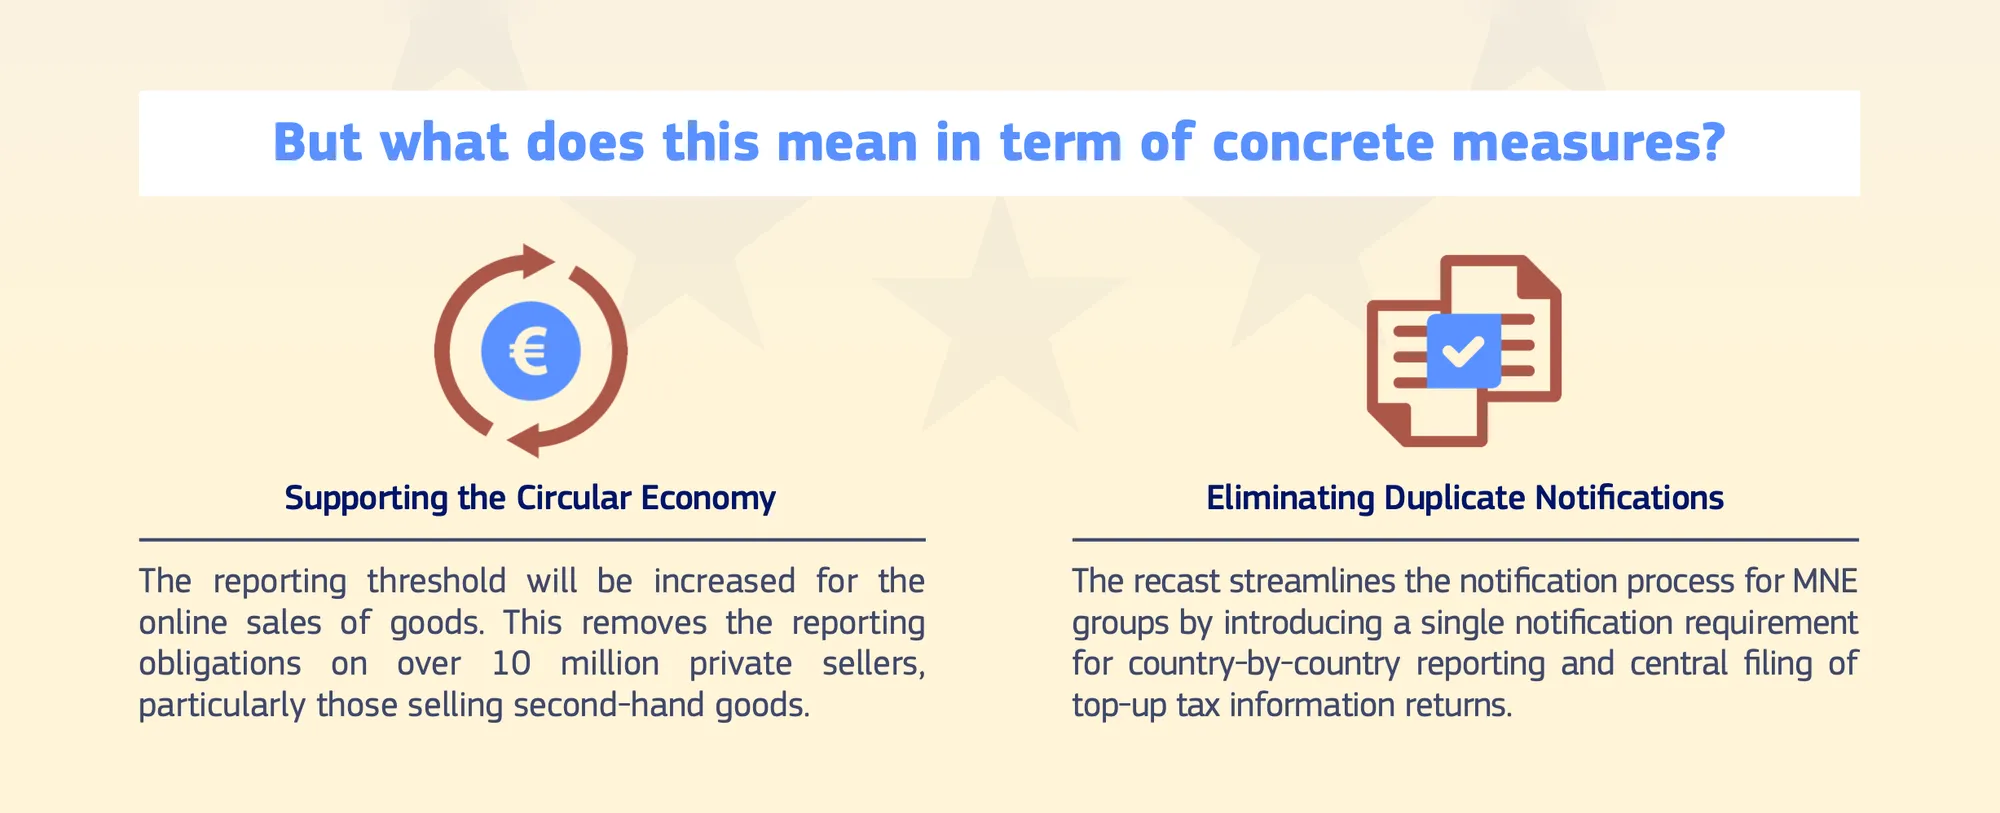
Step 6: Monitor the DAC recast. On 24 June 2026, the European Commission proposed a recast, COM(2026) 308, that would merge DAC1 to DAC9 into a single directive. For sellers of goods, it would drop the 30-sale test and raise the yearly threshold from €2,000 to €3,000, which the Commission says would take more than 10 million sellers out of reporting. The proposal would apply the new threshold from 1 January 2028. Ireland, which holds the presidency of the EU Council until the end of 2026, aims to conclude the negotiations, but member states have to agree unanimously. Reporting on personal services would stay largely as it is.
Step 7: Assign internal ownership and engage qualified EU tax counsel. The technical complexity of DAC7 implementation, including XML schema requirements, TIN validation, GDPR interaction and member state variations, requires specialist advice and a named internal owner responsible for the annual reporting cycle.
Conclusion
DAC7 draws a clear line. If you operate a platform that facilitates contractor and freelance transactions involving EU-resident sellers, you have reporting obligations that are active now. Platforms have already filed three annual reports, for 2023, 2024 and 2025, and tax authorities across the EU are exchanging the data.
If you are a business that hires contractors through platforms, the obligation belongs to the platform, not to you. But if you run a marketplace or platform product, the obligation is yours, and the consequences of ignoring it are substantial.
DAC7 is one piece of the broader contractor compliance picture for businesses engaging contractors internationally. Ruul pays contractors in 190 countries as the legal counterparty for each one: it contracts with them, collects their tax forms and issues your company the invoice.
FAQs
Does DAC7 change how much tax contractors owe?
No. DAC7 does not set tax rates or create a new tax. It only changes what tax authorities can see about platform income. Contractors declare all their income in their own annual return under domestic law, whether it came through a marketplace or from direct clients. Only a qualified local tax advisor can estimate an individual’s liability.
Will contractors receive a DAC7 statement from every platform they use?
They should hear from every platform that reports them. Platforms must give each reportable seller the information they reported about them by 31 January of the following year. DAC7 doesn’t prescribe a named form, so it looks different on each platform: Upwork posts a “Form DAC7” under its tax forms, and Fiverr offers a DAC7 report among its earnings documents. Contractors should keep these with their records for tax preparation, following a contractor compliance checklist for what else to keep on file.
If my company pays contractors through Ruul, does it file DAC7 reports?
Not for paying its own contractors. DAC7 reporting falls on the operator of a platform that connects sellers with other users, and a company that pays its own contractors, directly or through Ruul, is the buyer. With Ruul as the legal counterparty for each contractor, the contracts, identity checks, tax forms and invoices sit with Ruul, and your company remains responsible for its own taxes. If your company also runs a marketplace of its own, assess that separately.
Does DAC7 cover contractors based outside the EU?
Generally not. DAC7 reports cover sellers who live in the EU, plus anyone renting out property located in the EU, wherever their clients are. A platform may still report a non-EU contractor under the OECD’s model rules for digital platforms if they live in a partner country: some EU tax authorities, Ireland’s among them, have exchanged this data with the UK, Canada and New Zealand since 2025. Contractors outside the EU should ask each platform how it reports them and check double taxation questions with a local advisor.
How can my business reduce DAC7 exposure when hiring contractors across the EU?
Hiring contractors doesn’t create DAC7 obligations on its own; running a platform where third-party sellers transact with outside buyers does. If your company doesn’t want reporting duties, don’t build that kind of marketplace, and review your contractor engagement model annually with legal and tax advisors to confirm it hasn’t become one. Paying contractors through Ruul gives your company one counterparty for contracts, checks, tax forms and invoices, but it doesn’t change whether a marketplace you run is in scope.
Written by · Co-founder