Freelance legal requirements in the EU
Learn common legal requirements for freelancers in the EU, including registration, VAT, contracts, invoices, and records.
Summary
Registration is national, so register as a freelancer where you live and put your business number on every invoice. GDPR requires a data processing agreement for client personal data. Late business clients owe €40 plus interest.
On this page
- The two-level EU legal structure
- The EU Platform Work Directive: The most significant recent development
- National self-employment registration: The country-specific layer
- GDPR: Your obligations when handling personal data
- EU Late Payment Directive: Protecting your right to be paid
- Intellectual property: EU-level framework
- Cross-border EU freelancing: Key legal principles
- Contracts in EU context
- Practical starting points for EU freelancers
Important disclaimer: This article explains EU-wide legal frameworks and provides illustrative country examples for informational purposes only. It is not legal advice. The European Union has 27 member states, each with its own national legal system. The EU-wide rules described here apply across all member states at a framework level; their practical effect in your country depends on national implementation. For country-specific guidance, consult a qualified local accountant, tax adviser, or legal professional.
Freelancing in the European Union is not governed by a single rulebook. There is no “EU freelancer law” that applies uniformly to every independent professional across 27 countries. What exists instead is a two-layer structure: a set of EU-wide frameworks that apply everywhere, and a separate national layer that varies significantly from country to country.
Understanding that distinction is the starting point for everything else. Get it wrong, and you end up looking for rules that do not exist at the EU level, or missing obligations that apply squarely at the national level.
The two-level EU legal structure
Several EU-level rules apply in every member state, but not in the same way. The General Data Protection Regulation (GDPR) is a regulation, so it applies directly. Directives, such as the Late Payment Directive and the Platform Work Directive, set rules that each country then writes into its own law. Copyright rests on the Berne Convention, an international treaty that every member state has joined. Together they set common baselines, whether you are based in Tallinn or Toulouse.
Other matters are national: how you register as self-employed, what business structure you operate under, how contracts are governed, what professional licences you need. These rules vary enormously. Germany splits the self-employed into Freiberufler and Gewerbetreibende, France offers the micro-entreprise regime with its own turnover ceilings, and Spain registers anyone who regularly works for themselves as an autónomo.
The practical implication is clear. If you understand the EU-wide frameworks, that knowledge travels with you across borders. If you need to understand your national obligations, you need country-specific expertise. This article covers both layers, but redirects to local professionals for everything that depends on your specific country’s rules.
A note on the UK: The United Kingdom left the European Union on 31 January 2020, and EU law stopped applying there when the transition period ended on 31 December 2020. UK freelancers follow UK rules, covered in a separate guide, though some EU rules, such as the GDPR, can still apply when they offer services to people in the EU.
The EU Platform Work Directive: The most significant recent development
If you work through digital platforms, one EU-level development matters more than any other right now: Directive (EU) 2024/2831 on improving working conditions in platform work.
The directive was formally adopted by the Council on 14 October 2024, signed on 23 October 2024 and published in the Official Journal of the EU on 11 November 2024. It entered into force on 1 December 2024, and member states have until 2 December 2026 to write it into national law.
What the directive does
The core mechanism of the Platform Work Directive is a rebuttable legal presumption of employment. Where facts indicating “control and direction” of a worker by a digital labour platform are found, the working relationship is presumed to be employment rather than self-employment.
If a platform wants to challenge that presumption, the burden falls on the platform, not the worker. The platform must prove the relationship is genuine self-employment under national law. That shift in burden of proof is the directive’s most significant practical effect.
How the presumption works in practice
An important clarification: the original Commission proposal, published in 2021, included a list of five specific criteria (covering remuneration control, appearance and conduct rules, electronic supervision, work organisation, and restrictions on working for third parties). If a platform met two or more criteria, the employment presumption would apply automatically.
The final adopted text removed those five specific criteria. Instead, the directive delegates the definition of “control and direction” to each member state’s existing national labour law and case law. This means the presumption will function differently across the EU. A platform worker in Germany and a platform worker in France may reach different legal conclusions under the same working arrangements, because their countries apply different national standards.
What does not vary is the structural point: once the national standard for “control and direction” is met, the presumption kicks in, and the platform carries the evidential burden to rebut it.
Who this affects
The directive applies to digital labour platforms: services that organise work done by people for pay, whether the work happens online or in a set place, such as delivery, ride-hailing or cleaning. The European Commission estimated in 2021 that over 28 million people worked through digital labour platforms across the EU. Most of them were genuinely self-employed, but about 5.5 million were thought to be wrongly classified as self-employed.
Online platforms for professional tasks such as translation, programming or design can be covered too, but only where the platform organises the work, for example by matching you to tasks and processing payment. A site that only advertises offers or lists available freelancers is not a digital labour platform under the directive. Where the directive does apply, its rules on algorithmic management, such as transparency about automated monitoring and decisions and human review of significant decisions, protect everyone working through the platform, the self-employed included.
The “genuine self-employed” protection
The directive explicitly acknowledges that self-employed people who operate with real autonomy should remain classified as self-employed. The mechanism is designed to catch false self-employment, not to reclassify independent professionals with real business independence.
If you set your own rates, choose your own clients, work on your own schedule and use your own tools, those facts point to genuine self-employment. If the presumption is ever invoked, it is the platform, not you, that has to prove the relationship is not employment.
What this means in 2026
By autumn 2026, with the deadline close, countries were at different stages. Belgium, Portugal and Spain already had presumptions of employment for platform work before the directive: Belgium’s has applied since 1 January 2023, Portugal’s since 1 May 2023, and Spain’s covers delivery platforms only. Germany’s labour ministry was still drafting the implementing law in April 2026, and France appointed a consultation mission in February 2026 to prepare its approach. The Netherlands passed a separate law in June 2026 that, from 31 December 2026, presumes an employment contract when a self-employed person works for less than €38 an hour, an amount that rises with the minimum wage.
If you work primarily through platforms, the most useful step right now is to check your country’s implementation status and understand how the national “control and direction” standard applies to your working arrangement. A local employment lawyer can assess this against your specific situation.
National self-employment registration: The country-specific layer
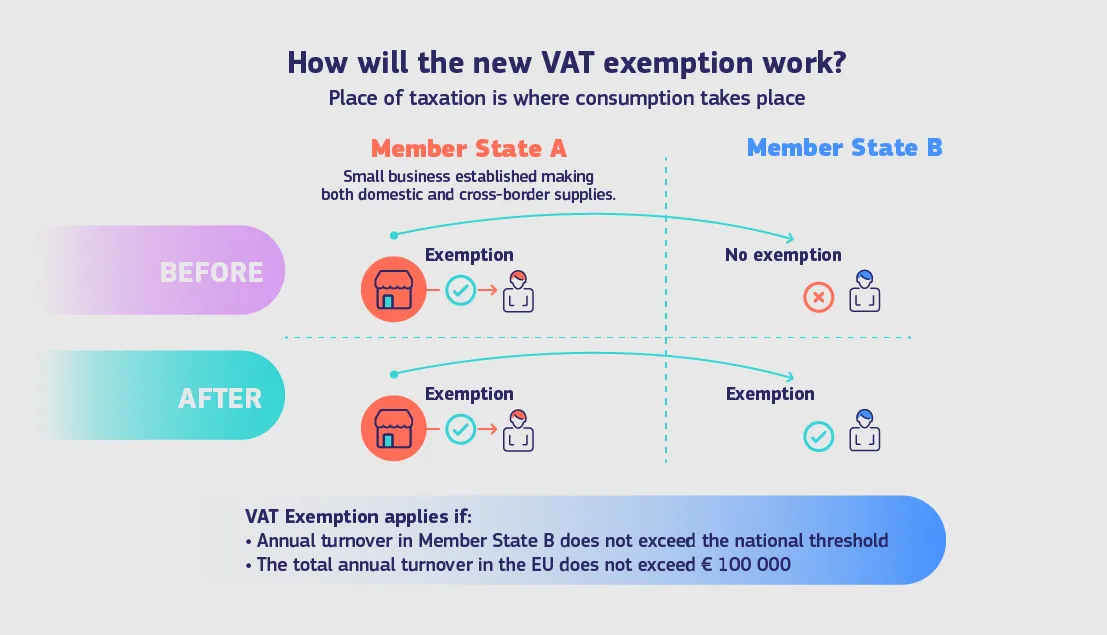
As an EU freelancer, you normally register your self-employment in the country where you live and work. Registration systems differ significantly by country, but most share a common set of elements: registration with the tax authority, social security registration, a business identification number and, often, a VAT number. Many EU countries let small businesses skip charging VAT below a national turnover threshold, which EU rules have capped at €85,000 a year since 1 January 2025, but not every country does, and the thresholds differ. If you sell services to businesses in other EU countries, you usually need a VAT number from the start, even below that threshold. A small business whose total EU turnover stays under €100,000 can also use other countries’ exemptions after registering once at home.
The country examples below are illustrative. They are not comprehensive legal guides. For authoritative guidance on registration in your country, consult a local accountant or adviser.
Germany: Freiberufler vs. Gewerbetreibende
Germany divides self-employed workers into two legally distinct categories. The classification is not a choice you make. It is a determination made by the tax authority based on the actual nature of your work.
Freiberufler (liberal professionals) are defined under §18 EStG of the German Income Tax Act. The listed professions include writers, journalists, translators, architects, engineers, doctors, lawyers and tax advisers. Designers and IT specialists can qualify too, but only when their work counts as artistic or comparable to one of the listed professions, so the answer depends on what you actually do. This classification carries significant legal consequences beyond tax: Freiberufler are not subject to trade regulations under the Gewerbeordnung, are not required to join a Chamber of Commerce (IHK), and are not liable for trade tax (Gewerbesteuer). You register with the local tax office (Finanzamt) within four weeks of starting, using the Fragebogen zur steuerlichen Erfassung (tax registration questionnaire), usually filed online through ELSTER. You receive a Steuernummer once registered.
Gewerbetreibende operate trade-based businesses. They must register with both the Finanzamt and the local trade registration office (Gewerbeamt). They owe trade tax only on profit above an annual allowance of €24,500. Under federal law, anyone assessed for trade tax becomes a member of the local Chamber of Commerce (IHK), in every German state, and small traders who aren’t in the commercial register and make no more than €5,200 in trade profit pay no IHK fee.
The Finanzamt makes the classification call. If you self-classify incorrectly, the legal and tax consequences are material. A Steuerberater (tax adviser) can assess your situation before you register.
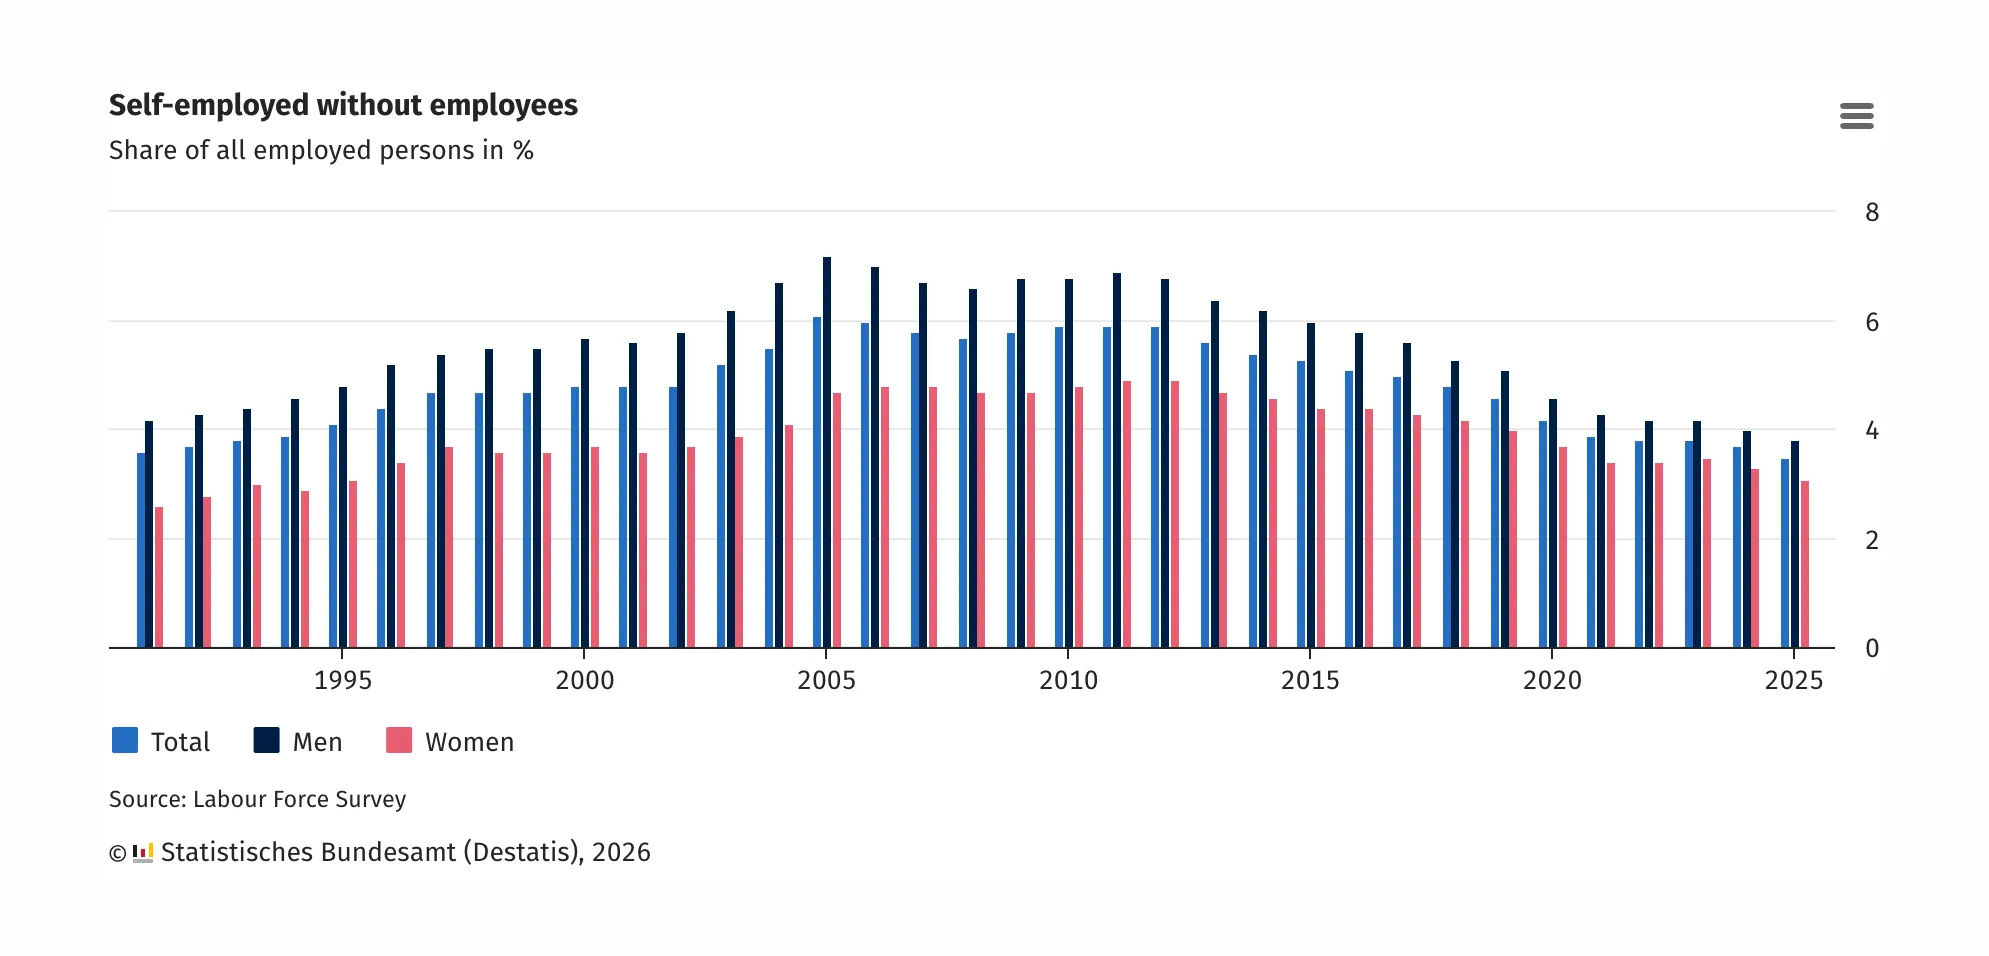
According to the German Federal Statistical Office (Destatis), 3.5% of people in work in Germany aged 15 to 64 were self-employed without staff in 2025, down from 4.2% in 2020.
France: The micro-entreprise framework
France’s micro-entreprise system (also still commonly called auto-entrepreneur, the name used before 2016) provides a simplified legal framework for small self-employed businesses. It is popular among freelancers because of its low administrative burden.
Registration is free and done online through the one-stop shop for business formalities (guichet unique), run by INPI at formalites.entreprises.gouv.fr. Once your registration is processed, usually within about two weeks, you receive a SIREN number (9 digits) and a SIRET number (14 digits). Your SIRET is a mandatory detail on every invoice you issue.
The micro-entreprise regime has turnover ceilings that are revised every three years: for 2026 to 2028 they are €203,100 for commercial activities and €83,600 for services. VAT runs on separate, lower thresholds. Under the franchise en base, you don’t charge VAT as long as your services turnover stayed under €37,500 in the previous year and stays under €41,250 in the current one (€85,000 and €93,500 for sales), and each invoice states that VAT doesn’t apply, currently with the mention “TVA non applicable, art. 293 B du CGI”. Going over the micro ceilings two years in a row moves you to the real tax regime from 1 January of the following year, but your business keeps its legal status. Since 2018, auto-entrepreneurs have been affiliated with the régime général de la sécurité sociale rather than the former self-employed regime. These thresholds change, so check the current figures on impots.gouv.fr or with an accountant.
Netherlands: ZZP and the Wet DBA
In the Netherlands, ZZP’ers (zelfstandigen zonder personeel, the self-employed without staff) register with the Kamer van Koophandel (KVK, the Chamber of Commerce) once they run a business by KVK’s criteria: you work independently, charge for your work and regularly supply people other than friends and family. There is no minimum income. Your KVK number must appear on your invoices, quotes, letters, business emails and website.
The Dutch regulatory picture changed materially on 1 January 2025. That is when the Dutch Tax and Customs Administration (Belastingdienst) ended a long-standing enforcement moratorium on the Wet DBA (the Employment Relationships Deregulation Act). The Wet DBA, in force since 2016, governs when a freelance engagement constitutes genuine self-employment versus a disguised employment relationship. Enforcement was effectively suspended for years. It is no longer suspended.
Since 1 January 2025, the Belastingdienst has been able to impose payroll tax corrections and back-assessments on clients that hire disguised employees, in most cases going back no earlier than 1 January 2025. It imposed no fines in 2025, and from 2026 it can fine deliberate or grossly negligent cases. Working conditions that resemble employment, such as a single dominant client, limited autonomy or ongoing work without a defined project scope, are what draw that scrutiny. From 31 December 2026, a new law also presumes an employment contract when a self-employed person works for less than €38 an hour, and the client then has to prove otherwise. If you work in the Netherlands, check how your arrangements hold up under these rules with an adviser.
Spain: Autónomo
In Spain, anyone who works for themselves on a regular basis must register as an autónomo. The rules set no minimum income: what counts is whether you work habitually, personally and directly, so the obligation can start with your first regular clients.
Registration takes two separate steps: filing a census declaration with the Agencia Tributaria (the tax authority) on Modelo 036, which replaced the simplified Modelo 037 in February 2025, and registering with the Seguridad Social (social security) under the RETA (Régimen Especial de Trabajadores Autónomos), usually through its Import@ss portal. Both registrations are required.
Social security contributions are a monthly cost of operating as an autónomo. Since 2023 they depend on your expected net income: you choose a contribution base within your income bracket, and the Seguridad Social adjusts what you paid once your actual income is known. In 2026 the rates add up to 31.5% of that base, and monthly bases run from €653.59 in the lowest bracket to €5,101.20 at most. New autónomos can apply for a reduced flat fee for their first 12 months (€80 a month for registrations from 2023 to 2025), and for 12 more months if their net income stays below the minimum wage. Quarterly VAT returns are also required, as are quarterly income tax prepayments unless at least 70% of your income was already subject to withholding. These figures change every year, so confirm them with the Seguridad Social or a gestor.
A note on other member states
Every EU country has its own registration framework. Italy has the partita IVA system. Poland requires registration with CEIDG. Sweden, Austria, Portugal, and every other member state operate their own distinct systems. This guide cannot responsibly cover all 27. Consult a local accountant before you begin operating in any EU country.
Tax obligations, VAT rules and social contribution systems are covered in more depth in our guide to freelance taxes in the EU. National registration and tax matters are related but distinct; this article focuses on legal structure and registration, not the ongoing tax filing obligations that follow.
GDPR: Your obligations when handling personal data
If you are based in the EU, the General Data Protection Regulation applies whenever your work involves personal data, whoever the data belongs to. It can also apply to freelancers outside the EU who offer services to people in the EU or monitor their behaviour. That is a broader scope than most freelancers initially assume.
“Processing” covers collecting, storing, accessing, transmitting, analysing, or using personal data in any way. You do not need to be running a large database. If you have access to client email lists, customer records, contact forms, analytics, or any similar data, you are processing personal data and GDPR applies.
Common freelancer scenarios where GDPR applies
Digital marketers with access to client subscriber lists or CRM systems are processing personal data. Developers who build or maintain systems that collect user information are processing personal data. Consultants who receive client employee records or customer files as part of a project are processing personal data. Anyone with a newsletter list is processing personal data. Website owners collecting contact form submissions or analytics data are processing personal data.
If any of these descriptions apply to your work, GDPR is relevant to you.
Core obligations
You need a lawful basis for processing personal data. Common bases for freelancers include contract performance (you need the data to do the work) and legitimate interest. Consent is required in some specific cases, particularly for marketing emails, where EU ePrivacy rules generally require prior consent, with an exception for your existing customers.
For personal data you control yourself, such as your newsletter list or website contact form, you need a privacy notice that tells people what information you collect, why, how long you keep it, and what their rights are. This does not need to be a complex document; a clear, honest single page is sufficient for most freelancers.
You must implement appropriate security measures for the data you hold. “Appropriate” depends on the sensitivity of the data and your role, but basics include using strong passwords, encrypting sensitive files, and not sharing access credentials.
If a personal data breach is likely to put people at risk, the controller must report it to the supervisory authority without undue delay and, where feasible, within 72 hours of becoming aware of it. When you handle data for a client as its processor, your duty is to tell the client without undue delay, and reporting it is the client’s job.
The data processing agreement
This is the obligation most freelancers overlook. Under Article 28 of the GDPR, when you process personal data for a client, you need a written data processing agreement (DPA) with that client, and electronic form counts as written. You are acting as a data processor; your client is the data controller.
If you are a developer with database access, a marketer with CRM access, or a consultant reviewing employee records, a DPA is not optional. It defines what you are permitted to do with the data, how you are required to secure it, and what happens in the event of a breach.
Many freelancers operate without DPAs either because they do not know they are required, or because clients have not requested them. Not having one is a compliance risk for both parties.
GDPR fines can reach €20 million or 4% of annual global turnover, whichever is higher, for the most serious breaches, and €10 million or 2% for breaches of duties such as processing agreements, security and breach reporting. The risk is real, particularly for ongoing access to sensitive client data. The supervisory authority in your country is the relevant body for any queries about your specific obligations.
EU Late Payment Directive: Protecting your right to be paid
Directive 2011/7/EU on combating late payment in commercial transactions establishes statutory rights for freelancers across all EU member states when clients pay invoices late.
The directive covers commercial transactions between businesses, which includes freelancer-to-business invoices. When a client pays late, three automatic rights arise: the right to charge interest, the right to claim a minimum compensation of €40, and the right to recover reasonable collection costs. These rights arise without the necessity of a reminder. You do not need to send a reminder or threaten legal action. The rights activate the day after the payment due date passes. If your contract sets no payment date, payment is due 30 days after your client receives the invoice, and business-to-business payment terms can’t exceed 60 days unless both sides expressly agree and the term isn’t grossly unfair to you.
The statutory interest rate is the reference rate plus at least 8 percentage points a year. In euro countries, the reference rate is the ECB’s main refinancing rate on 1 January for the first half of the year and on 1 July for the second half: it was 2.40% on 1 July 2026, so the minimum rate for late payments in the second half of 2026 is 10.40% a year. National law can set it higher, and countries outside the euro use their central bank’s rate. Interest runs on the full invoice amount including VAT, as the Court of Justice of the EU confirmed in BFF Finance Iberia (C-585/20).
The €40 compensation applies per late payment, not per contract. For clients who pay multiple invoices late under a single contract, the compensation applies to each.
Note: In 2023 the European Commission proposed replacing the Late Payment Directive with a directly applicable regulation (COM(2023) 533), with a strict 30-day payment limit and €50 compensation per late invoice. The European Parliament adopted its position in April 2024, but as of October 2026 the Council had not agreed on its own, so the proposal is not law and the existing directive still applies.
Intellectual property: EU-level framework
Copyright in the EU is grounded in the Berne Convention, an international treaty that all 27 member states have joined. The core principle is automatic protection: copyright arises from the moment of creation, without registration or any other formality. As the European Commission’s Your Europe portal confirms, if you create literary, artistic, or scientific work, you automatically have copyright protection from the moment you create it.
The EU has also harmonised aspects of copyright law through directives, including the InfoSoc Directive (2001/29/EC), which harmonises reproduction rights, distribution rights, and communication to the public rights. In EU countries, protection runs for 70 years after the death of the author.
The default position is that you, the creator, own the copyright to your work. However, specific rules about commissioned work, employer ownership, moral rights, and the practical scope of copyright transfer vary by member state. Germany and France both have strong moral rights traditions, meaning authors retain personal rights in their work even after economic rights are transferred. The rules in your specific country may differ.
The practical implication for your freelance practice: never rely on default rules. Use a written contract that explicitly addresses IP ownership, what rights are transferred, what rights you retain, and on what terms. A governing law clause is particularly important for cross-border engagements, because default rules are not the same in every country.
Cross-border EU freelancing: Key legal principles
The EU treaties protect the freedom to provide services across borders: Article 56 of the Treaty on the Functioning of the European Union (TFEU) prohibits restrictions on providing services between member states. In practice, as a freelancer established in one EU country, you can usually serve clients in another without setting up a company there. How far that goes depends on how often, how long and how regularly you work there, and some activities need a notification or authorisation in the host country.
For purely remote work, the picture is simpler. You stay registered in your home country and usually pay income tax there. VAT follows its own rules: when you invoice a business client in another EU country, you normally don’t charge VAT, your invoice shows both VAT numbers and the words “Reverse charge”, and your client accounts for the VAT in its own country.
Working on-site in another EU country
If you physically travel to another EU country to work on-site, the Posted Workers Directive (Directive 96/71/EC, amended by Directive (EU) 2018/957) is not the rule to look at: it covers employees sent abroad by their employer. For a self-employed freelancer, the question is social security. You can usually stay insured in your home country while working temporarily in another EU country for up to two years, if you apply for a PD A1 certificate from your home country’s social security institution before you go.
Some countries also ask self-employed people from abroad to declare their work before they start. Belgium’s Limosa declaration is one example.
If your work regularly takes you on-site in other EU countries, get advice specific to your situation.
Governing law for cross-border contracts
Contract law is national. There is no EU-wide contract law for private commercial transactions. For cross-border contracts, the law that governs the contract is determined either by agreement between the parties, or by Regulation (EU) No 593/2008 (Rome I) if there is no choice of law clause.
Always include a governing law clause in cross-border EU contracts. It removes ambiguity about which country’s law applies in a dispute. Without a clause, Rome I applies the law of the country where the service provider has their habitual residence, which in most freelance engagements is you.
Disputes over jurisdiction (which country’s courts decide the case) are governed by Regulation (EU) No 1215/2012 (Brussels I Recast). Awareness of both regulations is worthwhile for any freelancer with significant cross-border client relationships.
Professional qualifications
For regulated professions (doctors, lawyers, architects, accountants, and similar), the EU Directive on the recognition of professional qualifications (2005/36/EC, as amended) governs how qualifications recognised in one member state can be accepted in another. If you provide services in a regulated profession across borders, check whether formal recognition is required.
Contracts in EU context
Contract law is largely national in the EU. There is no single European contract law framework for private commercial transactions. What varies from country to country includes how contracts are interpreted, what implied terms apply, how damages are assessed, and what remedies are available.
Certain practical elements should appear in every contract regardless of which country’s law applies: a clear scope of work, defined payment terms with specific due dates, IP ownership provisions, confidentiality terms, and a dispute resolution mechanism.
For cross-border work, always add a governing law clause specifying which country’s law governs the contract, and a jurisdiction clause specifying which country’s courts have authority to hear disputes. These two clauses do significant work in a disagreement. Without them, Rome I and Brussels I Recast fill in default rules, but default rules are not always what you would choose.
For freelancers with ongoing retainer arrangements, subscription invoicing charges your client’s card weekly or monthly and issues a separate invoice for each period, so you don’t recreate the same invoice every month.
Practical starting points for EU freelancers
Register as self-employed in your country of residence as a first step. The registration form, the authority you register with, and the classification you receive all depend on your country. This is the one obligation that applies universally but is executed entirely at national level.
Obtain your business identification number once registered, and your VAT number if you need one. These numbers belong on every invoice you issue: a Steuernummer or VAT ID in Germany, a SIRET in France, a KVK number and VAT ID in the Netherlands, or the local equivalent in your country. Invoicing without them creates compliance risk.
Assess your GDPR obligations before you start handling client data. If your work involves accessing, processing, or storing personal data of individuals, GDPR applies. Get a data processing agreement in place with any client whose personal data you process on its instructions.
Keep organized records of all invoices, contracts and payments from day one, and check how long your country requires you to keep them. Ruul keeps every invoice and payment in your account and lets you export your transactions and a summary for your accountant, so you are not scrambling when filing season arrives.
Use written contracts for every client engagement. Be explicit about scope, payment terms, IP ownership, and, for cross-border work, governing law. The discomfort of raising these terms upfront is smaller than the cost of resolving a dispute without them.
If you work through platforms, understand your country’s approach to the Platform Work Directive. The transposition deadline is 2 December 2026, and countries are at different stages. If a platform sets your pay, directs your work or limits who else you can work for, the legal landscape in your country is shifting.
Consult a local accountant or legal adviser. EU legal complexity justifies professional guidance. The cost of incorrect registration or misclassification significantly exceeds the cost of getting advice.
EU freelance legal requirements are manageable with the right local guidance. For the wider picture on contracts, IP and the payment protections that apply everywhere, see our freelance legal requirements guide.
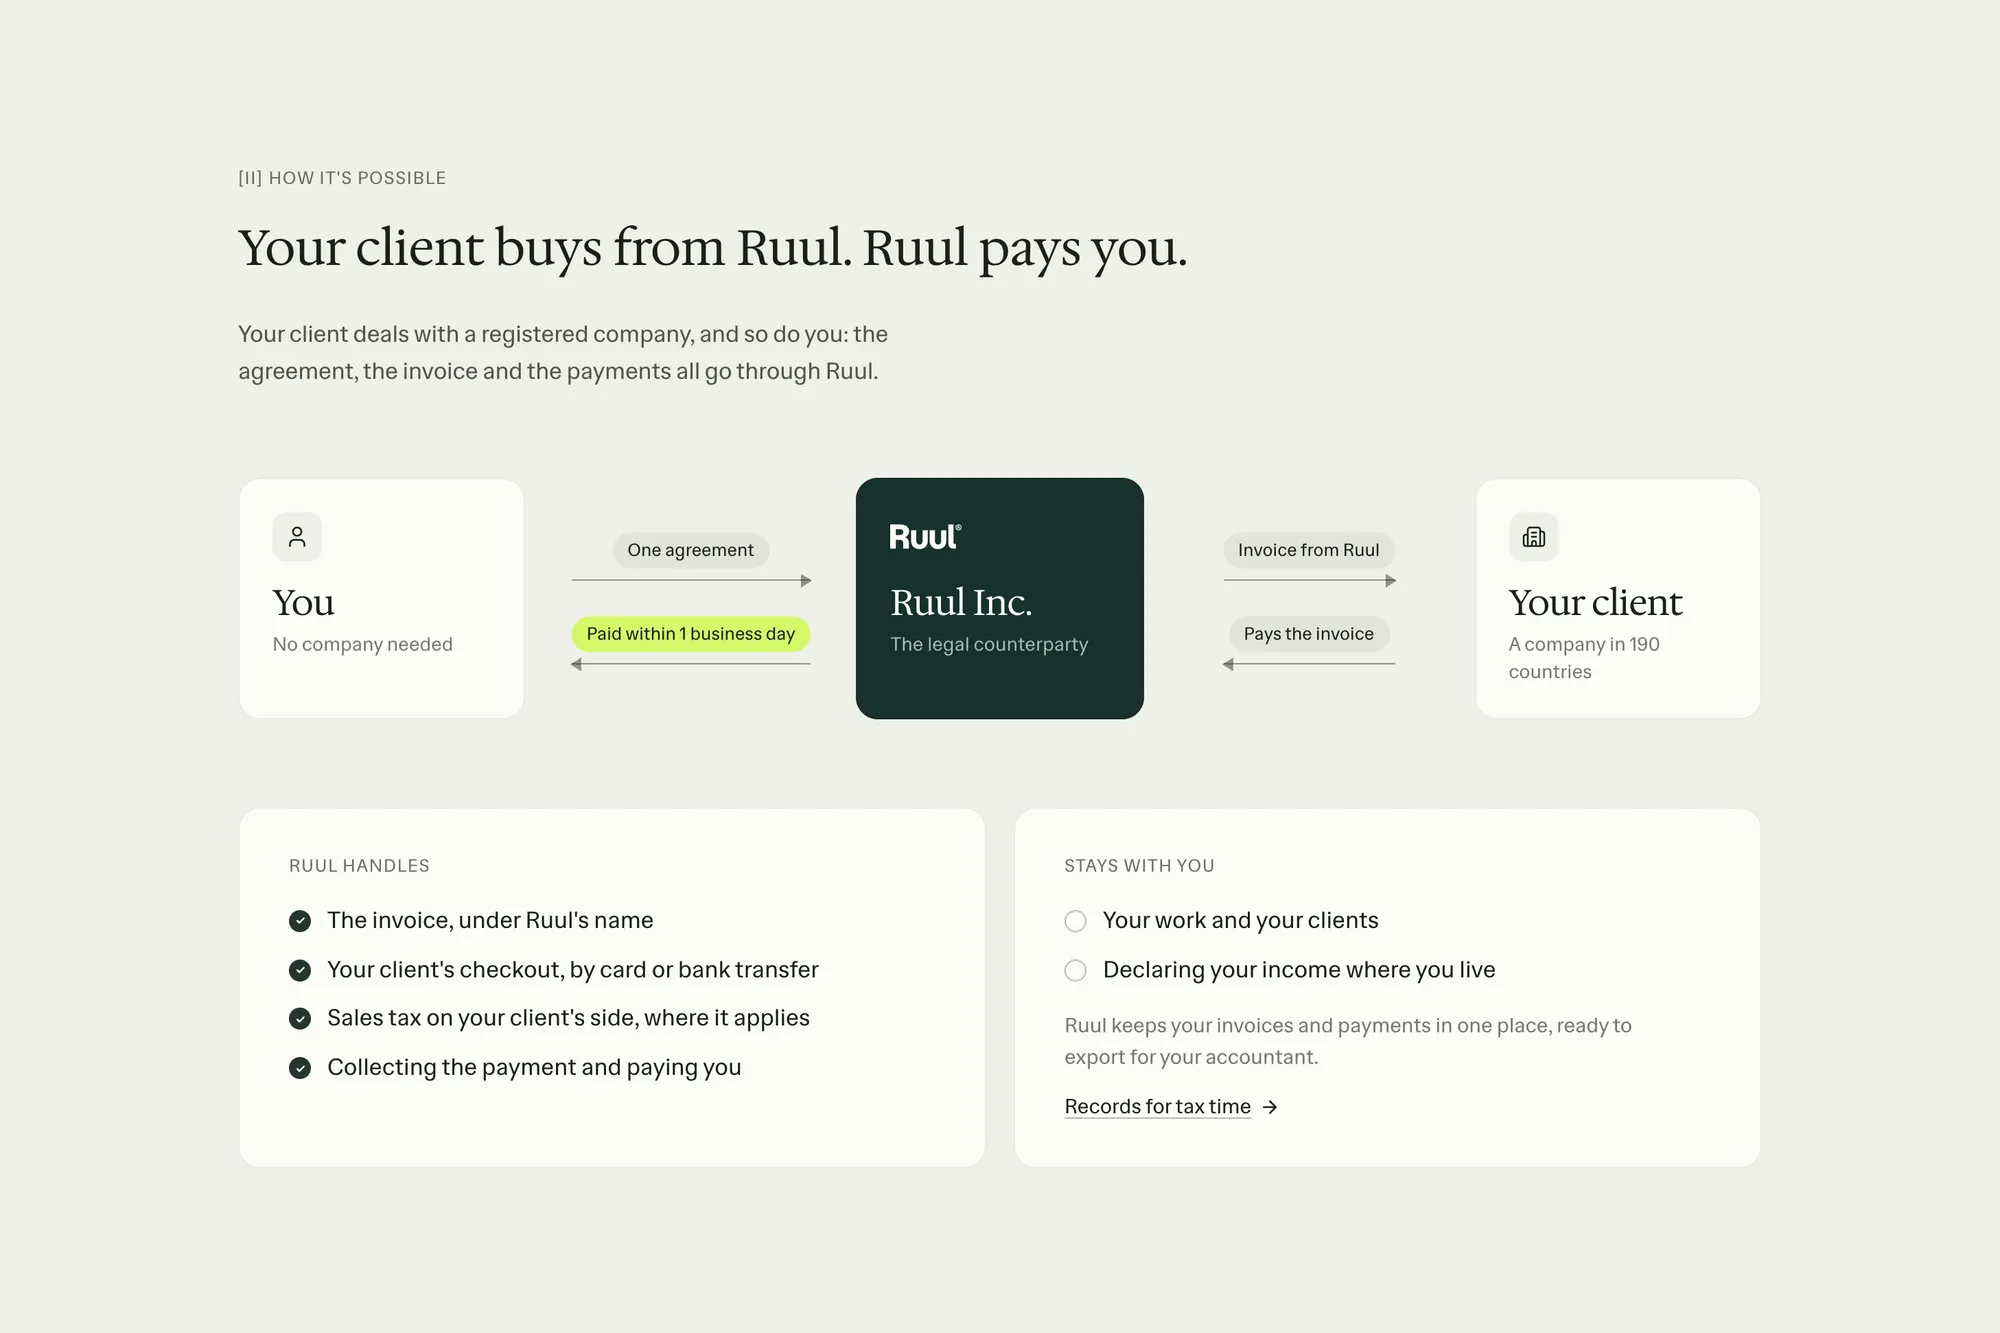
When you invoice clients in other countries, Ruul lets you do it without a registered company: Ruul invoices your client under its own name as the legal counterparty, collects the payment and pays you within one business day after your client pays, with clients in 190 countries and payments in 140+ currencies. Declaring that income where you live stays with you, so ask your accountant which of the registration steps above apply to you. If you prefer to receive earnings in crypto, Crypto Payout lets you withdraw in USDC while your clients keep paying the usual way.
Written by · Co-founder