Freelance taxes in the EU
Learn how freelance taxes work across the EU, including VAT basics, local rules, records, and cross-border client payments.
Summary
The EU sets VAT rules, while income tax follows where you live. Invoice business clients elsewhere in the EU without VAT under the reverse charge, once VIES confirms their VAT number. Late business clients owe €40 plus interest.
On this page
- Two layers of tax: What the EU controls and what your country decides
- EU VAT: The framework that applies everywhere
- National income tax: A different system in every country
- Cross-border EU freelancing: Where you pay tax
- EU Late Payment Directive: What you are owed when clients pay late
- DAC7: Your platform income is now visible to tax authorities
- Where to start: Practical steps for EU freelancers
- A note on the UK
- EU freelance taxation is navigable
Important disclaimer: The European Union has 27 member states and 27 separate tax systems. This guide covers EU-wide frameworks and illustrative country examples. It is not country-specific tax advice. Tax rates, thresholds, and registration requirements change. Always verify current rules with a qualified local tax adviser in your country of residence before making decisions.
If you freelance across Europe, tax feels like it should be simple. One market. Free movement. Common rules. The reality is more complicated, and the confusion costs people real money.
The EU does have common tax frameworks, but they apply selectively. VAT follows EU-wide rules. Income tax follows your country’s rules. Social security follows your country’s rules. Knowing which layer you’re dealing with determines what you need to do, and for whom.
This guide explains the structure, so you can ask the right questions of the right people.
Two layers of tax: What the EU controls and what your country decides
Start here. It makes everything else easier to follow.
The EU sets the framework for value-added tax (VAT) across all 27 member states through the EU VAT Directive (Council Directive 2006/112/EC). Every member state implements this directive, which means the core VAT rules for cross-border transactions are consistent across the bloc. That consistency matters enormously if you invoice clients in other EU countries.
Income tax, social security contributions, and self-employment registration are national matters. Each member state has its own system, and EU rules only decide which country’s social security covers you, usually the one where you work. Some countries offer simplified freelancer regimes. Others subject you to the same registration as a registered business. Thresholds, rates, deductions, and filing frequencies all vary.
The practical split: understanding EU VAT rules applies wherever you are in Europe. Understanding income tax requires country-specific knowledge.
One rule for VAT. Twenty-seven rules for income.
EU VAT: The framework that applies everywhere
VAT is where the EU has genuine authority over how freelancers operate across borders. Getting this wrong creates compliance problems. Getting it right avoids most of them.
What EU VAT is
VAT is a consumption tax collected at each stage of the supply chain. Once you are registered for VAT and not covered by a small-business exemption, you charge VAT to your clients and pay it to your national tax authority. Simple in a domestic context. The rules shift once you work across EU borders.
The key variables are: who your client is (business or individual), and where they are located.
B2B cross-border services: The reverse charge mechanism
This is the most practically important EU VAT rule for most freelancers. Understand it once, and it resolves a large part of your cross-border invoicing uncertainty.
When you provide services to a business client located in another EU country, the reverse charge mechanism applies. Article 44 of the EU VAT Directive places the taxable supply in the buyer’s country. Article 196 then shifts the VAT liability from you to your client.
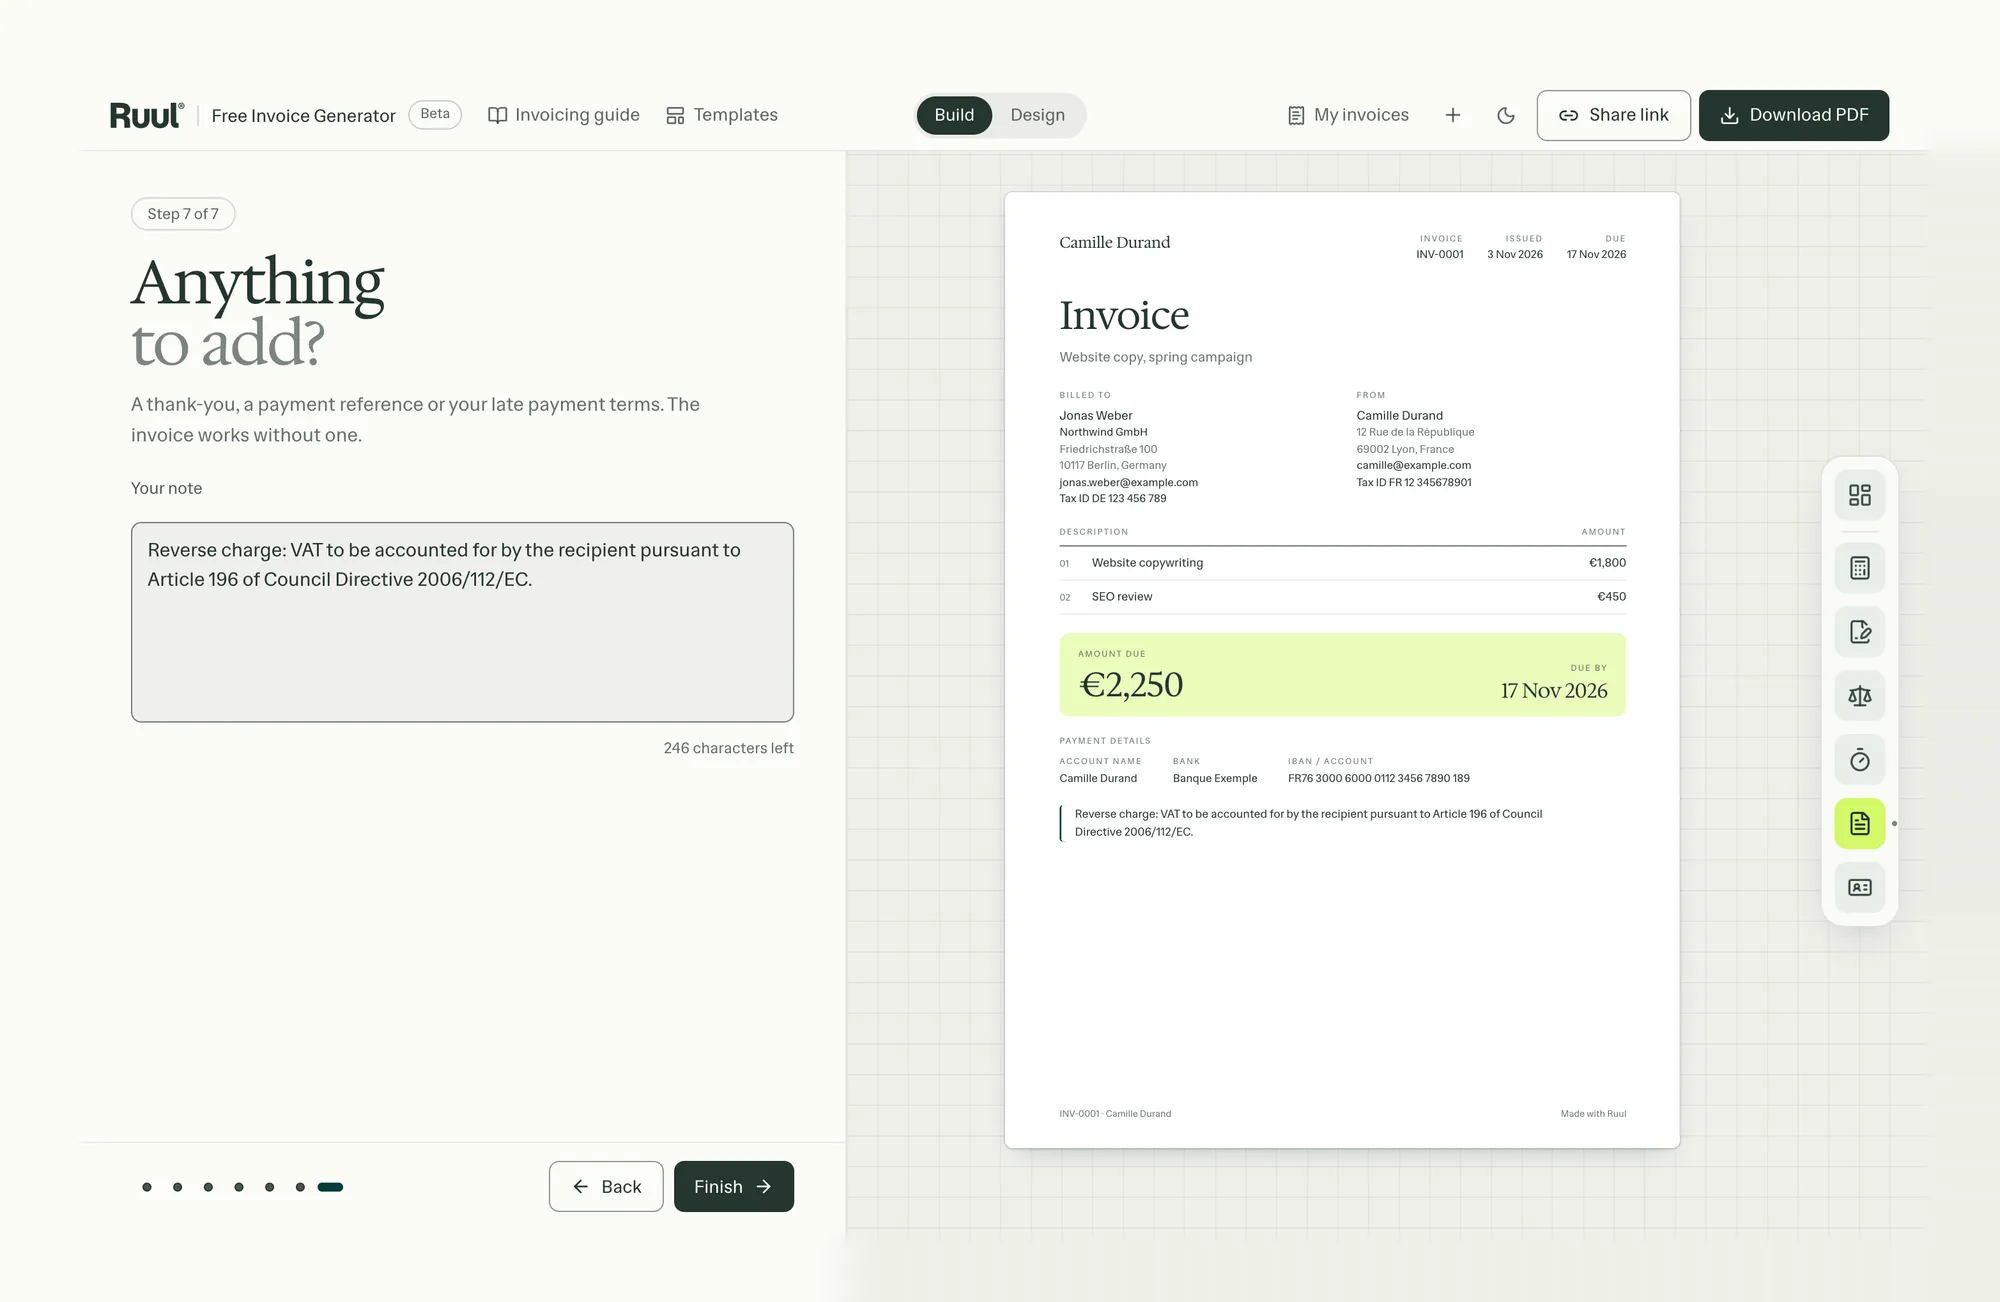
What this means in practice: you issue an invoice with no VAT. Your client self-assesses the VAT in their own country and reports it on their own VAT return. The net effect on their tax position is usually zero, since they declare and reclaim the VAT in the same return. You have no VAT collection obligation in their country, and you do not need to register for VAT there. You do need a VAT number in your own country for these sales, and you may have to list them in a periodic recapitulative statement, often called an EC Sales List.
Your invoice must include a reference making the reverse charge explicit. The phrase “Reverse charge” is now sufficient under EU invoicing rules, though many advisers still recommend the fuller form: “Reverse charge: VAT to be accounted for by the recipient pursuant to Article 196 of Council Directive 2006/112/EC.” Both your VAT number and your client’s VAT number must appear on the invoice.
Before applying the reverse charge, verify your client’s VAT number. The EU’s VIES tool (ec.europa.eu/taxation_customs/vies/) lets you do this in seconds, and it is worth keeping a record of each check. If VIES shows the number as invalid, ask your client to confirm it: a new number may not be activated for EU trade yet, and only their tax office can fix that. If you cannot confirm that your client is a business, treat the sale as one to a consumer and charge VAT. Check every client, every time.
One important limitation: the reverse charge under Article 44 applies to general services, meaning intellectual, professional, and consulting work. Services related to specific physical locations, such as construction or work on a property, follow different place-of-supply rules. If your work involves anything tied to a physical location, verify the applicable rule with your adviser before invoicing.
For most freelancers delivering professional services, writing, design, development, consulting, or marketing, the reverse charge handles the vast majority of EU cross-border invoicing. You send a clean invoice, your client handles their VAT domestically, and you avoid multi-country VAT registration.
B2C cross-border services: Usually your own country’s VAT
The reverse charge only applies to B2B transactions. If your client is an individual consumer rather than a registered business, different rules apply.
For services you sell to individual consumers in other EU countries, the general rule is that you charge VAT as you would at home, at your own country’s rate. The main exceptions are telecommunications, broadcasting and electronic services, such as downloads or automated online services, which are taxed in the customer’s country at their rate. A few other services, such as work on a property or admission to an event, are taxed where they take place.
In practice, most professional freelancers primarily serve business clients, and custom work such as writing, design or consulting usually falls under the general rule. But if you sell digital products or automated online services directly to consumers across EU borders, the OSS system below becomes relevant.
The One Stop Shop (OSS): One registration instead of many
The EU’s One Stop Shop (OSS) solves the multi-country problem for the consumer sales that are taxed in the customer’s country. Rather than registering for VAT in every EU country where those customers are, you register for OSS in your own member state and file one return each calendar quarter covering all of them.
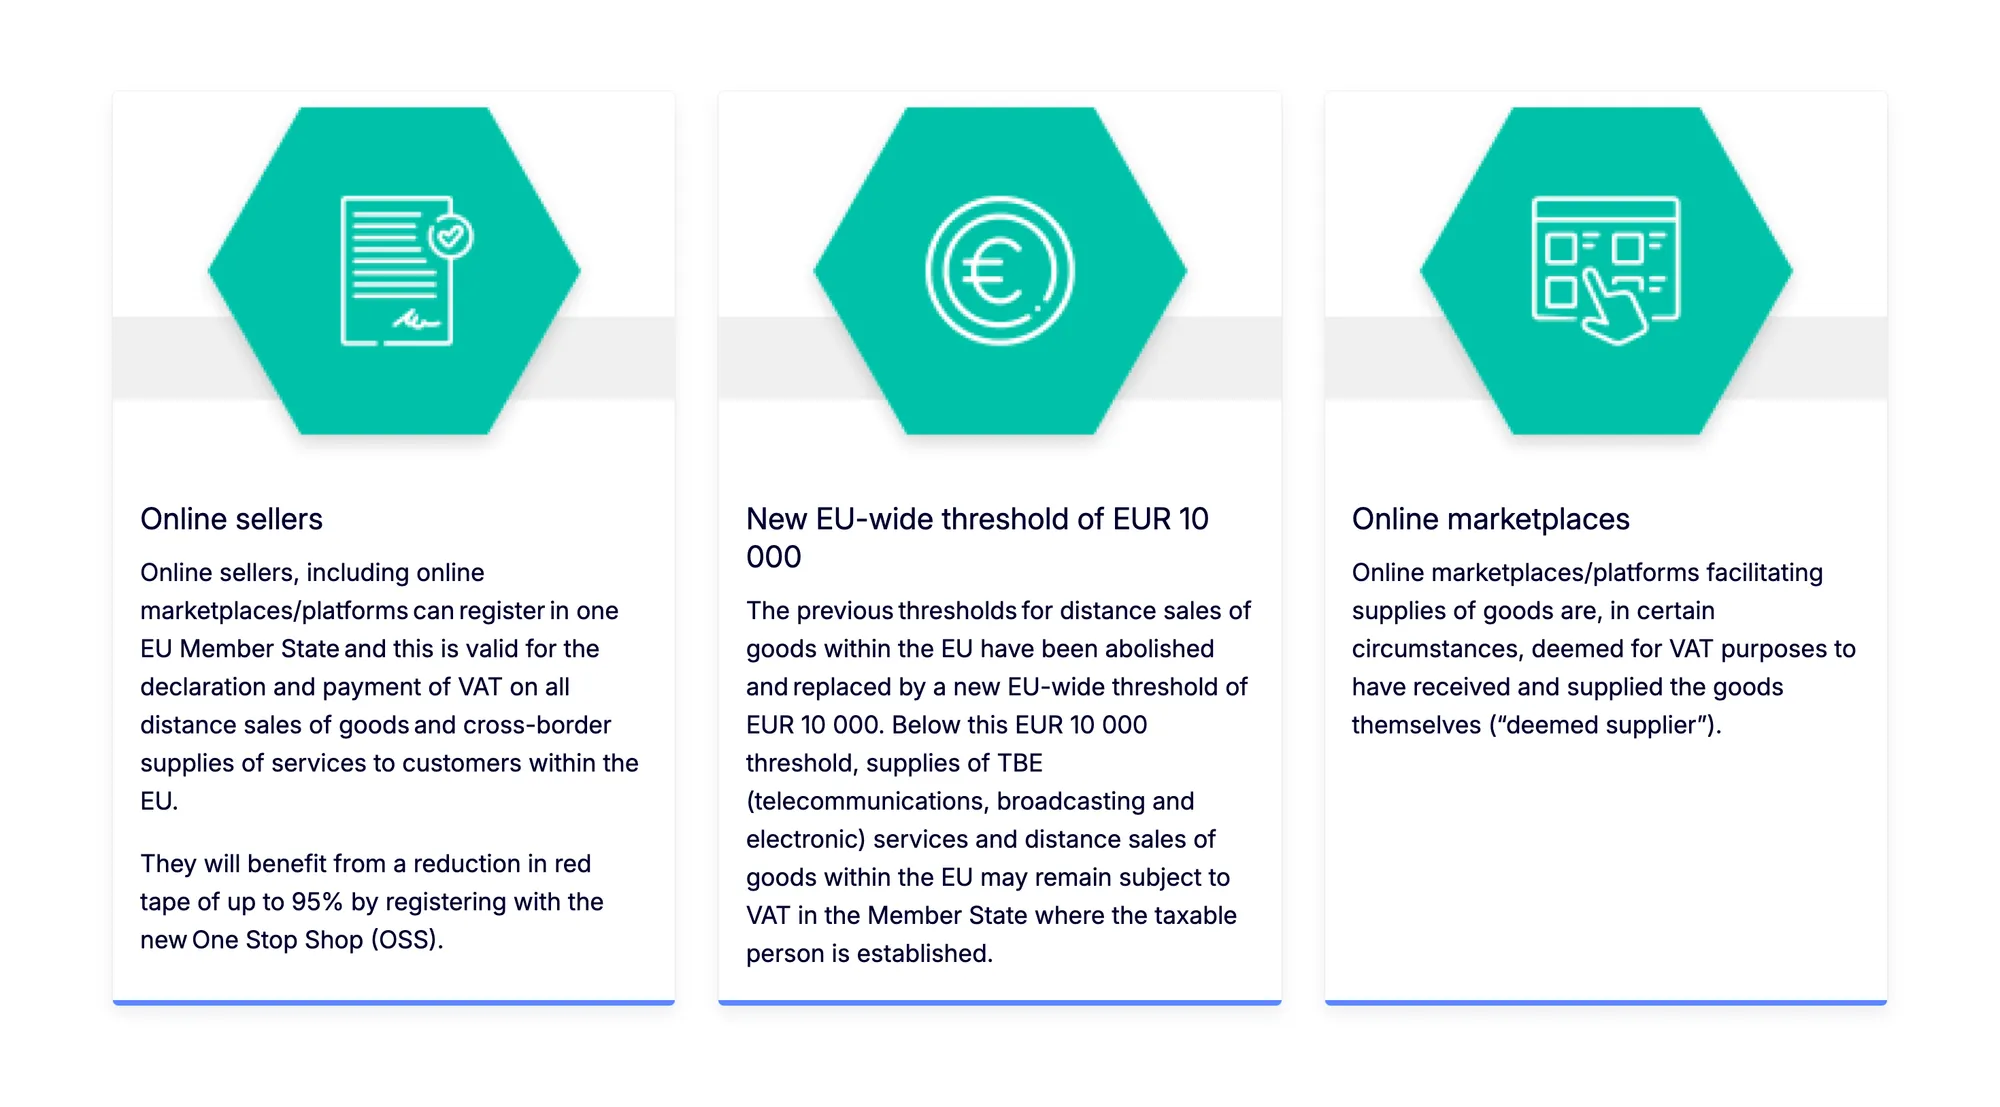
There is a threshold to be aware of. If your total cross-border B2C sales (combining goods and certain services) stay below €10,000 in both the current and preceding calendar years, you may apply your home country’s VAT rate instead of the customer’s country’s rate. Verify this threshold and its specific conditions with your adviser, as they apply to particular types of supplies.
For freelancers doing primarily B2B work, OSS is often not immediately relevant. The reverse charge already handles your cross-border B2B obligations. OSS becomes important when your B2C cross-border sales reach meaningful volume.
If you do register for OSS, records must be kept for 10 years.
National VAT registration thresholds
Most member states let small businesses skip charging VAT on their domestic sales below a national turnover threshold. Since 1 January 2025, EU rules cap that threshold at €85,000 a year, but the scheme is optional, so each country decides whether to offer it and at what level.
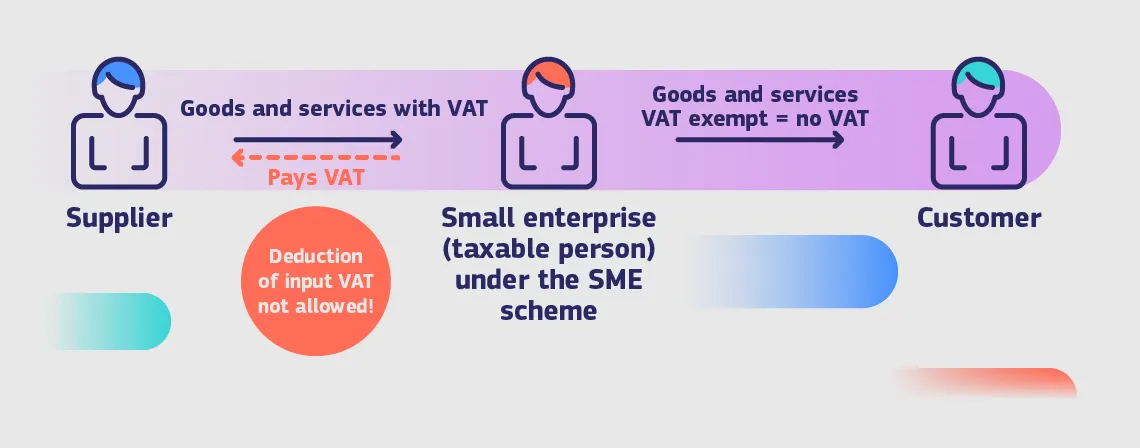
In 2026, Germany’s limit is €25,000 of turnover in the previous year and €100,000 in the current year. France’s is €37,500 in the previous year and €41,250 in the current one for services, the Netherlands lets you opt out of charging VAT up to €20,000 a year, and Spain has no small-business exemption at all, so most freelancers there charge VAT from the start, whatever their turnover. Look up your own country’s rules with your tax authority or a local tax adviser, since thresholds can change in any budget cycle.
One practical note: even if your domestic turnover stays below your national threshold, you normally need a VAT number to invoice business clients in other EU countries under the reverse charge. If you work with business clients abroad, sort this out before your first cross-border invoice.
National income tax: A different system in every country
This is where the EU’s common framework ends and your country’s rules begin. The following sections describe four member state systems as illustrative examples. They are not comprehensive guides to those countries’ tax rules. They show the range of approaches you will encounter across the EU.
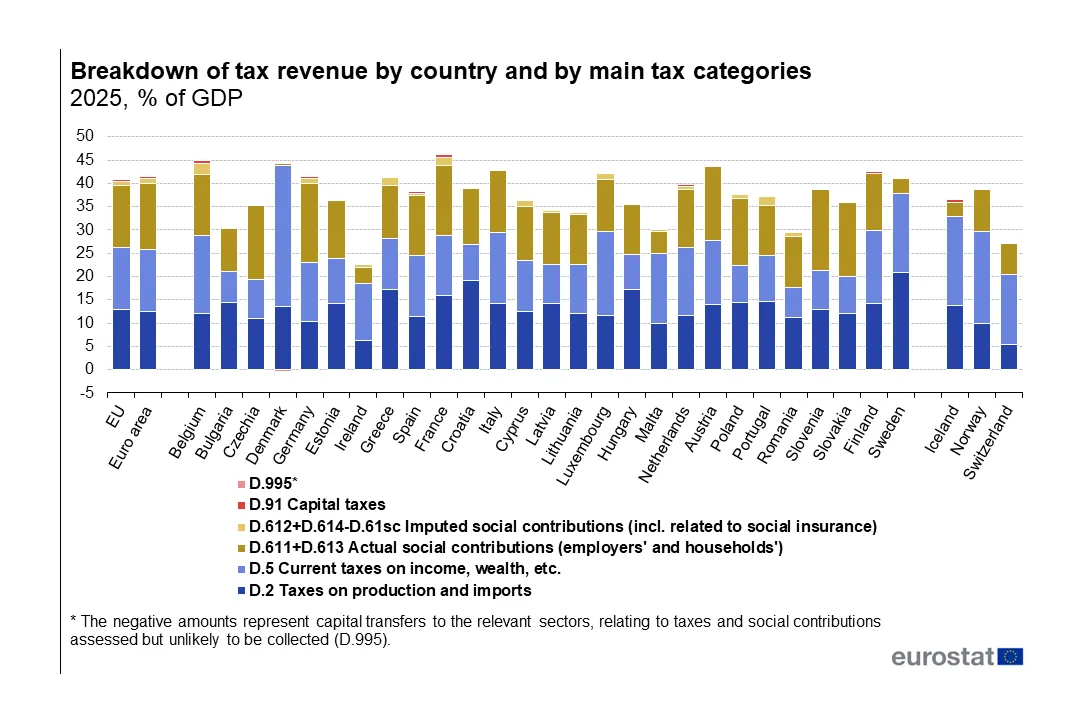
If your country is not covered here, the structural principle is the same: self-employment registration, annual income tax filing, and social security contributions are required. The specifics are yours to verify locally.
Germany: Freiberufler vs. Gewerbetreibende
Germany makes a distinction that matters more than almost anything else in German freelance taxation. Two categories exist: Freiberufler (liberal professions) and Gewerbetreibende (commercial traders). Your category determines your registration requirements, your tax obligations, and your exposure to trade tax.
Freiberufler status covers the liberal professions defined in §18 of Germany’s Einkommensteuergesetz (EStG). Writers, journalists, consultants, architects and lawyers are typical examples. Designers and software developers can qualify too, depending on what the work involves, so the classification is not automatic. The advantages are significant: no trade tax (Gewerbesteuer), no trade registration (Gewerbeanmeldung), and no mandatory Chamber of Commerce membership. You register with your local Finanzamt within four weeks of starting, usually online through ELSTER.
Gewerbetreibende are commercial businesses that do not qualify as Freiberufler. They pay Gewerbesteuer only on profit above an annual allowance of €24,500, must register their trade with the local Gewerbeamt, and face additional administrative requirements.
The classification is not optional. The Finanzamt makes the determination based on your actual professional activity, applying statutory definitions and existing case law. Getting it wrong has real financial consequences. If you are setting up in Germany, professional guidance on classification is not a luxury; it is a safeguard.
Both Freiberufler and Gewerbetreibende file an annual income tax return (Einkommensteuererklärung) and pay progressive income tax. In 2026, the first €12,348 of taxable income is tax-free. Rates then start at 14% and rise to 42% from €69,879 and 45% from €277,826, and the solidarity surcharge only applies once your income tax passes €20,350 (single filers). These amounts change most years, so check the current ones with your Finanzamt or a Steuerberater.
Under the Kleinunternehmer (small business) rule, you don’t charge VAT as long as your turnover was no more than €25,000 in the previous year and stays at or under €100,000 in the current year, the limits that apply since 2025. You can choose to charge VAT anyway, which binds you for five years. Above those limits, you charge VAT like any other business.
This is an illustrative overview only. German tax classification has significant legal consequences. Consult a Steuerberater (tax adviser) before registering.
France: The micro-entreprise regime
France operates a simplified self-employment regime called the micro-entreprise (formerly auto-entrepreneur), designed for small businesses and individual service providers. Its appeal is simplicity: social contributions are calculated as a flat percentage of turnover, accounting is minimal, and registration is straightforward.
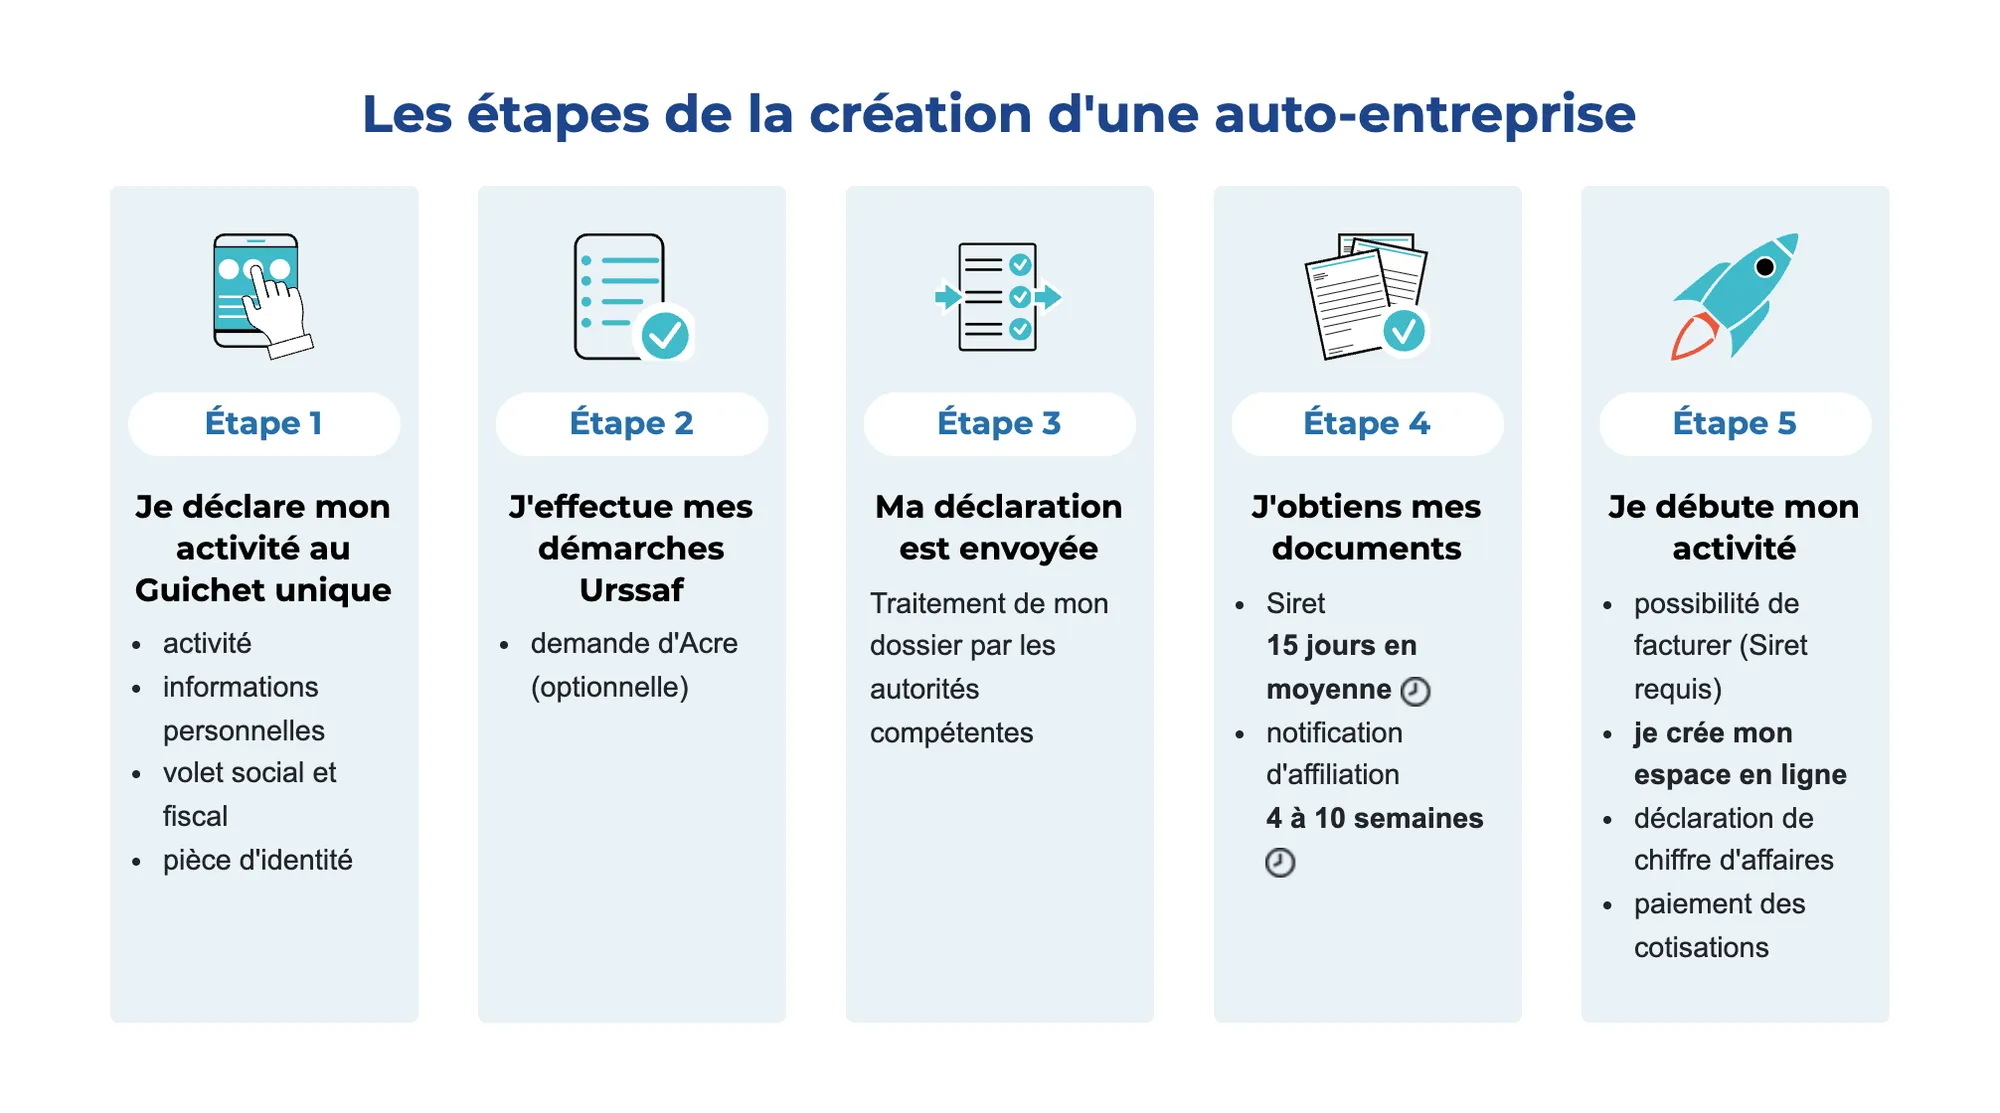
For service providers and professionals (the most common category for knowledge-work freelancers), the micro-entreprise turnover ceiling is €83,600 a year for 2026 to 2028, up from €77,700 for 2023 to 2025. Sales activity has a higher ceiling of €203,100. These ceilings are separate from the VAT threshold, which is much lower.
Social contributions are a flat percentage of turnover. In 2026 the rate is 21.2% for commercial and craft services (BIC) and 25.6% for other services (BNC), the category for liberal professions that aren’t regulated, after a rise on 1 January 2026. Regulated liberal professions covered by the Cipav pay 23.2%. A small training contribution of 0.1% to 0.3% of turnover comes on top. Because these rates apply to turnover rather than profit, they weigh more heavily when your business costs are high. Check the current rates with URSSAF or an accountant.
For income tax, micro-entrepreneurs don’t deduct their real costs. Instead, a flat allowance comes off turnover: 34% for liberal professions (BNC), 50% for commercial and craft services, and 71% for sales, with a minimum of €305. Income tax applies to what remains.
If your turnover goes over the ceiling two years in a row, you leave the micro regime on 1 January of the following year and move to the real tax regime (the déclaration contrôlée for BNC). Your business keeps its legal form, but accounting and tax filing become more complex.
This is an illustrative overview only. France’s micro-entreprise regime has multiple thresholds, transition rules, and options. Consult a French accountant before registering.
Netherlands: ZZP and the declining self-employed deduction
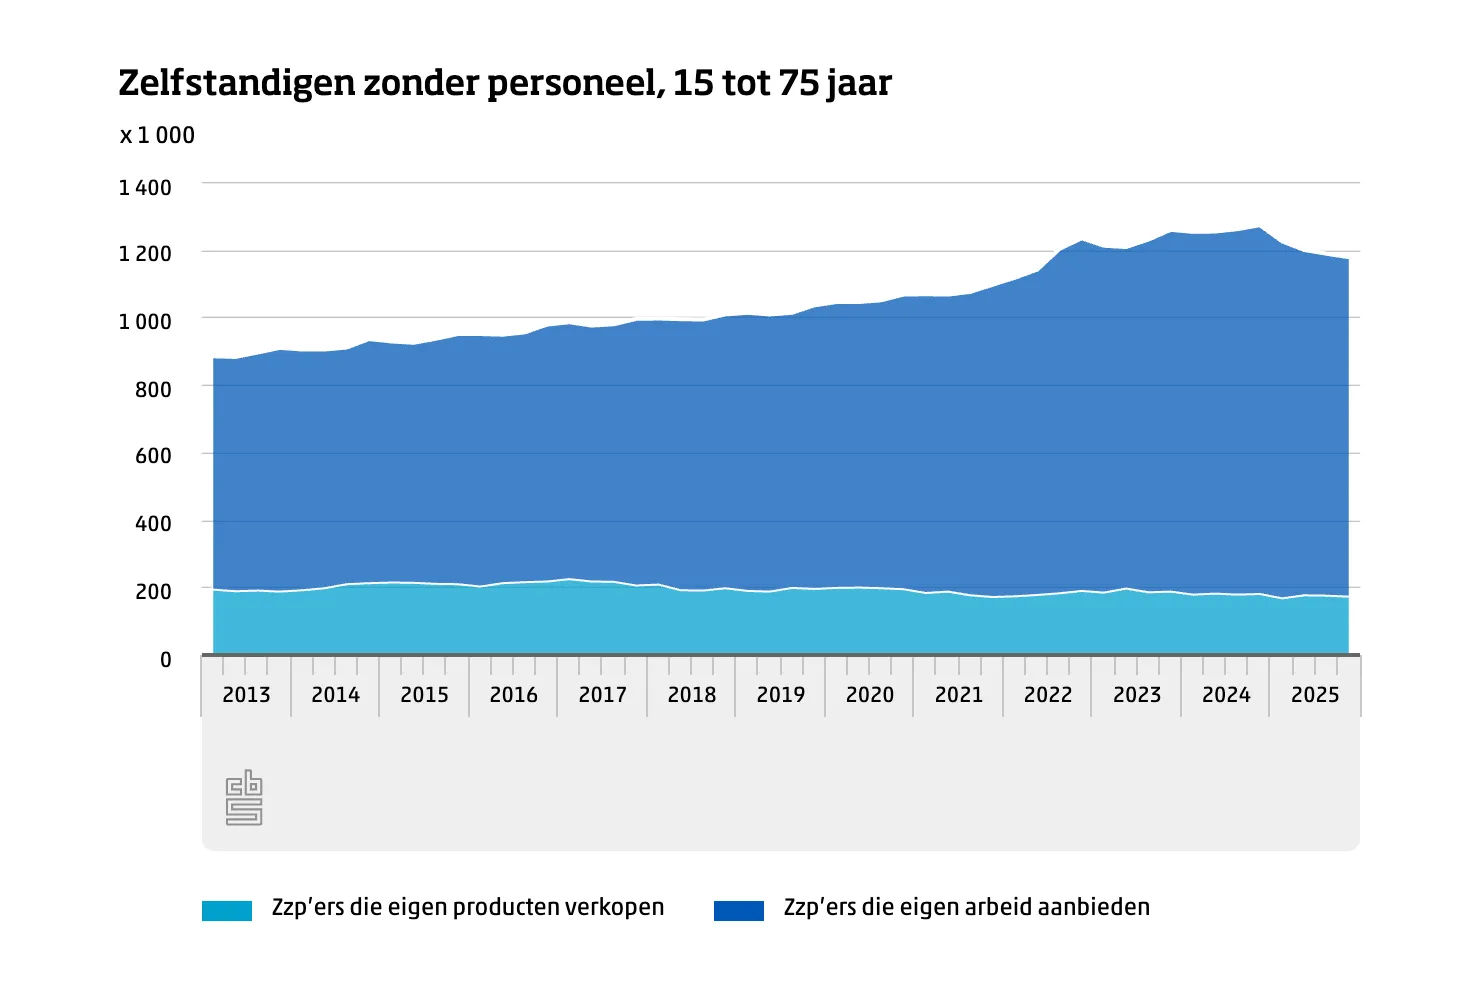
In the Netherlands, independent freelancers work as ZZP’ers (zelfstandigen zonder personeel, the self-employed without staff). You register with the Chamber of Commerce (KVK), which gives you a KVK number and passes your details to the Belastingdienst, the Dutch tax authority.
Your freelance profit is taxed in Box 1 (income from work and home) at the standard progressive rates. In 2026, if you are under state pension age, they are 35.75% up to €38,883, 37.56% up to €78,426 and 49.50% above that, with national insurance contributions included in the first band.
Two historically significant deductions apply to ZZP freelancers. The zelfstandigenaftrek (self-employed deduction) allows a fixed deduction from taxable profit, provided you spend at least 1,225 hours a year on your business and more time on it than on other work. It is being reduced step by step: it was €7,030 in 2020, €3,750 in 2024 and €2,470 in 2025, it stands at €1,200 in 2026, and it is set to fall to €900 in 2027. In 2026 its tax benefit is calculated at 37.56%, whatever your top rate. This is a structural policy shift, narrowing the tax advantage between employees and the self-employed.
The MKB-winstvrijstelling (SME profit exemption) then exempts a percentage of your profit after those deductions: 13.31% in 2024, and 12.7% in 2025 and 2026. Its future is under discussion, so check the current rate before you plan around it.
The startersaftrek (starter deduction) adds €2,123 to the self-employed deduction, up to three times in your first five years in business, if you qualify for the zelfstandigenaftrek. A government proposal from September 2026 would cut it to €10 from 2027 and abolish it from 2028, so check whether it still applies when you file.
For VAT (BTW), there is no threshold to wait for. Once KVK passes on your details, the Belastingdienst sends you a VAT ID (btw-id) for your invoices if it treats you as a VAT entrepreneur. If your turnover is €20,000 a year or less, you can opt into the small business scheme (KOR) and stop charging VAT; apply at least four weeks before the VAT period it should start in.
This is an illustrative overview only. Dutch ZZP rules are subject to active legislative change. Consult a Dutch belastingadviseur (tax adviser) for current figures and planning.
Spain: The autónomo system
In Spain, self-employed individuals register as autónomo under the RETA (Régimen Especial de Trabajadores Autónomos), the special social security scheme for the self-employed.
The autónomo system’s most distinctive feature is its social security contribution requirement. Until 2023, autónomos chose their own contribution base, so what they paid didn’t depend on what they earned. Since 2023, contributions follow expected net income across 15 brackets: you choose a base within your bracket, and the higher your income, the higher your monthly contribution. In 2026 the rates add up to 31.5% of that base, and monthly bases run from €653.59 to €5,101.20. A reconciliation occurs annually against your actual income, resulting in either a refund or a top-up payment.
New autónomos can apply for the tarifa plana when they register: a reduced flat fee of €80 a month for the first 12 months, whatever their income. A further 12 months at the reduced fee may apply if your expected net income stays below the Spanish minimum wage. The €80 was set for registrations from 2023 to 2025, and later amounts are set in the national budget, so confirm the current figure with the Seguridad Social or a gestor.
Income tax for autónomos is declared through the annual IRPF return, with quarterly advance payments (pago fraccionado) due throughout the year.
One aspect that surprises many new autónomos: social security contributions are mandatory from the moment of registration, regardless of whether you have earned anything in a given month. This is a fixed operational cost of working independently in Spain.
This is an illustrative overview only. Spain’s autónomo system has been subject to reform and rates continue to evolve. Consult a Spanish gestor or asesor fiscal before registering.
A note on other EU member states
Every EU member state has its own self-employment registration process, income tax structure, and social security contribution system. Countries not covered here, including Italy’s partita IVA, Portugal’s recibos verdes, Belgium’s various statuses, and the systems across Eastern European member states, all operate under distinct national frameworks. Italy, for example, has a flat-rate regime (regime forfetario) for sole traders with up to €85,000 in revenue, taxed at 15%, or 5% for the first five years of a new activity that meets the conditions.
What is broadly consistent across the EU: you need to register as self-employed in your country of residence, file an annual income tax return, and make social security or pension contributions. The rates, thresholds, and deductions are yours to verify locally.
This guide cannot responsibly provide detailed guidance for all 27 member states. A local accountant who works with freelancers is the right person for that.
Cross-border EU freelancing: Where you pay tax
Working for clients across EU borders does not mean you pay tax in every country where your clients are. Tax residency determines where you pay income tax, and tax residency follows where you live.
The basic rule: Residency determines income tax
As a freelancer, you are typically taxed on your worldwide income in the country where you are resident. If you live in France and work for clients in Germany, the Netherlands, and Spain, you declare your total income in France. Not in Germany, the Netherlands, or Spain.
This applies whether you work remotely or travel occasionally to meet clients. The location of your clients does not, on its own, create an income tax obligation in their country.
The 183-day rule
Each country has its own definition of tax residence. As a rule of thumb, you are usually treated as tax resident where you spend more than six months (183 days) of the year, and that country can tax your worldwide income.
Each country applies this test differently. Some count calendar year days, others use a rolling 12-month period. Some have additional residency tests based on permanent home, family connections, or centre of vital interests. If you are near the threshold, or if your situation is genuinely split between countries, you need specialist advice.
Double taxation treaties
Most EU member states have signed double taxation treaties with each other. These treaties establish which country has primary taxing rights on specific categories of income, and they provide mechanisms to prevent the same income being taxed twice.
In practice, for a freelancer resident in one EU country who earns income from clients in other EU countries, the treaty framework generally supports taxation only in your country of residence. You do not typically owe income tax in your clients’ countries for providing professional services remotely.
Verify the specific treaty between your country and your clients’ countries if you have any doubt. The treaty text and your local tax authority are the authoritative sources.
The permanent establishment risk
Permanent establishment is a concept that becomes relevant if your presence in another country starts to look more like a fixed business operation than remote service delivery. Occasional client meetings do not create this risk. A regular physical office, a dedicated assistant, or operations that look like a branch of a business might.
For most freelancers delivering services remotely, permanent establishment is not an active concern. If you have a substantial physical presence in a client’s country, get professional advice on whether a permanent establishment risk exists.
Moving between EU countries
Changing your country of residence within the EU is a legitimate choice, but it triggers real tax consequences. You may have exit tax obligations in the country you are leaving. You will have registration obligations in the country you are moving to. Treaty provisions apply differently to mid-year moves. The timing of your deregistration and re-registration matters.
If you are planning to relocate, start the tax planning process well before you move.
EU Late Payment Directive: What you are owed when clients pay late
EU Directive 2011/7/EU establishes rights for businesses when commercial clients pay late. As a freelancer invoicing business clients, this directive applies to you.
The directive covers commercial transactions between businesses across all EU member states. Its core provisions give you three automatic rights when a business client pays past the agreed or statutory due date: the right to charge statutory interest, the right to a fixed compensation of at least €40 per late invoice for recovery costs, and the right to recover additional reasonable collection costs.
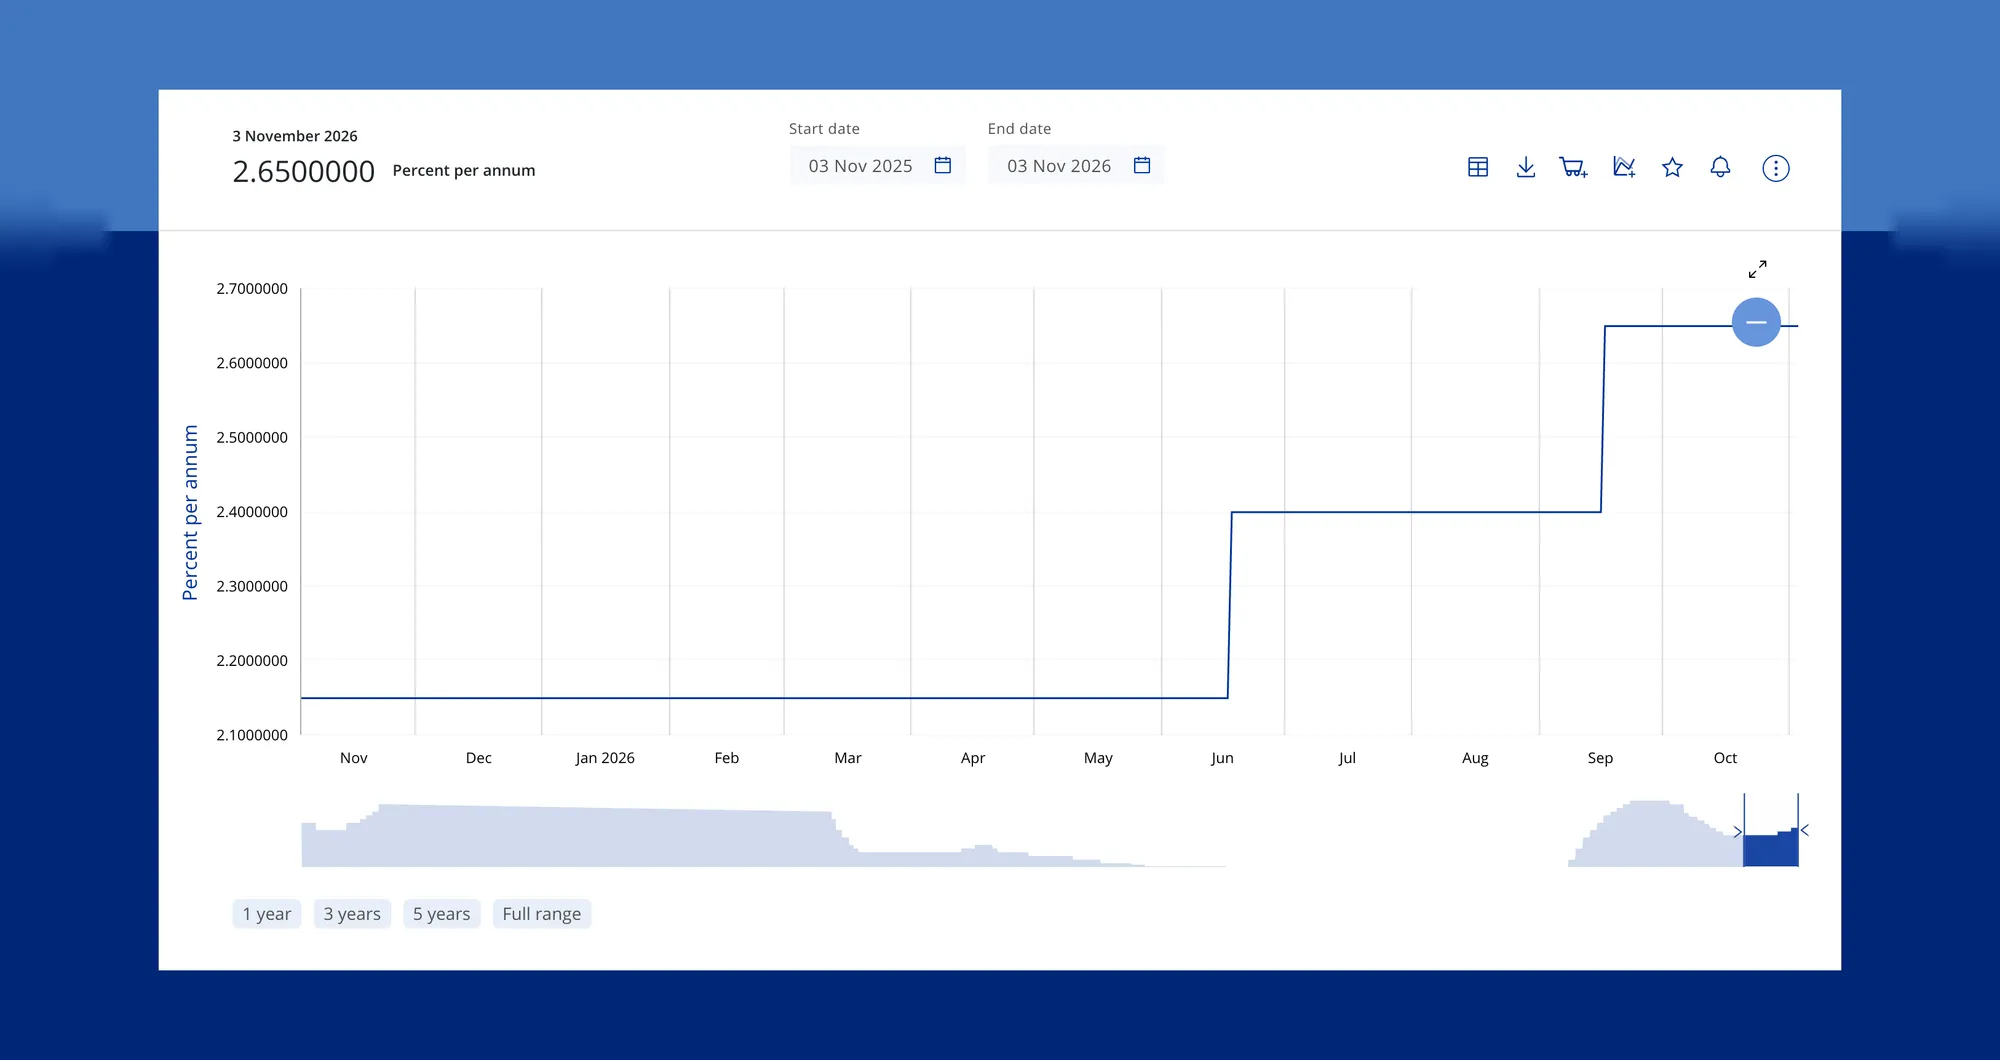
The statutory interest rate is a reference rate plus at least 8 percentage points. In euro countries, the reference rate is the ECB’s main refinancing rate in force on 1 January for the first half of the year and on 1 July for the second half. It was 2.40% on 1 July 2026, so the minimum for late payments in the second half of 2026 is 10.40% a year, and some countries set more, such as 12.40% in France. Countries outside the euro use their own central bank’s rate, and Your Europe lists each country’s current rate. If your contract sets a late payment rate, that rate applies instead. If it sets none, the statutory rate applies by law, with no clause needed.
Charging late payment interest and the recovery compensation is professional behavior, not aggression. The Directive exists precisely because late payment is a structural problem in commercial relationships. You are asserting a legal right.
DAC7: Your platform income is now visible to tax authorities
If you work through digital platforms such as Upwork, Fiverr, or similar marketplaces, Council Directive (EU) 2021/514, known as DAC7, is worth understanding.
DAC7 entered into force on 1 January 2023. The first exchange of information between EU tax authorities took place at the end of February 2024, covering the full calendar year 2023. Reports are submitted annually by 31 January, covering the previous year’s platform activity.
DAC7 does not create new taxes. It changes what is visible to tax authorities. Platforms operating in the EU (regardless of where the platform itself is based) are now required to collect and report seller information to EU tax authorities. This includes your identity, country of residence, tax identification number, total earnings, and number of transactions.
For service providers, there is no minimum threshold: platform income from services is reportable from the first euro. For goods sellers, reporting applies once you make 30 or more sales, or earn more than €2,000, in a calendar year.
The practical implication is straightforward: if you earn income through platforms and have not been declaring it, your tax authority can now see it. The right response is making sure your declared income matches what your platforms report.
DAC7 has also changed how platforms themselves behave. Most major platforms now require identity verification and tax ID confirmation from active users. If your platform asks for this information, provide it promptly: a platform has to close the account of a seller who still hasn’t provided it after reminders.
Keeping centralized records of your platform earnings by country and by year is good practice regardless of DAC7. When you need to reconcile what a platform reports against what you declared, clean records make that process straightforward. For work you invoice through Ruul, every invoice and payment is already in your account, ready to export with a summary for your accountant.
Where to start: Practical steps for EU freelancers
The complexity of EU freelance taxation resolves into manageable steps when you approach it in the right order.
Register as self-employed in your country of residence. This is your first obligation. Registration requirements vary by country, and our guide to freelance legal requirements in the EU walks through them. Operating as an unregistered freelancer creates compliance risk, so do this before you send your first invoice.
Understand your country’s VAT threshold. Find out whether your country exempts small businesses from VAT, up to what turnover, and whether you have to apply for it. Know whether you are above or below it, and what registration requires.
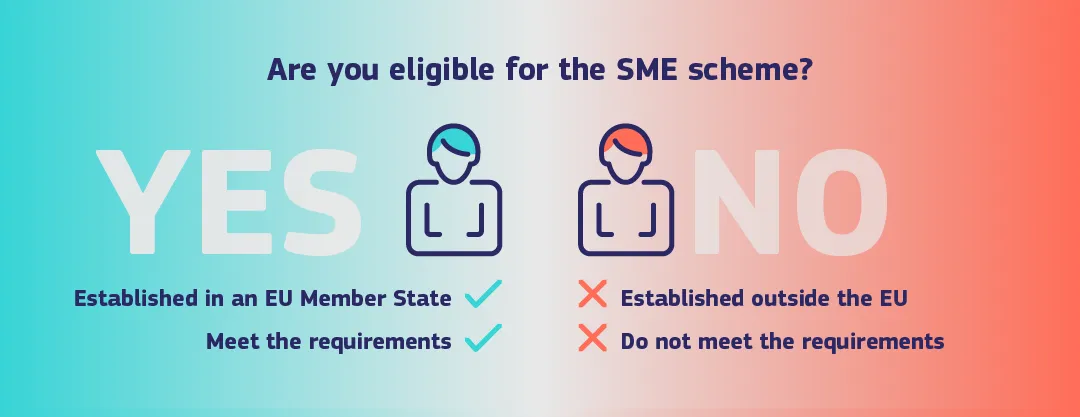
For cross-border EU business clients, apply the reverse charge. This is the EU-wide rule that resolves VAT for most B2B cross-border invoicing. Verify your client’s VAT number via VIES, issue your invoice without VAT, include the reverse charge reference, and include both VAT numbers. If you invoice clients through Ruul instead, Ruul issues the invoice under its own name, with tax and format set by your client’s country.
Keep records: invoices, contracts, expense receipts. Clean records are a standard requirement across all EU member states. They protect you in a VAT audit, they enable you to claim deductions, and they make annual tax filing significantly less painful. Aim to keep records for at least 10 years for any transaction involving OSS registrations.
Consult a local accountant who works with freelancers. The national-level complexity of EU taxation, across 27 systems, with frequent rate and threshold changes, justifies professional guidance. A generalist accountant is better than no accountant. An accountant who regularly works with freelancers in your country is better still.
If you do not have a registered company, you can still invoice internationally. Ruul acts as the legal counterparty: it issues the invoice to your client under its own name, collects the payment and pays you, so you can invoice without a company. Declaring that income where you live stays with you, so ask your accountant which of the steps above apply to you. This is particularly useful if you work with clients across several countries and want one setup for all of them.
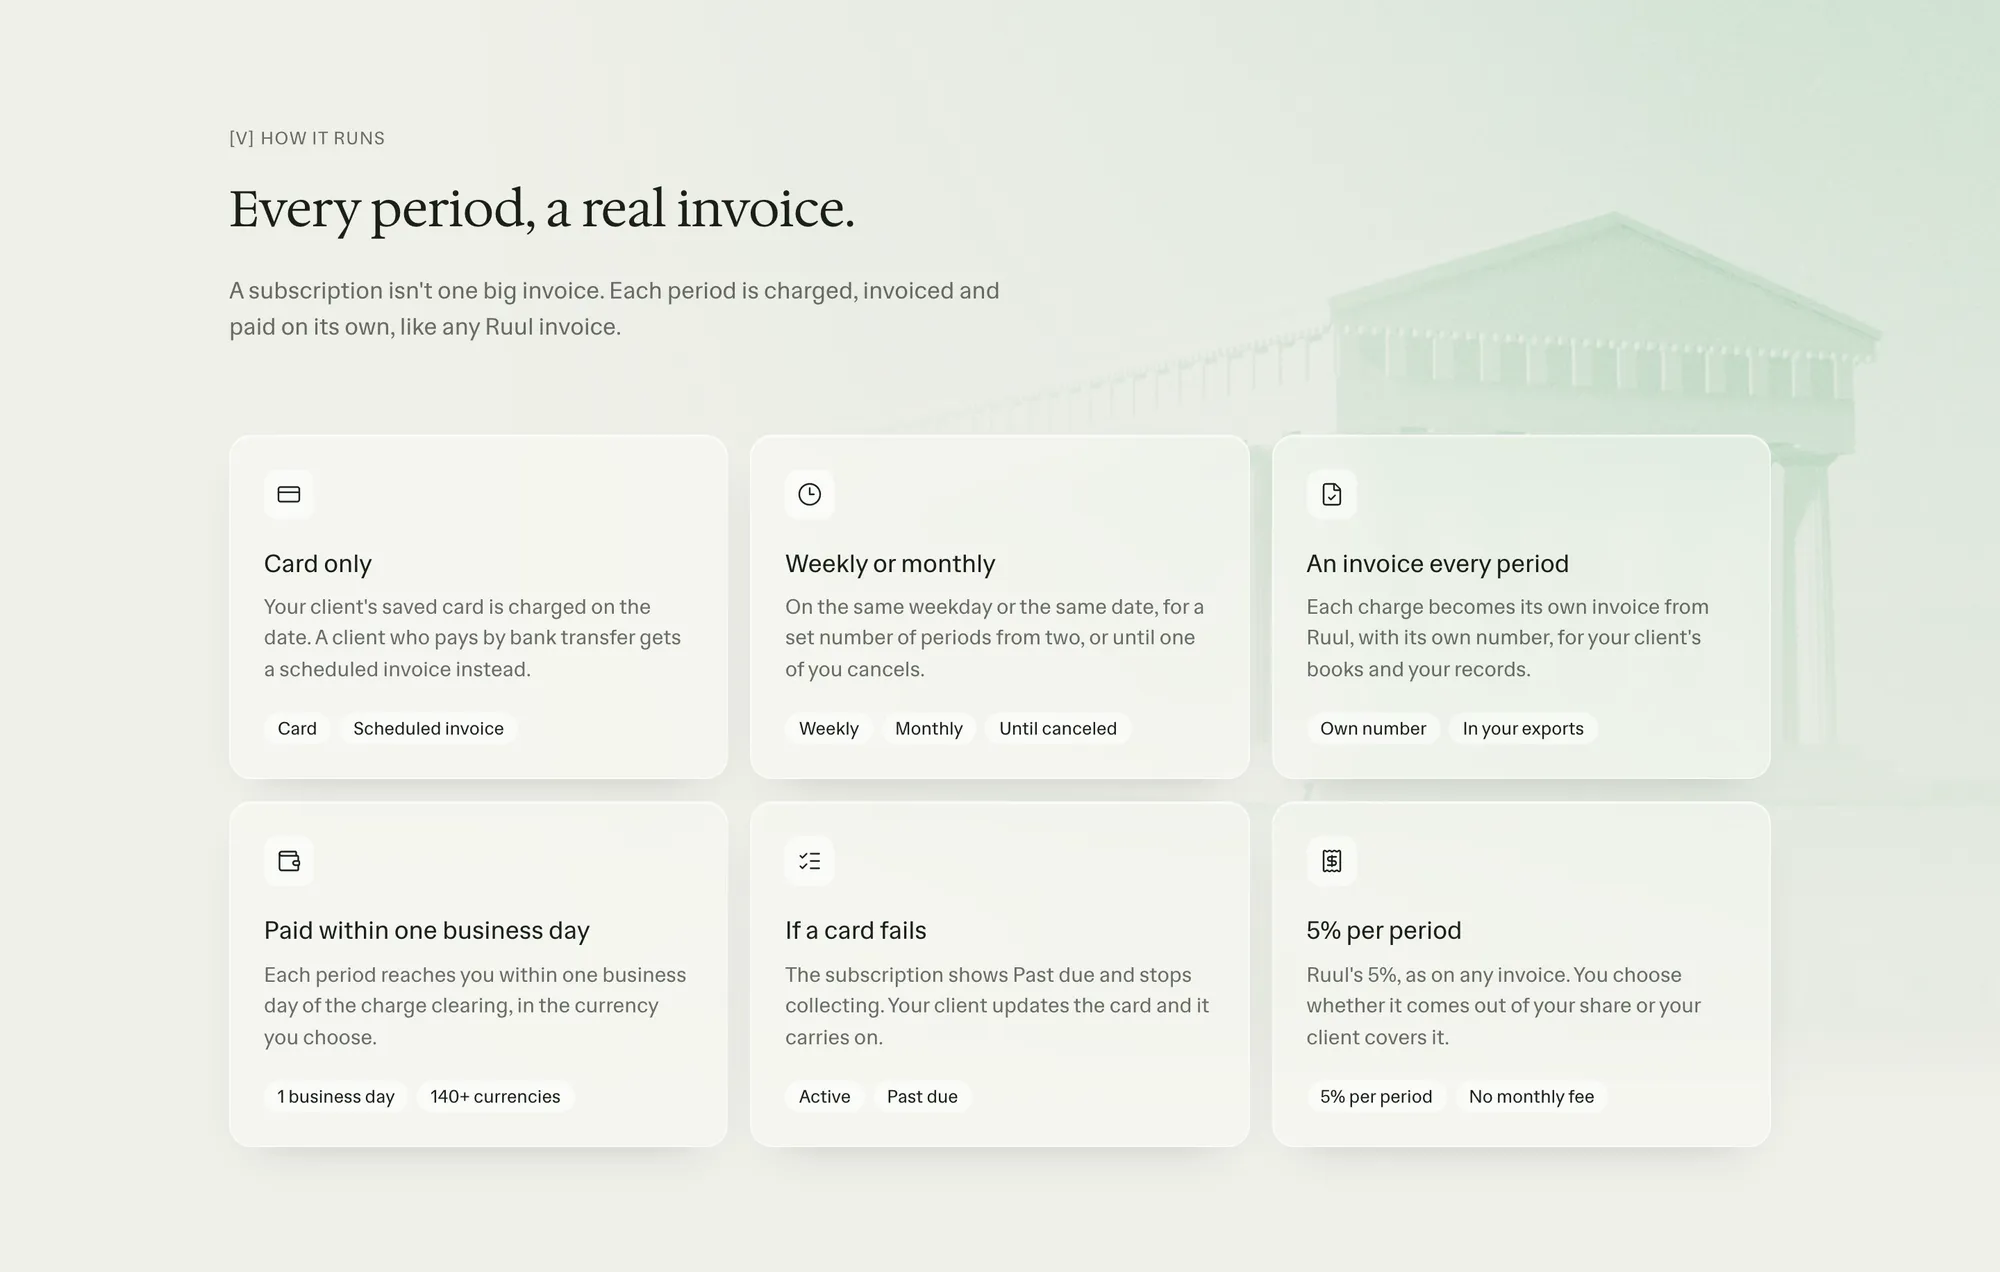
For recurring client work or retainers, subscription invoicing charges your client’s card weekly or monthly and issues an invoice for each period, so you keep a clear paper trail without recreating the same invoice every month.
A note on the UK
The United Kingdom left the European Union in 2020. UK tax rules, including the rules for cross-border services between EU freelancers and UK clients, now follow a different framework and are not covered here. If you work with UK clients, treat those transactions as non-EU for VAT purposes and verify the applicable rules with your adviser.
EU freelance taxation is navigable
The EU is not a single tax system. It is a single VAT framework sitting above 27 separate income tax systems. For the broader fundamentals that apply regardless of country, our freelance taxes guide lays out the core concepts. Once you understand that structure, you know what to handle yourself and what to delegate to a local professional.
The reverse charge handles your VAT for most EU business clients. Your country of residence determines your income tax. Your national registration requirements determine your self-employment status. The rest is documentation and filing.
EU freelance taxation is navigable, with the right local guidance and the right infrastructure. Ruul lets you invoice clients in 190 countries without setting up a company, and pays you within one business day after your client pays, in 140+ currencies. If you prefer crypto, Crypto Payout lets you withdraw in USDC while your clients pay the usual way.
Written by · Co-founder